DASH DoorDash, Inc. - Common Stock
NASDAQ · Hotels, Restaurants & Leisure · View on SEC EDGAR ↗ close Oct 2, 2026 10-K/10-Q Aug 5, 2026DASH Stock Snapshot Price, market cap, P/E, EPS, ROE, debt/equity, 52-week range
DASH Stock Price Chart Daily OHLCV with technical indicators — pan, zoom, and customize your view
Bar granularity adapts to the selected period — hover the chart to see open/high/low/close for a bar.
About DoorDash, Inc. - Common Stock Company overview from Wikipedia
DoorDash, Inc. is an American company operating online food ordering and food delivery. It trades under the symbol DASH. With a 56% market share, DoorDash is the largest food delivery platform in the United States. It also has a 60% market share in the convenience delivery category. As of December 31, 2020, the platform was used by 450,000 merchants, 20 million consumers, and had over one million delivery couriers.
Founded by Tony Xu, Andy Fang, Stanley Tang and Evan Moore, DoorDash made its debut on the Fortune 500 list in 2024, ranking No. 443.
DoorDash has been sued for or held legally liable for withholding tips, reducing tip transparency, antitrust price manipulation, listing restaurants without permission, misclassifying workers, withholding sick time, and illegally selling personal data.
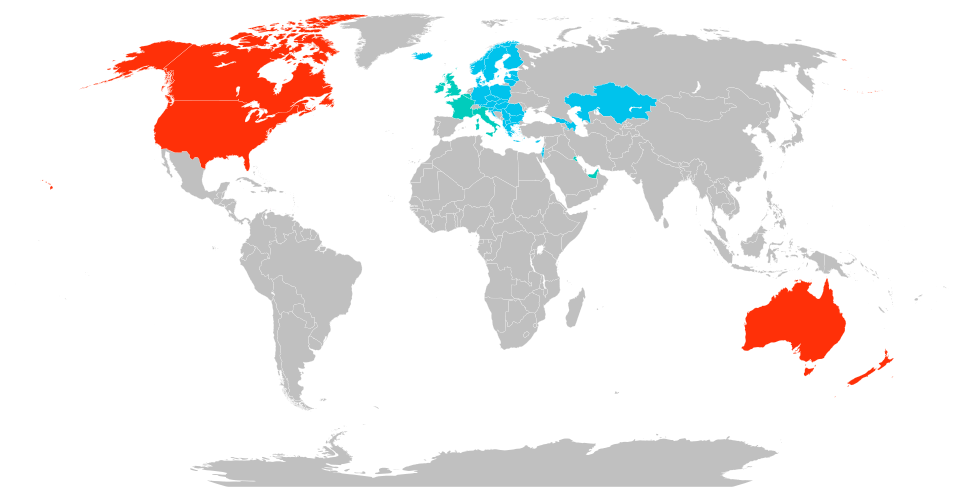
As of April 2026, DoorDash operates in the United States (including Puerto Rico), Canada, Mexico, and Australia. Through its subsidiaries Deliveroo and Wolt, the company also operates across Europe, as well as in Azerbaijan, Georgia, Israel, Kazakhstan, Kuwait, and the United Arab Emirates.
History
In January 2013, Stanford University students Tony Xu, Stanley Tang, Andy Fang and Evan Moore launched PaloAltoDelivery.com in Palo Alto, California. In the summer of 2013, it received US$120,000 in seed money from Y Combinator in exchange for a 7% stake. It incorporated as DoorDash in June 2013.
DoorDash's first partnership with a fast food burger restaurant chain was in April 2016, when it partnered with CKE Restaurants, parent company of Carl's Jr. and Hardee's, for food delivery.
In December 2017, DoorDash announced its partnership with Wendy's for delivery from its restaurants.
In December 2018, DoorDash overtook Uber Eats to hold the second position in total US food delivery sales, behind GrubHub. By March 2019, it had exceeded GrubHub in total sales, at 27.6% of the on-demand delivery market. By early 2019, DoorDash was the largest food delivery provider in the U.S., as measured by consumer spending.
In October 2019, DoorDash opened its first ghost kitchen, DoorDash Kitchen, in Redwood City, California, with four restaurants operating at the location.
By June 2020, DoorDash had raised more than $2.5 billion over several financing rounds from investors including Y Combinator, Charles River Ventures, SV Angel, Khosla Ventures, Sequoia Capital, SoftBank Group, GIC, and Kleiner Perkins. DoorDash announced a partnership with KFC in September 2020, followed by Taco Bell in October 2020.
In November 2020, DoorDash announced the opening of its first physical restaurant location, partnering up with Bay Area restaurant Burma Bites to offer delivery and pick-up orders. In December 2020, it became a public company via an initial public offering, raising $3.37 billion. In November 2021, DoorDash acquired Finland's Wolt for €7bn.
In August 2022, DoorDash announced it would end its partnership with Walmart in September, ending the companies' cooperation agreement from 2018. In November 2022, DoorDash announced plans to lay off 1,250 corporate employees, or about six percent of its workforce, to rein in expenses.
In June 2023, DoorDash announced it would give its drivers the option of earning an hourly minimum wage instead of being paid per delivery. However, drivers are only paid hourly when on an active delivery.
In September 2023, the company transferred its stock listing from the New York Stock Exchange to the Nasdaq. On December 18, 2023, DoorDash was added to the Nasdaq-100 index.
In March 2025, DoorDash announced a partnership with Klarna, a Buy Now, Pay Later (BNPL) service, letting customers schedule small payments over a set period of time. DoorDash received widespread criticism from this decision, including internet mockery, given concerns about the increase of household debt in America.
In 2025, DoorDash acquired the UK-based delivery service Deliveroo for $3.88 billion. The combined company operates in 40 countries and serves 50 million users monthly.
In September 2025, DoorDash and Ace Hardware (the largest hardware cooperative) announced their partnership to offer delivery for home use products from over 4,000 Ace locations.
In June 2026, the NJ Transit Meadowlands Line was renamed to the "Doordash Meadowlands Rail Line" through June 2027, as part of a new partnership with Doordash.
NYC Mayor Zohran Mamdani announced a record $131.5 million settlement with DoorDash on September 22, 2026, resolving what the city called systematic violations of its delivery worker laws that affected about 260,000 workers. DoorDash said the underpayment was a mistake, and it had also spent $1.4m last year trying to stop Mamdani from being elected.
Lawsuits against DoorDash
2017 class-action lawsuit for misclassifying workers
In 2017, a class-action lawsuit was filed against DoorDash for allegedly misclassifying delivery drivers in California and Massachusetts as independent contractors. In 2022, a tentative settlement was reached in which DoorDash would pay $100 million total, with $61 million going to over 900,000 drivers, paying out just over $130 per driver, and $28 million for the lawyers. Gizmodo criticized the settlement, noting that the $413 million that DoorDash CEO Tony Xu received the previous year was one of the largest CEO compensation packages of all time.
2019 data breach lawsuit
On May 4, 2019, DoorDash confirmed 4.9 million customers, delivery workers and merchants had sensitive information stolen via a data breach. Those who joined the platform after April 5, 2018, were unaffected by the breach. A class-action lawsuit for the breach was filed against DoorDash in October 2019.
Withholding of tips and subsequent class-action lawsuits
In July 2019, the company's tipping policy was criticized by The New York Times, and later The Verge and Vox and Gothamist. Drivers receive a guaranteed minimum per order that is paid by DoorDash by default. When a customer added a tip, instead of going directly to the driver, it first went to the company to cover the guaranteed minimum. Drivers then only directly received the part of the tip that exceeded the guaranteed minimum per order.
In January 2020, it was reported that DoorDash had lied about skimming tips from its drivers, causing them to earn an average of $1.45 an hour after expenses, and that after the company had allegedly overhauled its tipping system, DoorDash was still manipulating per-delivery payouts at the expense of drivers.
A DoorDash customer filed a class action lawsuit against the company for its "materially false and misleading" tipping policy. The case was referred to arbitration in August 2020. Under pressure, the company revised its policy. The company settled a lawsuit with District of Columbia Attorney General Karl Racine for $2.5 million, with funds going to deliverers, the government, and to charity.
2021 driver strike for tip transparency
In July 2021, DoorDash drivers went on strike to protest lack of tip transparency and to ask for higher pay. At the time of the strike, and, as of June 2022, DoorDash did not allow drivers to see the full tip amounts prior to accepting a delivery in the app. If customers tip over a set amount for the order total, Doordash hides a portion of the tip until the delivery is complete. The strike occurred after DoorDash rewrote its code to cut off access to Para, a third-party app that drivers had been using to see the full tip amounts.
2025 class-action lawsuit settlement
In 2025, DoorDash agreed to pay around $17 million for "misleading both consumers and delivery workers" with tips being docked from drivers' pay instead of directly going to drivers.
2020 antitrust litigation
In April 2020, in the case of Davitashvili v. GrubHub Inc. DoorDash, Grubhub, Postmates, and Uber Eats were accused of monopolistic power by only listing restaurants on its apps if the restaurant owners signed contracts which include clauses that require prices be the same for dine-in customers as for customers receiving delivery. The plaintiffs stated that this arrangement increases the cost for dine-in customers, as they are required to subsidize the cost of delivery; and that the apps charge "exorbitant" fees, which range from 13% to 40% of revenue, while the average restaurant's profit ranges from 3% to 9% of revenue. The lawsuit seeks treble damages, including for overcharges, since April 14, 2016, for dine-in and delivery customers in the United States at restaurants using the defendants' delivery apps. Although several preliminary documents in the case have now been filed, a trial date has not yet been set.
Litigation for illegal unauthorized restaurant listing
In May 2021, DoorDash was criticized for unauthorized listings of restaurants who had not given permission to appear on the app. The company was sued by Lona's Lil Eats in St. Louis, with the lawsuit claiming that DoorDash had listed them without permission, then prevented any orders to the restaurant from going through and redirecting customers to other restaurants instead, because Lona's was "too far away," when in reality it had not paid DoorDash a fee for listing. This aspect of DoorDash's business practice is illegal in California.
2021 lawsuit by the city of Chicago
In August 2021, the city of Chicago sued DoorDash and GrubHub. According to Chicago mayor Lori Lightfoot, the companies broke the law by using "unfair and deceptive tactics to take advantage of restaurants and consumers who were struggling to stay afloat during the COVID-19 pandemic." DoorDash and GrubHub denied the suit's merits.
2023 class-action lawsuit
DoorDash has been accused of charging users of iPhone more than users on the Android platform. User testing claimed to show several instances of various fees and delivery charges being higher when using an Apple device. DoorDash denied these allegations in response to the ongoing US$1 billion class-action suit.
2023 lawsuit by the city of Seattle
In August 2023, DoorDash was obligated to pay its drivers and the city of Seattle a total of $1.6 million. It was found that the platform made it difficult for users to request paid time off. DoorDash is to pay $1.1 million towards safe and sick time credits, $500k directly to drivers and an additional $8,500 in city fees.
2024 privacy lawsuit by the state of California
In February 2024, after being found to have illegally sold personal data, DoorDash was obligated to pay a $375,000 civil penalty as well as to begin complying with privacy laws it had been shirking, namely CCPA and CalOPPA.
Markets
DoorDash began expanding into international markets in 2015, launching in Toronto, Canada. The company started operating in markets outside North America in 2019, officially launching in Melbourne, Australia, in September and later expanding further into the country. In 2021, the company expanded its service area to Sendai, Japan in June and Stuttgart, Germany, in November. In June 2022, the company expanded into the Wellington Region of New Zealand.
The company expanded its service offerings in 2020, adding grocery delivery initially in California and the Midwest in August 2020. DoorDash expanded the service offerings in 2021 to include DoubleDash, which allows for orders from multiple merchants, and alcohol delivery in 20 U.S. states, Washington, D.C., Canada, and Australia.
Acquisitions
In August 2019, the company acquired Scotty Labs, a tele-operations startup company that focuses on self-driving and remote-controlled vehicle technology. In October 2019, DoorDash acquired Caviar, a service specializing in food delivery from upscale urban-area restaurants that typically do not offer delivery, from Square, Inc. for $410 million. On February 8, 2021, DoorDash announced its acquisition of Chowbotics, a robotics company known for its salad-making robot. The companies did not disclose the terms of the deal, but Chowbotics was valued at $46 million in 2018. On November 9, 2021, DoorDash announced its acquisition of the Finnish technology company Wolt for over $8.1 billion. In March 2022, DoorDash announced its acquisition of Bbot, startup that developed digital ordering and payment solutions for restaurants and hospitality venues.
In April 2025, the company made an initial offer to acquire Deliveroo, a UK-based food delivery company, for £2.7 billion($3.6 billion). In May 2025, DoorDash announced it had acquired Deliveroo for $3.9 billion. In May 2025, DoorDash announced the $1.2 billion all-cash acquisition of restaurant booking platform SevenRooms.
Philanthropy
In 2018, DoorDash launched Project DASH, a partnership with local food security organizations to deliver donations to those in need. By August 2019, the program had expanded to 25 cities in the United States and Canada and had delivered more than one million pounds of food. As of September 2021, Project DASH operated in more than 900 cities and had delivered more than 15 million meals.
DoorDash partnered with the National Urban League in 2020 as part of its Main Street Strong program, pledging $200 million over five years to support restaurants and drivers during the COVID-19 pandemic, $12 million of which was allotted to assisting drivers of color in building job skills and financial literacy.
In 2022, DoorDash partnered with Meals on Wheels to help deliver food to senior citizens.
== Business trend ==
Source: Wikipedia, CC BY-SA 4.0 · View on Wikipedia ↗
10-Year Performance Revenue, net income, margins and EPS trends
Valuation P/E, P/S, P/B, EV/EBITDA ratios — is the stock expensive or cheap?
| Metric | 5Y trend | DASH | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| P/E (TTM) | 98.55Y avg ≈98.9 | ≈98.9 | 26.4 | Overvalued | |
| P/S (TTM) | 5.25Y avg ≈6.2 | ≈6.2 | 2.4 | Overvalued | |
| P/B (MRQ) | 8.35Y avg ≈7.2 | ≈7.2 | 8.1 | Fair value | |
| Price / FCF (TTM) | 31.65Y avg ≈63.0 | ≈63.0 | · | · | |
| Price / Cash Flow (TTM) | 29.05Y avg ≈45.9 | ≈45.9 | 16.6 | Overvalued | |
| Price / Tangible Book (MRQ) | 10.45Y avg ≈17.2 | ≈17.2 | · | · |
Peer median is calculated on a standardized basis per metric and may not always match the TTM/MRQ basis shown for this stock.
Profitability Gross, operating and net margins; ROE, ROA, ROIC
| Metric | 5Y trend | DASH | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Operating Margin (TTM) | 4.5%5Y avg ≈-5.6% | ≈-5.6% | 13.8% | Weak | |
| EBITDA Margin (TTM) | 10.8%5Y avg ≈-0.55% | ≈-0.55% | 17.4% | Weak | |
| Pretax Margin (TTM) | 5.5%5Y avg ≈-5.7% | ≈-5.7% | 14.7% | Weak | |
| Net Profit Margin (TTM) | 5.3%5Y avg ≈-5.8% | ≈-5.8% | 11.3% | Weak | |
| ROA (TTM) | 4.6%5Y avg ≈-7.0% | ≈-7.0% | 10.9% | Weak | |
| ROE (TTM) | 8.9%5Y avg ≈-9.2% | ≈-9.2% | 10.2% | In line |
Financial Health Debt, liquidity, solvency — balance sheet strength
| Metric | 5Y trend | DASH | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Current Ratio (MRQ) | 1.45Y avg ≈1.9 | ≈1.9 | 0.9 | Strong liquidity |
Growth Revenue, EPS and net income growth: YoY, 3Y CAGR, 5Y CAGR
| Metric | 5Y trend | DASH | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Revenue YoY | 27.9%5Y avg ≈37.5% | ≈37.5% | · | · | |
| Revenue CAGR 3Y | 27.7%5Y avg ≈33.9% | ≈33.9% | · | · | |
| Revenue CAGR 5Y | 36.6% | · | · | · | |
| EPS YoY | 634.5% | · | · | · | |
| Net Income YoY | 660.2% | · | · | · |
Capital Efficiency Asset turnover, inventory turnover, receivables turnover
| Metric | 5Y trend | DASH | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Revenue / Employee | ≈$436.8K | · | · | · |
value · ≈ 5Y avg · industry median · verdict relative to median
Earnings History EPS actual vs estimate, surprise %, beat rate, next earnings date
| Period | Report | EPS Actual | EPS Est | Surprise |
|---|---|---|---|---|
| June 30, 2026 | Aug 4, 2026 | $0.46 | $0.47 | -1.2% |
| March 31, 2026 | $0.42 | $0.37 | 13.0% | |
| Dec. 31, 2025 | $0.48 | $0.60 | -19.7% | |
| Sept. 30, 2025 | $0.55 | $0.70 | -22.0% | |
| June 30, 2025 | $0.65 | $0.45 | 44.8% | |
| March 31, 2025 | $0.44 | $0.40 | 10.8% |
Full Fundamentals All metrics by year — income statement, balance sheet, cash flow
Income Statement
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Revenue | $13.72B | $10.72B | $8.63B | $6.58B | $4.89B | $2.89B | $885M | |
| R&D Expense | $1.43B | $1.17B | $1.00B | $829M | $430M | $321M | $107M | |
| SG&A Expense | $1.60B | $1.45B | $1.24B | $1.15B | $797M | $556M | $245M | |
| Operating Expenses | $12.99B | $10.76B | $9.21B | $7.71B | $5.34B | $3.32B | $1.50B | |
| Operating Income | $723M | $-38M | $-579M | $-1.12B | $-452M | $-436M | $-616M | |
| Interest Expense | · | · | · | $2M | $14M | $32M | $0 | |
| Other Non-op | $5M | $-5M | $-107M | $-305M | $0 | $3M | $-68M | |
| Pretax Income | $939M | $156M | $-534M | $-1.40B | $-463M | $-458M | $-666M | |
| Income Tax | $7M | $39M | $31M | $-31M | $5M | $3M | $1M | |
| Net Income | $935M | $123M | $-558M | $-1.36B | $-468M | $-461M | $-667M | |
| EPS (Basic) | $2.19 | $0.30 | $-1.42 | $-3.68 | $-1.39 | $-7.39 | $-15.44 | |
| EPS (Diluted) | $2.13 | $0.29 | $-1.42 | $-3.68 | $-1.39 | $-7.39 | $-15.44 | |
| Shares (Basic) | 427,043,000 | 411,551,000 | 392,948,000 | 371,413,000 | 336,847,000 | 62,390,000 | 43,252,000 | |
| Shares (Diluted) | 439,686,000 | 430,242,000 | 392,948,000 | 371,413,000 | 336,847,000 | 62,390,000 | 43,252,000 | |
| EBITDA | $1.47B | $523M | $-70M | $-755M | $-296M | $-316M | · |
Balance Sheet
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $4.38B | $4.02B | $2.66B | $1.98B | $2.50B | $4.34B | $257M | |
| Receivables | $1.11B | $732M | $533M | $400M | $349M | $291M | $58M | |
| Prepaid Expense | $1.17B | $687M | $525M | $358M | $139M | $221M | $125M | |
| Other Current Assets | $397M | $253M | $146M | · | · | · | · | |
| Current Assets | $8.64B | $7.39B | $5.60B | $4.72B | $4.57B | $5.52B | $998M | |
| Goodwill | $5.52B | $2.31B | $2.43B | $2.37B | $316M | $316M | $306M | |
| Intangibles | $2.26B | $510M | $659M | $765M | $61M | $74M | $103M | |
| Other Non-current Assets | $896M | $632M | $420M | $129M | $68M | $33M | $28M | |
| Total Assets | $19.66B | $12.85B | $10.84B | $9.79B | $6.81B | $6.35B | $1.73B | |
| Accounts Payable | $397M | $321M | $216M | $157M | $161M | $80M | $20M | |
| Accrued Liabilities | $5.64B | $4.05B | $3.13B | $2.33B | $1.57B | $943M | $345M | |
| Current Liabilities | $6.15B | $4.44B | $3.41B | $2.54B | $1.76B | $1.40B | $382M | |
| Capital Leases | $461M | $468M | $454M | $456M | $373M | $238M | $167M | |
| Other Non-current Liabilities | $281M | $129M | $162M | $21M | $9M | $13M | $1M | |
| Total Liabilities | $9.61B | $5.04B | $4.03B | $3.02B | $2.14B | $1.65B | $550M | |
| Common Stock | $0 | $0 | $0 | $0 | $0 | $0 | $0 | |
| Paid-in Capital | $14.09B | $13.16B | $11.89B | $10.63B | $6.75B | $6.31B | $70M | |
| Retained Earnings | $-4.32B | $-5.25B | $-5.15B | $-3.85B | $-2.08B | $-1.61B | $-1.15B | |
| AOCI | $261M | $-107M | $73M | $-33M | $-4M | $0 | · | |
| Stockholders' Equity | $10.03B | $7.80B | $6.81B | $6.75B | $4.67B | $4.70B | $-1.08B | |
| Liabilities + Equity | $19.66B | $12.85B | $10.84B | $9.79B | $6.81B | $6.35B | $1.73B | |
| Shares Outstanding | 434,247,000 | 419,677,000 | 403,228,000 | 391,471,000 | 346,512,000 | 318,503,000 | 43,937,000 |
Cash Flow
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| D&A | $747M | $561M | $509M | $369M | $156M | $120M | $32M | |
| Stock-based Comp | $1.05B | $1.10B | $1.09B | $889M | $486M | $322M | $18M | |
| Deferred Tax | $-37M | $1M | $-1M | $-35M | $1M | $0 | · | |
| Amort. of Intangibles | $212M | $125M | $127M | $99M | $13M | $51M | $7M | |
| Restructuring | $2M | $0 | $2M | $92M | $0 | $0 | · | |
| Other Non-cash | $-265M | $348M | $635M | $509M | $518M | $271M | · | |
| Operating Cash Flow | $2.43B | $2.13B | $1.67B | $367M | $692M | $252M | $-467M | |
| CapEx | $257M | $104M | $123M | $176M | $129M | $106M | $78M | |
| Investing Cash Flow | $-4.39B | $-444M | $-342M | $-300M | $-2.05B | $-192M | $-570M | |
| Stock Repurchased | $0 | $224M | $750M | $400M | $0 | $0 | $0 | |
| Net Stock Activity | $0 | $-224M | $-750M | $-400M | · | $0 | · | |
| Financing Cash Flow | $2.36B | $-204M | $-752M | $-375M | $-483M | $4.00B | $1.11B | |
| Net Change in Cash | $460M | $1.45B | $584M | $-318M | $-1.84B | $4.06B | $72M | |
| Free Cash Flow | $2.17B | $2.03B | $1.55B | $191M | $563M | $146M | · | |
| Levered FCF | · | · | · | $189M | $549M | $114M | · |
Profitability
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Operating Margin | 5.3% | -0.35% | -6.7% | -17.1% | -9.2% | -15.1% | · | |
| Net Margin | 6.8% | 1.1% | -6.5% | -20.7% | -9.6% | -16.0% | · | |
| Pretax Margin | 6.9% | 1.5% | -6.2% | -21.2% | -9.5% | -15.9% | · | |
| EBITDA Margin | 10.7% | 4.9% | -0.81% | -11.5% | -6.1% | -10.9% | · | |
| ROA | · | 1.0% | -5.4% | -16.4% | -7.1% | -11.4% | · | |
| ROE | · | 1.6% | -8.3% | -20.1% | -10.0% | -26.4% | · | |
| ROIC | · | -0.37% | -9.0% | -16.3% | -9.8% | -9.3% | · |
Liquidity & Solvency
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Current Ratio | · | 1.7 | 1.6 | 1.9 | 2.6 | 3.9 | · | |
| Quick Ratio | · | 1.1 | 0.9 | 0.9 | 1.6 | 3.3 | · | |
| Interest Coverage | · | · | · | -562.0 | -32.3 | -13.6 | · |
Efficiency
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Asset Turnover | · | 0.9 | 0.8 | 0.8 | 0.7 | 0.7 | · | |
| Receivables Turnover | · | 17.0 | 18.5 | 17.6 | 15.3 | 16.5 | · |
Per Share
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Book Value / Share | · | $18.59 | $16.88 | $17.25 | $13.47 | $14.76 | · | |
| Revenue / Share | $31.20 | $24.92 | $21.97 | $17.72 | $14.51 | · | · | |
| Cash Flow / Share | $5.53 | $4.96 | $4.26 | $0.99 | $2.05 | · | · | |
| Cash / Share | · | $9.58 | $6.59 | $5.05 | $7.23 | $13.64 | · | |
| EPS (TTM) | $2.13 | $0.29 | $-1.42 | $-3.68 | $-1.39 | $-7.39 | · |
Growth Rates
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Revenue YoY | 27.9% | 24.2% | 31.2% | 34.7% | 69.4% | · | · | |
| Revenue CAGR 3Y | 27.7% | 29.9% | 44.1% | · | · | · | · | |
| Revenue CAGR 5Y | 36.6% | · | · | · | · | · | · | |
| EPS YoY | 634.5% | · | · | · | · | · | · | |
| Net Income YoY | 660.2% | · | · | · | · | · | · |
Valuation (TTM)
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $13.72B | $10.72B | $8.63B | $6.58B | $4.89B | $2.89B | · | |
| Net Income TTM | $935M | $123M | $-558M | $-1.36B | $-468M | $-461M | · | |
| Market Cap | · | $70.40B | $39.88B | $19.11B | $51.60B | $45.47B | · | |
| P/E | 106.3 | 578.4 | -69.6 | -13.3 | -107.1 | -19.3 | · | |
| P/S | · | 6.6 | 4.6 | 2.9 | 10.6 | 15.8 | · | |
| P/B | · | 9.0 | 5.9 | 2.8 | 11.1 | 9.7 | · | |
| P / Tangible Book | 43.6 | 14.1 | 10.7 | 5.3 | 12.0 | 10.5 | · | |
| P / Cash Flow | · | 33.0 | 23.8 | 52.1 | 74.6 | 180.4 | · | |
| P / FCF | · | 34.7 | 25.7 | 100.1 | 91.6 | 311.4 | · | |
| Earnings Yield | 0.94% | 0.17% | -1.4% | -7.5% | -0.93% | -5.2% | · |
Income Statement
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $4.45B | $4.04B | $3.96B | $3.45B | $3.28B | $3.03B | $2.87B | $2.71B | $2.63B | $2.51B | $2.30B | $2.16B | $2.13B | $2.04B | $1.82B | $1.70B | |
| R&D Expense | $535M | $398M | $419M | $355M | $351M | $306M | $297M | $289M | $303M | $279M | $253M | $250M | $269M | $231M | $250M | $226M | |
| SG&A Expense | $538M | $432M | $480M | $400M | $388M | $332M | $324M | $315M | $494M | $319M | $320M | $289M | $341M | $285M | $300M | $311M | |
| Operating Expenses | $4.30B | $3.88B | $3.81B | $3.19B | $3.12B | $2.88B | $2.76B | $2.60B | $2.83B | $2.57B | $2.39B | $2.27B | $2.34B | $2.21B | $2.19B | $2.01B | |
| Operating Income | $156M | $151M | $147M | $258M | $163M | $155M | $117M | $107M | $-201M | $-61M | $-89M | $-108M | $-211M | $-171M | $-370M | $-308M | |
| Interest Expense | · | · | · | · | · | · | · | · | · | · | · | · | · | $1M | · | $0 | |
| Other Non-op | $16M | $6M | $33M | $-81M | $59M | $-6M | $8M | $-6M | $-5M | $-2M | $-101M | $-1M | $-4M | $-1M | $-305M | $-2M | |
| Pretax Income | $207M | $191M | $222M | $248M | $271M | $198M | $176M | $155M | $-157M | $-18M | $-139M | $-69M | $-181M | $-145M | $-659M | $-301M | |
| Income Tax | $8M | $8M | $9M | $5M | $-13M | $6M | $37M | $-6M | $1M | $7M | $17M | $6M | $-9M | $17M | $-17M | $-5M | |
| Net Income | $200M | $184M | $213M | $244M | $285M | $193M | $141M | $162M | $-157M | $-23M | $-154M | $-73M | $-170M | $-161M | $-640M | $-295M | |
| EPS (Basic) | $0.46 | $0.42 | $0.49 | $0.57 | $0.67 | $0.46 | $0.35 | $0.39 | $-0.38 | $-0.06 | $-0.38 | $-0.19 | $-0.44 | $-0.41 | $-1.71 | $-0.77 | |
| EPS (Diluted) | $0.46 | $0.42 | $0.49 | $0.55 | $0.65 | $0.44 | $0.35 | $0.38 | $-0.38 | $-0.06 | $-0.38 | $-0.19 | $-0.44 | $-0.41 | $-1.71 | $-0.77 | |
| Shares (Basic) | 434,425,000 | 435,429,000 | · | 428,911,000 | 425,113,000 | 421,422,000 | · | 413,106,000 | 410,482,000 | 405,482,000 | · | 393,217,000 | 388,737,000 | 390,397,000 | · | 384,756,000 | |
| Shares (Diluted) | 439,345,000 | 442,326,000 | · | 441,812,000 | 438,377,000 | 435,563,000 | · | 427,962,000 | 410,482,000 | 405,482,000 | · | 393,217,000 | 388,737,000 | 390,397,000 | · | 384,756,000 | |
| EBITDA | $451M | $420M | · | $427M | $322M | $307M | · | $245M | $-61M | $81M | · | $20M | $-83M | $-48M | · | $-190M |
Balance Sheet
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $4.42B | $4.58B | $4.38B | $3.28B | $3.91B | $4.50B | $4.02B | $3.66B | $3.43B | $3.12B | $2.66B | $2.34B | $1.90B | $1.83B | $1.98B | $2.32B | |
| Receivables | $1.10B | $1.03B | $1.11B | $894M | $840M | $782M | $732M | $622M | $585M | $546M | · | $417M | $383M | $382M | · | $325M | |
| Prepaid Expense | $1.15B | $1.12B | $1.17B | $899M | $824M | $730M | $687M | $839M | $782M | $700M | · | $519M | $469M | $509M | · | $302M | |
| Other Current Assets | $440M | $425M | $397M | $362M | $386M | $295M | $253M | · | · | · | · | · | · | · | · | · | |
| Current Assets | $8.42B | $8.59B | $8.64B | $10.49B | $9.73B | $7.85B | $7.39B | $6.76B | $6.62B | $6.13B | · | $5.14B | $4.61B | $4.59B | · | $4.69B | |
| Goodwill | $5.50B | $5.50B | $5.52B | $3.57B | $3.53B | $2.41B | $2.31B | $2.46B | $2.37B | $2.39B | $2.43B | $2.35B | $2.40B | $2.40B | $2.37B | $2.20B | |
| Intangibles | $2.00B | $2.12B | $2.26B | $878M | $890M | $504M | $510M | $577M | $586M | $621M | · | $663M | $708M | $743M | · | $735M | |
| Other Non-current Assets | $1.08B | $1.07B | $896M | $809M | $774M | $731M | $632M | $519M | $458M | $456M | · | $140M | $131M | $126M | · | $125M | |
| Total Assets | $19.56B | $19.71B | $19.66B | $17.97B | $16.95B | $13.57B | $12.85B | $12.28B | $11.84B | $11.45B | · | $10.01B | $9.60B | $9.65B | · | $9.55B | |
| Accounts Payable | $301M | $268M | $397M | $257M | $345M | $329M | $321M | $191M | $163M | $203M | · | $149M | $173M | $208M | · | $238M | |
| Accrued Liabilities | $5.75B | $5.65B | $5.64B | $4.79B | $4.27B | $4.18B | $4.05B | $3.84B | $3.80B | $3.48B | · | $2.77B | $2.50B | $2.39B | · | $1.93B | |
| Current Liabilities | $6.15B | $6.03B | $6.15B | $5.13B | $4.70B | $4.58B | $4.44B | $4.09B | $4.03B | $3.74B | · | $2.99B | $2.73B | $2.65B | · | $2.22B | |
| Capital Leases | $474M | $457M | $461M | $454M | $452M | $457M | $468M | $466M | $470M | $483M | · | $430M | $440M | $437M | · | $460M | |
| Other Non-current Liabilities | $276M | $293M | $281M | $155M | $153M | $143M | $129M | $139M | $167M | $214M | · | $29M | $28M | $27M | · | $35M | |
| Total Liabilities | $9.63B | $9.50B | $9.61B | $8.46B | $8.02B | $5.18B | $5.04B | $4.70B | $4.67B | $4.44B | · | $3.44B | $3.19B | $3.12B | · | $2.71B | |
| Common Stock | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | · | $0 | $0 | $0 | · | $0 | |
| Paid-in Capital | $14.81B | $14.38B | $14.09B | $13.76B | $13.44B | $13.44B | $13.16B | $12.84B | $12.52B | $12.18B | · | $11.58B | $11.26B | $10.90B | · | $10.32B | |
| Retained Earnings | $-4.99B | $-4.30B | $-4.32B | $-4.53B | $-4.78B | $-5.06B | $-5.25B | $-5.40B | $-5.34B | $-5.18B | · | $-4.95B | $-4.87B | $-4.40B | · | $-3.21B | |
| Treasury Stock | · | $162M | · | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| AOCI | $101M | $117M | $261M | $268M | $261M | $7M | $-107M | $122M | $-25M | $-1M | · | $-68M | $9M | $18M | · | $-292M | |
| Stockholders' Equity | $9.92B | $10.20B | $10.03B | $9.49B | $8.92B | $8.39B | $7.80B | $7.57B | $7.16B | $7.00B | $6.81B | $6.56B | $6.40B | $6.52B | $6.75B | $6.83B | |
| Liabilities + Equity | $19.56B | $19.71B | $19.66B | $17.97B | $16.95B | $13.57B | $12.85B | $12.28B | $11.84B | $11.45B | · | $10.01B | $9.60B | $9.65B | · | $9.55B | |
| Shares Outstanding | 433,256,000 | 435,955,000 | 434,247,000 | 430,907,000 | 426,915,000 | 423,627,000 | 419,677,000 | 415,162,000 | 413,140,000 | 408,512,000 | 403,228,000 | 398,386,000 | 392,652,000 | 389,756,000 | 391,471,000 | 388,137,000 |
Cash Flow
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $295M | $269M | $267M | $169M | $159M | $152M | $141M | $138M | $140M | $142M | $130M | $128M | $128M | $123M | $111M | $118M | |
| Stock-based Comp | $349M | $231M | $276M | $258M | $282M | $235M | $271M | $274M | $302M | $252M | $269M | $278M | $311M | $230M | $280M | $249M | |
| Amort. of Intangibles | $114M | $114M | $113M | $36M | $32M | $31M | $31M | $32M | $31M | $31M | $30M | $30M | $34M | $33M | $32M | $45M | |
| Restructuring | $2M | $48M | $0 | $1M | $0 | $1M | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $2M | $84M | $5M | |
| Other Non-cash | · | $-90M | · | · | · | $55M | · | · | · | $182M | · | · | · | $205M | · | · | |
| Operating Cash Flow | $944M | $594M | $421M | $871M | $504M | $635M | $518M | $531M | $530M | $553M | $485M | $398M | $393M | $397M | $23M | $199M | |
| CapEx | $61M | $57M | $54M | $63M | $66M | $74M | $32M | $32M | $23M | $17M | $29M | $28M | $27M | $39M | $45M | $54M | |
| Investing Cash Flow | $-188M | $-98M | $-3.12B | $-173M | $-941M | $-160M | $-163M | $-62M | $-147M | $-72M | $-119M | $-78M | $-135M | $-10M | $-181M | $-199M | |
| Stock Repurchased | $887M | $162M | $0 | $0 | $0 | $0 | $0 | $217M | $7M | $0 | $51M | $6M | $301M | $392M | $0 | $400M | |
| Net Stock Activity | · | $-162M | · | · | · | · | · | · | · | $0 | · | · | · | $-392M | · | · | |
| Financing Cash Flow | $-896M | $-173M | $-19M | $1M | $2.38B | $3M | $7M | $-213M | $-5M | $7M | $-50M | $-4M | $-308M | $-390M | $1M | $-384M | |
| Net Change in Cash | $-136M | $301M | $-2.72B | $699M | $1.99B | $493M | $323M | $278M | $373M | $475M | $337M | $302M | $-53M | $-2M | $-139M | $-404M | |
| Free Cash Flow | · | $537M | · | · | · | $561M | · | · | · | $536M | · | · | · | $358M | · | · | |
| Levered FCF | · | · | · | · | · | · | · | · | · | · | · | · | · | $357M | · | · |
Profitability
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | 3.5% | 3.7% | · | 7.5% | 5.0% | 5.1% | · | 4.0% | -7.6% | -2.4% | · | -5.0% | -9.9% | -8.4% | · | -18.1% | |
| Net Margin | 4.5% | 4.6% | · | 7.1% | 8.7% | 6.4% | · | 6.0% | -6.0% | -0.92% | · | -3.4% | -8.0% | -7.9% | · | -17.3% | |
| Pretax Margin | 4.7% | 4.7% | · | 7.2% | 8.2% | 6.5% | · | 5.7% | -6.0% | -0.72% | · | -3.2% | -8.5% | -7.1% | · | -17.7% | |
| EBITDA Margin | 10.1% | 10.4% | · | 12.4% | 9.8% | 10.1% | · | 9.0% | -2.3% | 3.2% | · | 0.92% | -3.9% | -2.4% | · | -11.2% | |
| ROA | 1.1% | 1.1% | · | 1.6% | 2.0% | 1.5% | · | 1.5% | -1.5% | -0.22% | · | -0.75% | -1.7% | -2.0% | · | -3.7% | |
| ROE | 2.1% | 2.0% | · | 2.9% | 3.5% | 2.5% | · | 2.3% | -2.3% | -0.34% | · | -1.1% | -2.5% | -2.9% | · | -5.1% | |
| ROIC | 1.5% | 1.4% | · | 2.7% | 1.9% | 1.8% | · | 1.5% | -2.8% | -1.2% | · | -1.8% | -3.1% | -2.9% | · | -4.4% |
Liquidity & Solvency
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.4 | 1.4 | · | 2.0 | 2.1 | 1.7 | · | 1.7 | 1.6 | 1.6 | · | 1.7 | 1.7 | 1.7 | · | 2.1 | |
| Quick Ratio | 0.9 | 0.9 | · | 0.8 | 1.0 | 1.2 | · | 1.0 | 1.0 | 1.0 | · | 0.9 | 0.8 | 0.8 | · | 1.2 | |
| Interest Coverage | · | · | · | · | · | · | · | · | · | · | · | · | · | -171.0 | · | · |
Efficiency
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | |
| Receivables Turnover | 4.6 | 4.4 | · | 4.5 | 4.6 | 4.6 | · | 5.2 | 5.4 | 5.4 | · | 5.8 | 5.9 | 5.8 | · | 5.6 |
Per Share
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $22.90 | $23.39 | · | $22.03 | $20.90 | $19.80 | · | $18.23 | $17.34 | $17.13 | · | $16.46 | $16.29 | $16.72 | · | $17.58 | |
| Revenue / Share | $10.14 | $9.12 | · | $7.80 | $7.49 | $6.96 | · | $6.32 | $6.41 | $6.20 | · | $5.50 | $5.49 | $5.21 | · | $4.42 | |
| Cash Flow / Share | · | $1.34 | · | · | · | $1.46 | · | · | · | $1.36 | · | · | · | $1.02 | · | · | |
| Cash / Share | $10.21 | $10.49 | · | $7.61 | $9.16 | $10.62 | · | $8.83 | $8.30 | $7.65 | · | $5.88 | $4.85 | $4.70 | · | $5.98 | |
| EPS (TTM) | $1.92 | $2.11 | · | $1.99 | $1.82 | $0.79 | · | $-0.44 | $-1.01 | $-1.07 | · | $-2.75 | $-3.33 | $-3.61 | · | $-2.42 |
Valuation (TTM)
| Metric | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $15.89B | $14.72B | · | $12.63B | $11.89B | $11.24B | · | $10.15B | $9.61B | $9.11B | · | $8.15B | $7.69B | $7.16B | · | $6.07B | |
| Net Income TTM | $841M | $926M | · | $863M | $781M | $339M | · | $-172M | $-407M | $-420M | · | $-1.04B | $-1.27B | $-1.36B | · | $-880M | |
| Market Cap | $79.95B | $65.46B | · | $117.20B | $105.24B | $77.43B | · | $59.26B | $44.94B | $56.26B | · | $31.66B | $30.01B | $24.77B | · | $19.19B | |
| P/E | 96.1 | 71.2 | · | 136.7 | 135.4 | 231.4 | · | -324.4 | -107.7 | -128.7 | · | -28.9 | -22.9 | -17.6 | · | -20.4 | |
| P/S | 5.0 | 4.4 | · | 9.3 | 8.8 | 6.9 | · | 5.8 | 4.7 | 6.2 | · | 3.9 | 3.9 | 3.5 | · | 3.2 | |
| P/B | 8.1 | 6.4 | · | 12.3 | 11.8 | 9.2 | · | 7.8 | 6.3 | 8.0 | · | 4.8 | 4.7 | 3.8 | · | 2.8 | |
| P / Tangible Book | 33.0 | 25.4 | · | 23.2 | 23.4 | 14.1 | · | 13.1 | 10.7 | 14.1 | · | 8.9 | 9.1 | 7.3 | · | 4.9 | |
| P / Cash Flow | · | 110.2 | · | · | · | 121.9 | · | · | · | 101.7 | · | · | · | 62.4 | · | · | |
| Earnings Yield | 1.0% | 1.4% | · | 0.73% | 0.74% | 0.43% | · | -0.31% | -0.93% | -0.78% | · | -3.5% | -4.4% | -5.7% | · | -4.9% |
Most recent period on the left · null values shown as ·
Financial Statements Income statement, balance sheet, cash flow — annual, last 5 years
| Metric | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Revenue | $13.72B | $10.72B | $8.63B | $6.58B | $4.89B |
| Operating Margin % | 5.3% | -0.35% | -6.7% | -17.1% | -9.2% |
| Net Income | $935M | $123M | $-558M | $-1.36B | $-468M |
| Diluted EPS | $2.13 | $0.29 | $-1.42 | $-3.68 | $-1.39 |
| Metric | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Current Ratio | · | 1.7 | 1.6 | 1.9 | 2.6 |
| Quick Ratio | · | 1.1 | 0.9 | 0.9 | 1.6 |
| Metric | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Free Cash Flow | $2.17B | $2.03B | $1.55B | $191M | $563M |
Institutional owners (13F) 1,169 filers · $79.2B total · As of Sept. 30, 2026
Institutions that report holding this stock in their quarterly SEC Form 13F. Long positions only; a single filer may appear twice for separate option legs. Large offsetting put/call legs typically reflect market-making or hedged inventory, not directional conviction.
| New positions | Exited positions | Increased | Decreased | Net shares change |
|---|---|---|---|---|
| 171 (+10 vs prior Q) | 120 (-64 vs prior Q) | 412 (+13 vs prior Q) | 372 (-38 vs prior Q) | +12.6M |
Compared to Q1 2026. SEC Form 13F filings are due within 45 days of quarter-end plus a short buffer for late filers — quarters still inside that window are skipped in favor of the most recent fully-reported pair.
| Institution | Value | Shares | % of tracked 13F | Type |
|---|---|---|---|---|
| VANGUARD GROUP INC | $9,835,228,964 | 43,426,479 | 12.41% | Shares |
| SC US (TTGP), LTD. | $5,830,240,851 | 31,595,084 | 7.36% | Shares |
| BlackRock, Inc. | $4,957,203,515 | 26,863,944 | 6.26% | Shares |
| VANGUARD CAPITAL MANAGEMENT LLC | $4,511,093,823 | 24,446,398 | 5.69% | Shares |
| VANGUARD PORTFOLIO MANAGEMENT LLC | $3,224,942,236 | 17,476,520 | 4.07% | Shares |
| STATE STREET CORP | $2,971,424,957 | 16,102,666 | 3.75% | Shares |
| MORGAN STANLEY | $2,678,183,152 | 14,513,536 | 3.38% | Shares |
| JPMORGAN CHASE & CO | $2,483,553,075 | 13,437,684 | 3.13% | Shares |
| Invesco Ltd. | $2,409,705,629 | 13,058,612 | 3.04% | Shares |
| Capital Research Global Investors | $2,019,671,813 | 10,944,937 | 2.55% | Shares |
| Capital World Investors | $1,917,374,215 | 10,390,570 | 2.42% | Shares |
| GEODE CAPITAL MANAGEMENT, LLC | $1,668,238,570 | 9,080,148 | 2.11% | Shares |
| Newlands Management Operations LLC | $1,304,313,214 | 7,068,299 | 1.65% | Shares |
| BAILLIE GIFFORD & CO | $1,256,411,994 | 6,808,714 | 1.59% | Shares |
| JANUS HENDERSON GROUP PLC | $1,159,377,028 | 7,762,553 | 1.46% | Shares |
| FMR LLC | $971,714,735 | 5,265,890 | 1.23% | Shares |
| NORGES BANK | $914,956,760 | 4,958,309 | 1.15% | Shares |
| GOLDMAN SACHS GROUP INC | $851,792,231 | 4,616,010 | 1.08% | Shares |
| BANK OF AMERICA CORP /DE/ | $839,705,896 | 4,550,512 | 1.06% | Shares |
| Durable Capital Partners LP | $766,571,389 | 4,154,183 | 0.97% | Shares |
| PARNASSUS INVESTMENTS, LLC | $717,176,767 | 3,886,505 | 0.91% | Shares |
| WELLINGTON MANAGEMENT GROUP LLP | $708,782,683 | 3,841,016 | 0.89% | Shares |
| Temasek Holdings (Private) Ltd | $638,750,780 | 3,461,501 | 0.81% | Shares |
| NORTHERN TRUST CORP | $604,209,715 | 3,274,317 | 0.76% | Shares |
| JANE STREET GROUP, LLC | $573,150,180 | 3,106,000 | 0.72% | Call option |
| CHARLES SCHWAB INVESTMENT MANAGEMENT INC | $563,343,886 | 3,052,858 | 0.71% | Shares |
| WELLCOME TRUST LTD (THE) as trustee of the WELLCOME TRUST | $553,590,000 | 3,000,000 | 0.70% | Shares |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $482,915,010 | 2,617,000 | 0.61% | Call option |
| UBS AM, a distinct business unit of UBS ASSET MANAGEMENT AMERICAS LLC | $458,530,474 | 3,053,816 | 0.58% | Shares |
| Artisan Partners Limited Partnership | $440,184,162 | 2,385,434 | 0.56% | Shares |
| Bank of New York Mellon Corp | $436,065,524 | 2,363,114 | 0.55% | Shares |
| SANDS CAPITAL MANAGEMENT, LLC | $429,178,951 | 2,325,795 | 0.54% | Shares |
| UBS Group AG | $424,551,309 | 2,300,717 | 0.54% | Shares |
| VANGUARD FIDUCIARY TRUST CO | $399,972,466 | 2,167,520 | 0.50% | Shares |
| Legal & General Group Plc | $394,699,439 | 2,138,939 | 0.50% | Shares |
| Amundi | $387,252,812 | 2,098,590 | 0.49% | Shares |
| ALKEON CAPITAL MANAGEMENT LLC | $381,977,098 | 2,070,000 | 0.48% | Call option |
| AMERIPRISE FINANCIAL INC | $370,331,889 | 2,006,812 | 0.47% | Shares |
| PointState Capital LP | $337,687,501 | 1,829,987 | 0.43% | Shares |
| FIRST TRUST ADVISORS LP | $336,799,845 | 1,825,177 | 0.43% | Shares |
| FRANKLIN RESOURCES INC | $327,487,974 | 1,774,714 | 0.41% | Shares |
| Nuveen, LLC | $283,544,258 | 1,536,576 | 0.36% | Shares |
| Foxhaven Asset Management, LP | $266,988,707 | 1,446,858 | 0.34% | Shares |
| NOMURA ASSET MANAGEMENT INTERNATIONAL INC. | $259,072,000 | 1,403,958 | 0.33% | Shares |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $252,713,835 | 1,369,500 | 0.32% | Put option |
| D1 Capital Partners L.P. | $240,572,684 | 1,303,705 | 0.30% | Shares |
| WOLVERINE TRADING, LLC | $239,636,500 | 879,400 | 0.30% | Call option |
| BNP PARIBAS FINANCIAL MARKETS | $236,166,292 | 1,279,826 | 0.30% | Shares |
| PRINCIPAL FINANCIAL GROUP INC | $229,065,340 | 1,241,295 | 0.29% | Shares |
| DIMENSIONAL FUND ADVISORS LP | $228,367,246 | 1,237,545 | 0.29% | Shares |
Company insiders 20 insiders · 7 officers · 13 directors
| Insider | Role | Last activity | Shares owned | Buys 12m | Sells 12m | Net 12m |
|---|---|---|---|---|---|---|
| Tony Xu | CHIEF EXECUTIVE OFFICER | Sept. 3, 2026 J | 1,500 | 0 | 15 | $-88,705,441 |
| Ravi Inukonda | CHIEF FINANCIAL OFFICER | Sept. 1, 2026 M | 217,911 | 0 | 36 | $-27,417,019 |
| Prabir Adarkar | PRESIDENT AND COO | Sept. 28, 2026 S | 921,473 | 0 | 71 | $-59,160,684 |
| Christopher D Payne | President and COO | Feb. 28, 2023 S | 322,951 | 0 | 0 | $0 |
| Keith Yandell | CHIEF BUSINESS OFFICER | Sept. 17, 2026 S | 120,688 | 0 | 28 | $-6,562,271 |
| Gordon S Lee | CHIEF ACCOUNTING OFFICER | Sept. 4, 2026 S | 83,919 | 0 | 11 | $-4,057,453 |
| Tia Sherringham | GENERAL COUNSEL AND SECRETARY | Aug. 24, 2026 S | 118,262 | 0 | 17 | $-8,803,608 |
| Stanley Tang | Director | Sept. 2, 2026 J | 10,361 | 0 | 95 | $-114,670,597 |
| Andy Fang | Director | Sept. 1, 2026 J | 0 | 0 | 69 | $-43,760,427 |
| Alfred Lin | Director | Aug. 7, 2026 J | 877,117 | 11 | 0 | $100,277,893 |
| Shona L Brown | Director | June 26, 2026 S | 31,156 | 0 | 13 | $-2,164,314 |
| Milan Kovac | Director | June 10, 2026 A | 3,928 | 2 | 0 | $6,238 |
| Ashley Still | Director | June 10, 2026 S | 2,685 | 0 | 6 | $-250,828 |
| Elinor Mertz | Director | June 10, 2026 A | 15,809 | 0 | 0 | $0 |
| Jeffrey M Blackburn | Director | June 10, 2026 A | 8,102 | 0 | 0 | $0 |
| Diego Piacentini | Director | June 10, 2026 A | 13,350 | 0 | 0 | $0 |
| DOERR L JOHN | Director | June 10, 2026 A | 9,069 | 0 | 0 | $0 |
| Gregory K Peters | Director | June 20, 2023 A | 9,818 | 0 | 0 | $0 |
| Stanley J Meresman | Director | May 24, 2023 S | 3,557 | 0 | 0 | $0 |
| Maria Renz | · | June 22, 2021 A | 11,408 | 0 | 0 | $0 |
Insiders from SEC Form 3/4/5 filings; net = open-market P/S only
ETF ownership Held by 125 ETFs
Weight reflects direct equity holdings (N-PORT) only; leveraged or derivative-based funds may hold additional swap exposure not shown.
| Fund | Weight | Units | As of | Source |
|---|---|---|---|---|
| FDND · First Trust Exchange-Traded Fund IV | 2.93% | 1,457 NS | July 31, 2026 | N-PORT |
| JXX · Janus Detroit Street Trust | 2.64% | 3,590 NS | July 31, 2026 | N-PORT |
| RSPD · Invesco Exchange-Traded Fund Trust | 2.05% | 40,724 SH | Oct. 1, 2026 | Daily |
| PNQI · Invesco Exchange-Traded Fund Trust | 2.01% | 58,378 SH | Oct. 1, 2026 | Daily |
| WEBL · Direxion Shares ETF Trust | 1.90% | 9,058 NS | July 31, 2026 | N-PORT |
| ARKX · ARK ETF Trust | 1.78% | 68,997 NS | July 31, 2026 | N-PORT |
| QNXT · iShares Trust | 1.58% | 2,152 SH | Sept. 11, 2026 | Daily |
| ARKF · ARK ETF Trust | 1.58% | 56,481 NS | July 31, 2026 | N-PORT |
| ARKQ · ARK ETF Trust | 1.52% | 143,833 NS | July 31, 2026 | N-PORT |
| VOT · VANGUARD INDEX FUNDS | 1.50% | 2,836,119 SH | Aug. 19, 2026 | Daily |
| QQQE · Direxion Shares ETF Trust | 1.25% | 85,333 NS | July 31, 2026 | N-PORT |
| RXI · iShares Trust | 1.22% | 14,972 SH | Sept. 11, 2026 | Daily |
| FDIS · FIDELITY COVINGTON TRUST | 1.17% | 100,427 NS | July 31, 2026 | N-PORT |
| ARKW · ARK ETF Trust | 1.15% | 93,876 NS | July 31, 2026 | N-PORT |
| VCR · VANGUARD WORLD FUND | 1.08% | 401,841 SH | Aug. 19, 2026 | Daily |
| IMCG · iShares Trust | 1.05% | 208,592 SH | Sept. 11, 2026 | Daily |
| WANT · Direxion Shares ETF Trust | 1.04% | 1,078 NS | July 31, 2026 | N-PORT |
| ALTL · Pacer Funds Trust | 0.94% | 4,401 NS | July 31, 2026 | N-PORT |
| GARP · iShares Trust | 0.89% | 134,731 SH | Sept. 11, 2026 | Daily |
| RPG · Invesco Exchange-Traded Fund Trust | 0.88% | 92,348 SH | Oct. 1, 2026 | Daily |
| TRFM · ETF Series Solutions | 0.87% | 10,984 NS | July 31, 2026 | N-PORT |
| VO · VANGUARD INDEX FUNDS | 0.66% | 8,022,824 SH | Aug. 19, 2026 | Daily |
| SPHB · Invesco Exchange-Traded Fund Trust … | 0.64% | 33,027 SH | Oct. 1, 2026 | Daily |
| HIBL · Direxion Shares ETF Trust | 0.64% | 2,432 NS | July 31, 2026 | N-PORT |
| IMCB · iShares Trust | 0.53% | 44,208 SH | Sept. 11, 2026 | Daily |
| PALC · Pacer Funds Trust | 0.53% | 5,637 NS | July 31, 2026 | N-PORT |
| HEQQ · J.P. Morgan Exchange-Traded Fund Tr… | 0.52% | 794 NS | July 31, 2026 | N-PORT |
| JHAI · Janus Detroit Street Trust | 0.52% | 620 NS | July 31, 2026 | N-PORT |
| WINN · Harbor ETF Trust | 0.48% | 27,907 NS | July 31, 2026 | N-PORT |
| ACVF · ETF Opportunities Trust | 0.46% | 3,561 NS | July 31, 2026 | N-PORT |
| XOEF · iShares Trust | 0.43% | 477 SH | Sept. 11, 2026 | Daily |
| FTC · First Trust Exchange-Traded AlphaDE… | 0.41% | 27,858 NS | July 31, 2026 | N-PORT |
| QYLD · Global X Funds | 0.38% | 155,480 NS | July 31, 2026 | N-PORT |
| IYW · iShares Trust | 0.37% | 464,177 SH | Sept. 11, 2026 | Daily |
| PTNQ · Pacer Funds Trust | 0.37% | 22,492 NS | July 31, 2026 | N-PORT |
| QYLG · Global X Funds | 0.37% | 2,958 NS | July 31, 2026 | N-PORT |
| QTR · Global X Funds | 0.37% | 142 NS | July 31, 2026 | N-PORT |
| QRMI · Global X Funds | 0.37% | 266 NS | July 31, 2026 | N-PORT |
| QQWZ · Pacer Funds Trust | 0.36% | 938 NS | July 31, 2026 | N-PORT |
| QCLR · Global X Funds | 0.36% | 61 NS | July 31, 2026 | N-PORT |
| FXL · First Trust Exchange-Traded AlphaDE… | 0.35% | 46,085 NS | July 31, 2026 | N-PORT |
| QSIX · Pacer Funds Trust | 0.34% | 318 NS | July 31, 2026 | N-PORT |
| JMOM · J.P. Morgan Exchange-Traded Fund Tr… | 0.33% | 42,003 NS | July 31, 2026 | N-PORT |
| QQQM · Invesco Exchange-Traded Fund Trust … | 0.31% | 1,880,647 SH | Oct. 1, 2026 | Daily |
| QQQ · Invesco QQQ Trust, Series 1 | 0.31% | 8,544,692 SH | Oct. 1, 2026 | Daily |
| FBCG · FIDELITY COVINGTON TRUST | 0.31% | 110,030 NS | July 31, 2026 | N-PORT |
| JVAL · J.P. Morgan Exchange-Traded Fund Tr… | 0.31% | 13,177 NS | July 31, 2026 | N-PORT |
| IWY · iShares Trust | 0.27% | 205,882 SH | Sept. 11, 2026 | Daily |
| SIZE · iShares Trust | 0.24% | 5,101 SH | Sept. 11, 2026 | Daily |
| ILCG · iShares Trust | 0.24% | 36,720 SH | Sept. 11, 2026 | Daily |
| HELO · J.P. Morgan Exchange-Traded Fund Tr… | 0.23% | 54,514 NS | July 31, 2026 | N-PORT |
| USMV · iShares Trust | 0.23% | 272,485 SH | Sept. 11, 2026 | Daily |
| IWF · iShares Trust | 0.23% | 1,408,528 SH | Sept. 11, 2026 | Daily |
| VEGN · ETF Series Solutions | 0.23% | 2,040 NS | July 31, 2026 | N-PORT |
| IVW · iShares Trust | 0.21% | 807,070 SH | Sept. 11, 2026 | Daily |
| VUG · VANGUARD INDEX FUNDS | 0.21% | 4,247,615 SH | Aug. 19, 2026 | Daily |
| FAD · First Trust Exchange-Traded AlphaDE… | 0.21% | 6,054 NS | July 31, 2026 | N-PORT |
| IUSG · iShares Trust | 0.20% | 333,160 SH | Sept. 11, 2026 | Daily |
| WRND · New York Life Investments ETF Trust | 0.20% | 107 NS | July 31, 2026 | N-PORT |
| VOOG · VANGUARD ADMIRAL FUNDS | 0.20% | 281,083 SH | Aug. 19, 2026 | Daily |
| VONG · VANGUARD SCOTTSDALE FUNDS | 0.20% | 593,594 SH | Aug. 19, 2026 | Daily |
| DFUV · Dimensional ETF Trust | 0.19% | 152,231 NS | July 31, 2026 | N-PORT |
| RSP · Invesco Exchange-Traded Fund Trust | 0.19% | 991,668 SH | Oct. 1, 2026 | Daily |
| EUSA · iShares, Inc. | 0.19% | 17,720 SH | Sept. 11, 2026 | Daily |
| GLBL · Pacer Funds Trust | 0.18% | 10 NS | July 31, 2026 | N-PORT |
| EGLE · Global X Funds | 0.17% | 19 NS | July 31, 2026 | N-PORT |
| LGDX · Tidal Trust III | 0.17% | 1,199 NS | July 31, 2026 | N-PORT |
| TOPC · iShares Trust | 0.14% | 230 SH | Sept. 11, 2026 | Daily |
| IWL · iShares Trust | 0.13% | 14,588 SH | Sept. 11, 2026 | Daily |
| XVV · iShares Trust | 0.13% | 4,343 SH | Sept. 11, 2026 | Daily |
| VOXP · Advisors Series Trust | 0.12% | 36 NS | July 31, 2026 | N-PORT |
| ESGV · VANGUARD WORLD FUND | 0.12% | 84,740 SH | Aug. 19, 2026 | Daily |
| IETC · iShares U.S. ETF Trust | 0.12% | 4,095 SH | Sept. 11, 2026 | Daily |
| XTR · Global X Funds | 0.12% | 29 NS | July 31, 2026 | N-PORT |
| XYLG · Global X Funds | 0.12% | 384 NS | July 31, 2026 | N-PORT |
| XYLD · Global X Funds | 0.12% | 19,383 NS | July 31, 2026 | N-PORT |
| IVV · iShares Trust | 0.12% | 4,769,872 SH | Sept. 11, 2026 | Daily |
| CATH · Global X Funds | 0.12% | 7,714 NS | July 31, 2026 | N-PORT |
| XCLR · Global X Funds | 0.12% | 21 NS | July 31, 2026 | N-PORT |
| CHRI · Global X Funds | 0.12% | 47 NS | July 31, 2026 | N-PORT |
| BBUS · J.P. Morgan Exchange-Traded Fund Tr… | 0.11% | 51,958 NS | July 31, 2026 | N-PORT |
| DFSU · Dimensional ETF Trust | 0.11% | 13,242 NS | July 31, 2026 | N-PORT |
| VOTE · TCW ETF Trust | 0.11% | 6,375 NS | July 31, 2026 | N-PORT |
| ILCB · iShares Trust | 0.11% | 7,302 SH | Sept. 11, 2026 | Daily |
| PTLC · Pacer Funds Trust | 0.11% | 18,932 NS | July 31, 2026 | N-PORT |
| XRMI · Global X Funds | 0.11% | 287 NS | July 31, 2026 | N-PORT |
| VOO · VANGUARD INDEX FUNDS | 0.11% | 9,832,428 SH | Aug. 19, 2026 | Daily |
| VV · VANGUARD INDEX FUNDS | 0.11% | 432,357 SH | Aug. 19, 2026 | Daily |
| IYY · iShares Trust | 0.11% | 16,197 SH | Sept. 11, 2026 | Daily |
| IWB · iShares Trust | 0.11% | 259,843 SH | Sept. 11, 2026 | Daily |
| BKLC · BNY Mellon ETF Trust | 0.11% | 29,973 NS | July 31, 2026 | N-PORT |
| PBP · Invesco Exchange-Traded Fund Trust | 0.11% | 2,243 SH | Oct. 1, 2026 | Daily |
| SPUU · Direxion Shares ETF Trust | 0.11% | 1,427 NS | July 31, 2026 | N-PORT |
| DFUS · Dimensional ETF Trust | 0.11% | 111,972 NS | July 31, 2026 | N-PORT |
| QDPL · Pacer Funds Trust | 0.10% | 9,111 NS | July 31, 2026 | N-PORT |
| ITOT · iShares Trust | 0.10% | 492,153 SH | Sept. 11, 2026 | Daily |
| PBUS · Invesco Exchange-Traded Fund Trust … | 0.10% | 63,915 SH | Oct. 1, 2026 | Daily |
| IWV · iShares Trust | 0.10% | 102,961 SH | Sept. 11, 2026 | Daily |
| VONE · VANGUARD SCOTTSDALE FUNDS | 0.10% | 62,097 SH | Aug. 19, 2026 | Daily |
| VTHR · VANGUARD SCOTTSDALE FUNDS | 0.10% | 31,561 SH | Aug. 19, 2026 | Daily |
| TOV · EA Series Trust | 0.10% | 1,380 NS | July 31, 2026 | N-PORT |
| FEX · First Trust Exchange-Traded AlphaDE… | 0.10% | 7,636 NS | July 31, 2026 | N-PORT |
| DFAU · Dimensional ETF Trust | 0.09% | 58,531 NS | July 31, 2026 | N-PORT |
| HCMT · Direxion Shares ETF Trust | 0.09% | 2,631 NS | July 31, 2026 | N-PORT |
| VTI · VANGUARD INDEX FUNDS | 0.09% | 11,755,244 SH | Aug. 19, 2026 | Daily |
| TOK · iShares Trust | 0.09% | 1,052 SH | Sept. 11, 2026 | Daily |
| PHDG · Invesco Actively Managed Exchange-T… | 0.09% | 296 SH | Oct. 1, 2026 | Daily |
| SPXL · Direxion Shares ETF Trust | 0.09% | 29,590 NS | July 31, 2026 | N-PORT |
| HDUS · Lattice Strategies Trust | 0.09% | 883 NS | July 31, 2026 | N-PORT |
| CRBN · iShares Trust | 0.08% | 4,849 SH | Sept. 11, 2026 | Daily |
| ESMV · iShares Trust | 0.08% | 32 SH | Sept. 11, 2026 | Daily |
| URTH · iShares, Inc. | 0.08% | 33,008 SH | Sept. 11, 2026 | Daily |
| RWL · Invesco Exchange-Traded Fund Trust … | 0.08% | 40,202 SH | Oct. 1, 2026 | Daily |
| ACWI · iShares Trust | 0.07% | 118,219 SH | Sept. 11, 2026 | Daily |
| TILT · FlexShares Trust | 0.07% | 7,900 NS | July 31, 2026 | N-PORT |
| IUS · Invesco Exchange-Traded Self-Indexe… | 0.07% | 3,534 SH | Oct. 1, 2026 | Daily |
| DFAC · Dimensional ETF Trust | 0.07% | 159,811 NS | July 31, 2026 | N-PORT |
| DCOR · Dimensional ETF Trust | 0.06% | 10,905 NS | July 31, 2026 | N-PORT |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0.06% | 312,434 SH | Aug. 19, 2026 | Daily |
| EQAL · Invesco Exchange-Traded Fund Trust … | 0.06% | 2,511 SH | Oct. 1, 2026 | Daily |
| PEVC · Pacer Funds Trust | 0.06% | 7 NS | July 31, 2026 | N-PORT |
| LRGF · iShares Trust | 0.05% | 9,295 SH | Sept. 11, 2026 | Daily |
| PRF · Invesco Exchange-Traded Fund Trust | 0.03% | 16,656 SH | Oct. 1, 2026 | Daily |
| DFLV · Dimensional ETF Trust | 0.00% | 218 NS | July 31, 2026 | N-PORT |
| LSEQ · Harbor ETF Trust | -2.19% | -1,712 NS | July 31, 2026 | N-PORT |
DASH Analyst Consensus Bullish and bearish analyst opinions, 12-month price target, upside
12-Month Price Target
43 analysts · 2026-10-02Mean target $256.26 +35.5%
Peer comparison (GICS sub-industry) Key metrics vs sector peers
FY basis, prices as of each company's last fiscal year-end close.
| Ticker | Market Cap | P/E | Rev YoY | Net Margin | ROE | Gross Margin |
|---|---|---|---|---|---|---|
| DASH | · | 106.3 | 27.9% | 6.8% | · | · |
| MCD | · | 25.6 | 3.7% | 31.9% | -376.3% | · |
| SBUX | $94.81B | 51.2 | 2.8% | 5.0% | -23.9% | · |
| YUM | · | 27.3 | 8.8% | 19.0% | -20.8% | · |
| CMG | · | 32.5 | 5.4% | 12.9% | 48.3% | · |
| QSR | $23.63B | 29.0 | 12.2% | 11.4% | 31.9% | · |
| DRI | $23.27B | 19.6 | 9.4% | 9.1% | 56.3% | 20.3% |
| ARMK | $10.25B | 32.0 | 6.3% | 1.8% | 10.6% | · |
| TXRH | $11.03B | 27.4 | 9.4% | 7.0% | 29.4% | · |
| DPZ | $14.31B | 24.2 | 5.0% | 12.2% | -15.3% | 40.0% |
| EAT | $7.17B | 15.6 | 7.9% | 8.4% | 118.3% | · |
Latest News Recent headlines mentioning this company
DASH AI Analyst Panel — Bullish and Bearish Views 2026Q2 debate: Claude, Grok, Gemini, ChatGPT on the stock's prospects
DoorDash is currently a battleground stock caught between its potential as a logistics powerhouse and the reality of its expensive valuation. Gemini and Claude argued that the 113 P/E ratio is unsustainable given thin net margins, while Grok countered that institutional volume and scale justify the premium. The panel remains split on whether the company's expansion into grocery can finally unlock the efficiency needed to support its current price, with most analysts maintaining a hold rating.
Round 1 — Opening Takes
I see DoorDash building a durable moat in food delivery through network effects that lock in users and restaurants for accelerating profits. Gross margins hold steady at 50.49%, proving they capture half of every order dollar despite heavy competition—a sign of real pricing power. EPS has climbed to $1.93, reflecting scalable profitability as order volumes grow. With a current ratio of 2.04, they have ample liquidity to invest in expansion without dilution risks. If grocery and international bets pay off, this compounds into a cash machine by 2026Q2.
My read is DoorDash trades at a premium that assumes flawless execution, but slowing growth could crush returns given the lofty multiples. P/E sits at 113—far above peers like MCD at 25.5—meaning the market prices in years of hypergrowth that delivery saturation threatens to derail. ROE is just 9.97%, lagging peers like CMG's 47%, signaling inefficient capital use despite profits. Debt/equity at 28.67 is low but irrelevant if margins slip under competitive pressure from Uber Eats.
DoorDash has built a defensible logistics network that is finally converting scale into real profit. EPS is up to $1.93 trailing, and the company is turning 10% of shareholder equity into earnings — modest by tech standards, but real and growing. The stock has rallied 35% from May lows to $240, and gross margins hold steady at 50%, which means unit economics are holding even as competition intensifies. If management can push net margins from 6.8% toward 10% over the next two years through operational leverage, the current valuation starts to look reasonable for a duopoly player in a $200B+ TAM.
DoorDash trades at 113 times trailing earnings — roughly 4x what McDonald's commands and 2x what Chipotle pays. That P/E is not justified by the fundamentals. ROE sits at 10%, a fraction of what peers like Starbucks (116%) and Yum (118%) generate, which tells you DoorDash is trapped in a lower-return business model despite its scale. The stock has already priced in perfection: margins are flat, growth is decelerating, and the company is burning capital on driver incentives just to hold market share. At $240, you're paying for a logistics commodity, not a compounder.
DoorDash is effectively cementing itself as the essential utility layer for local commerce, moving well beyond just restaurant delivery. The company maintains a gross margin of 50.49%. This indicates that for every dollar of revenue, over half remains after direct costs, proving their platform has significant scale and operational efficiency. Furthermore, their current ratio sits at 2.04. This means the company has more than two dollars in liquid assets for every dollar of short-term debt, giving them the financial runway to continue aggressive expansion into grocery and retail categories without needing to raise expensive capital.
The valuation gap between DoorDash and its restaurant peers is simply too wide to justify given the current profitability profile. The stock trades at a P/E ratio of 113.11. This means investors are paying a massive premium for earnings growth that is significantly more expensive than established fast-food giants like McDonald's. Additionally, the return on equity is only 9.97%. This suggests the company is not yet generating efficient returns on the capital shareholders have provided, making the current triple-digit earnings multiple look like a speculative bet rather than a value-based investment for 2026.
I think DoorDash's strongest bullish case is that the platform economics are durable and the growth runway remains intact, supported by a conservative balance sheet and improving profitability signals. EPS TTM is 1.93 per share. That means the company is already delivering positive earnings, giving it flexibility to invest in growth without needing new equity. Gross margin is 50.49%. That level shows the core marketplace delivers solid gross profit on revenue, which, with scale, can support higher operating margins. Debt/Equity is 28.67. That modest leverage gives the balance sheet room to fund expansion or weather a downturn.
I think the bear case is that DoorDash trades at a sky-high multiple for growth with limited near-term margin expansion, and that competitive or regulatory headwinds could derail the rally. P/E TTM is 113.11. That is extreme vs peers, implying the stock is pricing in very high growth and a miss could compress multiples. P/S TTM is 7.73. That premium to sales signals investors are paying for growth rather than current profitability. ROE TTM is 9.97%. That ROE is modest versus peers with much higher returns on equity, suggesting limited efficiency and that upside hinges on top-line growth rather than returns on capital.
Round 2 — Responses & Rebuttals
Round 2 — Responses & Rebuttals
Claude, your bear case that the 35% rally prices in perfection ignores how multiples are compressing with profit growth. P/E has dropped from 133 last quarter to 113 now as EPS rose to $1.93 from $1.76. That means the market is giving credit for actual execution on scale, not just hoping for margin miracles—making the valuation more defensible heading into 2026Q2.
I think Grok is conflating two different things here. Yes, gross margin at 50.49% is solid, but that's not the same as pricing power — it's the margin after paying restaurants and platform costs, not after paying drivers. The real test of pricing power is net margin, which sits at 6.83% and hasn't budged in two quarters. That tells me DoorDash is locked in a race where every efficiency gain gets competed away or spent on driver incentives to hold share. Grok's point about grocery and international upside is fair, but those are unproven bets. The core business isn't generating the returns that justify a 113 P/E.
Claude, your focus on the 10% ROE misses the reality that DoorDash is still in a heavy investment phase for its non-restaurant verticals. That 9.97% ROE represents the return on capital while the company is aggressively subsidizing its entry into grocery and retail logistics. If they were to pivot to pure harvest mode, that number would climb significantly, but you are right that the current valuation assumes that transition is already complete. We are paying for the future potential of a logistics network, not the current efficiency of a mature restaurant chain.
Claude, your margin-expansion thesis hinges on near-term improvements that may not materialize given intense driver incentives and the risk of margin pressure from competition. P/E 113 signals the market is already pricing in years of outsized growth independent of near-term results. That premium means any deceleration in growth or a stall in unit economics could trigger a sharp multiple compression, complicating the outlook even if earnings stay positive.
Round 3 — Final Rebuttals
Round 3 — Final Rebuttals
Claude, your bear case overlooks the technical conviction driving this rally into 2026Q2. DoorDash surged 35% from May lows. That gain came on conviction buying, with volume spiking to 24 million shares on the June 27th close at $242. Institutions are positioning heavily here, not just hoping for margins—this flow makes the 113 P/E more resilient than static ratios suggest.
I want to push back on Grok's math here, and I think it matters for how we frame the risk. Grok says P/E compressed from 133 to 113 as EPS grew from $1.76 to $1.93—implying the market is rewarding execution. But that's not quite right. Market cap actually fell from $104B to $97.6B over the same window, even though earnings rose. That means multiples didn't compress because of profit growth; they compressed because the stock sold off harder than earnings improved. The rally from May lows is real, but we're still down 6% from three quarters ago on a per-share earnings basis. That's not a vote of confidence in the business model—it's a repricing of risk. I'm holding my hold, but the narrative that execution is being rewarded doesn't match the actual capital flows.
I want to challenge Grok’s assertion that the P/E compression from 133 to 113 validates the stock price. This ignores the macro regime shift, specifically the cooling of the delivery sector's growth as consumer discretionary spending tightens under sustained high interest rates. A P/E of 113.11 means the market is still pricing in a growth trajectory that assumes consumers will keep paying premium delivery fees indefinitely. If the current rate environment forces households to trade down to cheaper dining alternatives, that 113 multiple will face severe compression regardless of DoorDash’s internal execution or recent EPS gains.
I think we should widen the frame to regulatory risk around gig-worker classification as a potential swing factor for 2026Q2. Net margin is 6.83%. That relatively thin margin means any reclassification to higher driver costs could shave profits further. Claude, your margin-expansion bet assumes labor costs stay tame; regulatory changes could derail that. Keep an eye on Prop 22 in California and potential spillovers as states rethink gig-work rules.
Price Forecasts
| Model | 3M Target | 6M Target | Reasoning |
|---|---|---|---|
| Grok | $255.00 | $275.00 | I think DoorDash trades fairly around current levels with modest upside as scale drives EPS higher, compressing the extreme P/E toward peer realities by 2026Q2. The key catalyst is the Q2 2026 earnings release in early August, where guidance for 15%+ order growth in grocery could validate the logistics pivot and spark fresh buying. The big risk is California Prop 22 challenges escalating nationally, hiking driver costs and squeezing 6.83% net margins. At a $275 6-month target, P/E falls to about 90—that still prices aggressive growth but aligns better with CMG's 29, rewarding execution without perfection. |
| Claude | $215.00 | $198.00 | DoorDash is a high-multiple compounder priced for flawless execution in a margin-trapped business—and the math doesn't support the premium. My thesis: the 113 P/E is unjustifiable because net margin sits at 6.83% and hasn't moved in two quarters, meaning scale isn't translating to profitability. Concrete catalyst: Q2 2026 earnings guidance. If management signals net margin expansion to 8%+ and sustains it through Q3, I'd revise higher; if they hold flat or guide down, multiples compress hard. Concrete risk: regulatory reclassification of drivers in California or federally, which would shred that 6.83% margin instantly. At 113 times earnings, DoorDash trades at 4.4x McDonald's multiple despite 1/10th the ROE—that gap closes when growth slows or labor costs spike. |
| Gemini | $215.00 | $235.00 | My thesis is that DoorDash will trade higher as it proves its utility as a logistics backbone, though the path will be volatile due to high valuation. A key catalyst for the 6-month target is the Q4 earnings report, where sustained growth in non-restaurant categories could finally convince the market to stop treating this as a simple delivery app. The primary risk is a broad regulatory crackdown on gig-worker classification, which would instantly destroy their unit economics. The current P/E of 113.11 means investors are paying for years of future growth, so any sign of slowing order volume will lead to immediate and painful share price compression. |
| Chatgpt | $200.00 | $210.00 | I think DoorDash can grind higher as its non-restaurant verticals start contributing meaningfully to profits without wrecking gross margins. Catalyst: the Q2 2026 earnings print, where management guides to expanded grocery/retail mix and improving unit economics, would push the stock toward the 200 area. Risk: a regulatory setback on gig-worker classification or a spike in driver costs could compress margins and derail the rally. From current price 187.76, a move to about 200 would imply a modest valuation uplift, with 210 serving as a longer-horizon check on growth confidence. |
Trading Signals Recent buy/sell signals with entry price and risk/reward ratio
No open signal right now — no card is filled, and that's honest.
My Metrics Your personal watchlist — selected rows from Full Fundamentals
Pick the metrics that matter to you — click the + next to any row in Full Fundamentals above.
Your selection is saved and follows you across all tickers.