RY Royal Bank Of Canada Common Stock
NYSE · Banking · View on SEC EDGAR ↗ close Oct 2, 2026 10-K/10-Q Dec 3, 2025RY Stock Snapshot Price, market cap, P/E, EPS, ROE, debt/equity, 52-week range
RY Stock Price Chart Daily OHLCV with technical indicators — pan, zoom, and customize your view
Bar granularity adapts to the selected period — hover the chart to see open/high/low/close for a bar.
| Ex-date | Split | Type |
|---|---|---|
| April 7, 2006 | 2-for-1 | Forward |
| Oct. 6, 2000 | 2-for-1 | Forward |
About Royal Bank Of Canada Common Stock Company overview from Wikipedia
The Royal Bank of Canada (RBC; French: Banque Royale du Canada) is a Canadian multinational financial services company and the largest bank in Canada by market capitalization. The bank serves over 19 million clients and has more than 101,000 employees worldwide. Founded in 1864 in Halifax, Nova Scotia, it maintains its corporate headquarters in Toronto and its head office in Montreal. RBC's institution number is 003. In November 2017, RBC was added to the Financial Stability Board's list of global systemically important banks.
In Canada, the bank's personal and commercial banking operations are branded as RBC Royal Bank in English and RBC Banque Royale in French and serves approximately 11 million clients through its network of 1,263 branches. RBC Bank is a US banking subsidiary which formerly operated 439 branches across six states in the Southeastern United States, but now only offers cross-border banking services to Canadian travellers and expats. RBC's other Los Angeles-based US subsidiary City National Bank operates 79 branches across 11 US states. RBC also has 127 branches across seventeen countries in the Caribbean, which serve more than 16 million clients. RBC Capital Markets is RBC's worldwide investment and corporate banking subsidiary, while the investment brokerage firm is known as RBC Dominion Securities. Investment banking services are also provided through RBC Bank and the focus is on middle market clients. The company expanded further in 2024 when RBC acquired HSBC's Canadian operations.
In 2011, RBC was the largest Canadian company by revenue and market capitalization. In 2023, the company was ranked 38th in the Forbes Global 2000. The company has operations in Canada and 28 other countries, and had CA$1.574 trillion of assets under management in 2025.
History
In 1864, the Merchants Bank of Halifax was founded in Halifax, Nova Scotia, as a commercial bank that financed the fishing and timber industries and the European and Caribbean import/export businesses. By 1869 the Merchants' Bank was officially incorporated and received its federal charter in the same year. During the 1870s and 1880s, the bank expanded into the other Maritime Provinces. When both the Newfoundland Commercial Bank and Union Bank of Newfoundland collapsed on December 10, 1894, the Merchants Bank expanded to Newfoundland on January 31, 1895.
As the bank grew, executives changed its name to reflect its growth and western expansion. In 1901, the Merchants Bank of Halifax changed its name to the Royal Bank of Canada (RBC). As Canada’s financial activity became increasingly concentrated in Montreal, RBC moved its head office from Halifax to Montreal in 1907. In 1910, RBC merged with the Union Bank of Halifax. In the same year it built a bank branch in Winnipeg, Manitoba, designed by Carrère and Hastings, in beaux-arts classicism proclaiming the financial dominance of Winnipeg in the prairies. To improve its position in Ontario, RBC merged with Traders Bank of Canada in 1912 and in 1917 RBC merged with Quebec Bank, which was founded in 1818 and chartered in 1822 in Quebec City.
RBC's presence in Manitoba and Saskatchewan was strengthened through a 1918 merger with Northern Crown Bank, the product of the 1908 merger of Northern Bank (established in 1905 in Winnipeg) and Crown Bank of Canada (1904), based in Ontario. RBC's presence in the Canadian Prairie was further expanded by the 1925 merger with the Union Bank of Canada, which had begun in Quebec City in 1865 as the Union Bank of Lower Canada, but changed its name in 1886. The Union Bank of Canada had moved its headquarters to Winnipeg in 1912, and had built a strong presence in the Prairies and opened the first bank in the Northwest Territories at Fort Smith in 1921.
In 1935, RBC merged with Crown Savings and Loan Co. merged with Industrial Mortgage & Trust Co.
RoyWest Banking Corporation was formed in Nassau, Bahamas in 1965, to undertake medium-term lending and trustee business in the British West Indies. Majority owned by seven firms, including RBC and Westminster Bank, sole ownership transferred to National Westminster Bank in 1987.
RBC installed its first computer in 1961, the IBM 1401, the first to do so in Canadian banking. In the 1960s, RBC Insurance was created. In 1968, it merged with Ontario Loan and Debenture Company (formerly Ontario Savings and Investment Society). RBC Insurance is the largest Canadian bank-owned insurance organization, with services to over five million people. It provides life, health, travel, home and auto and reinsurance products as well as creditor and business insurance services. The completion of Royal Bank Plaza in Toronto in 1976 saw the relocation of many critical head-office functions from Montreal, with Toronto serving as RBC's corporate headquarters ever since. In 1993, RBC merged with Royal Trust.
In 1998, RBC acquired Security First Network Bank in Atlanta—the first pure Internet bank. In the same year, the Royal Bank of Canada proposed to merge with the Bank of Montreal, at the same time as the Toronto-Dominion Bank proposed to merge with the Canadian Imperial Bank of Commerce. Both mergers were examined by the Competition Bureau of Canada, and ultimately rejected by Paul Martin, at the time the Finance Minister of Canada, and future Prime Minister.
In 2000, RBC merged merchant credit/debit card acquiring business with the Bank of Montreal's to form Moneris Solutions. In 2013, RBC completed the acquisition of the Canadian subsidiary of Ally Financial.
An RBC branch in The Glebe neighbourhood of Ottawa was firebombed in May 2010. The party responsible later identified themselves on Independent Media Center and threatened to make their presence at the upcoming 2010 G20 Toronto summit.
In November 2022, RBC and HSBC Canada announced a deal which would see RBC acquiring 100% of the common shares of HSBC Canada for an all-cash purchase price of $13.5 billion, a multiple of 9.4 times HSBC Canada's estimated 2024 earnings. Completion of the transaction is expected by late 2023, subject to regulatory approvals. In December 2023, RBC received approval from Finance Minister Chrystia Freeland to take over HSBC Bank in a deal. Conditions for the deal include that none of HSBC Canada's 4,000 employees will be laid off within six months of the closing date or two years for direct staff, and banking services will be provided at 33 HSBC branches for at least another four years. RBC will also provide $7 billion in financing for affordable housing developments in Canada.
International expansion
1882: Merchants Bank of Halifax opened offices in Bermuda and Newfoundland.
1899: RBC opened an agency in New York City and a branch in Havana.
1903: RBC bought Banco de Oriente de Santiago de Cuba. By the mid-1920s, RBC had 65 branches in Cuba and is the largest bank in the country.
1904: RBC bought Banco del Commercio de Havana.
1907: RBC opened a branch in San Juan, Puerto Rico; branches in Mayagüez and Ponce followed.
1909: RBC established a branch in Nassau, Bahamas.
1910: RBC opened a branch in London and acquired branches in Puerto Rico and Port of Spain, Trinidad as a result of its acquisition of Union Bank of Halifax.
1911: RBC opened an agency in New York City, and branches in Bridgetown, Barbados, and Kingston, Jamaica.
1912: RBC bought Bank of British Honduras (incorporated in 1902 by United States citizens from Mobile) in British Honduras, which it converted to a branch.
RBC opened a branch in the Dominican Republic; three more follow.
1913: RBC opened a branch in Grenada.
1914: RBC bought out Bank of British Guiana (est. 1836), in British Guiana, and converted it to a branch.
1915: RBC opened branches in Costa Rica, Antigua, Dominica, and Saint Kitts.
1916: RBC opened a branch in Venezuela.
1917: RBC opened branches in Antigua, Dominica, St. Kitts, Montserrat, Nevis, and Tobago.
1918: RBC opened a branch in Barcelona, and another in Vladivostok that lasted less than a year.
1919: RBC opened branches in Brazil, Argentina, Uruguay, Paris, Martinique, Guadeloupe, and Port-au-Prince, Haiti.
1920: RBC opened a branch in Colombia and a branch in Castries, St Lucia.
1923: RBC bought and consolidated the banking operations of Pedro Gomez Mena e Hijo in Cuba.
1925: RBC opened a branch in Peru, and acquired the American-owned, and failed, Bank of Central and South America. The purchase of BCSA brought with it subsidiaries, and their branches, in Colombia, Costa Rica, Peru, and Venezuela
1932: RBC closed its branch in St. Lucia.
1940: RBC closed its branches in Martinique and Guadeloupe.
1958: A representative office opened in Hong Kong, which became a branch in 1978.
1959: RBC opened a branch in St. Vincent.
1960: RBC returned to St. Lucia.
1960: Fidel Castro's regime acquired RBC's operations in Cuba on December 8. At the time of the forced sale, RBC had 24 branches in Cuba. From 1961 to 1965, RBC maintained a Special Representative in Havana to facilitate trade between Cuba and Canada. After the failed Bay of Pigs Invasion in April 1961, the Special Representative acted as a financial intermediary between the American and Cuban governments to manage the ransoming of the prisoners for food and agricultural machinery.
1964: RBC opened a branch in George Town, Cayman Islands.
1970s: As a result of Law 75, RBC's operations in Colombia became Banco Royal Colombiano.
1973: RBC was forced to incorporate its operations in Jamaica, which became Royal Bank (Jamaica).
1980: RBC purchased Banco de San Juan in Puerto Rico, adding its 14 branches to the six that RBC already had in Puerto Rico. RBC sold its assets in Grenada to Republic Bank of Trinidad and Tobago.
1985: RBC started to withdraw from much of the Caribbean.
It sold its 12 branches in the Dominican Republic to Banco de Comercio Dominicano.
It also sold its stake in Royal Bank (Jamaica) to Jamaica Mutual Life Assurance. Branches in Curaçao, Aruba, St. Maarten and Dominica are still open (1985–present)
The Government of Guyana nationalized its operations there and renamed the bank the National Bank of Industry and Commerce Ltd.
Additionally, RBC incorporated its operations in Trinidad and Tobago locally, floating the shares, thereby divesting itself of ownership. The new bank took the name Royal Bank of Trinidad and Tobago (RBTT).
1986: National Mutual Royal Bank opened in Australia with RBC having a 50% shareholding
1986: RBC sold its two branches in Haiti to Societe Generale Haitienne de Banque, a local bank.
1987: RBC sold its operations in Belize, ex-British Honduras, to Belize Holdings Inc., which renamed them Belize Bank.
1990: National Mutual Royal Bank in Australia sold to the Australia and New Zealand Banking Group
1993: RBC sold Royal Bank of Puerto Rico to Spain's Banco Bilbao-Vizcaya.
1995: RBC sold Royal Trust Bank (Austria) to Anglo Irish Bank, which renamed it Anglo Irish Bank (Austria).
2000: Acquired Dain Rauscher Wessels, a US brokerage and investment banking firm based in Minneapolis, Minnesota
2001: RBC acquired Centura Bank based in Rocky Mount, North Carolina.
2001: RBC bought the investment banking and brokerage firm Tucker Anthony Sutro (Boston) from John Hancock Mutual Life Insurance Co.
2003: RBC purchased Florida interest in Provident Financial Group, Cincinnati OH.
2003: Hong Kong branch started operating as a licensed bank.
2006: RBC upgraded its representative office in Beijing, China, to a branch.
2006: Created an institutional investment joint venture with Dexia. The 50/50 partnership operated under the name RBC Dexia Investor Services.
2007: RBC acquires Carlin Financial.
2008: RBC established a representative office in Mumbai, India. RBC re-acquired 98.14% of the shares of Royal Bank of Trinidad and Tobago. This brought RBC back to Trinidad and Tobago 20 years after it had withdrawn and provided it with a presence in other islands served by RBTT.
2011: RBC sold RBC Bank to PNC Financial Services for US$3.62 billion. PNC ATMs are now used by customers with RBC Bank (Georgia), N.A. providing Canadians with bank options when they are residing in the US.
2012: RBC completed the acquisition of Dexia's 50% stake in RBC Dexia Investor Services Limited, making it the sole owner of the newly named [RBC Investor & Treasury Services]. RBC also opened a Branch in Wilemstad, Curaçao.
2014: RBC "entered into a merger agreement to acquire City National Corporation", a major U. S. bank.
2015: RBC agreed to sell its Swiss private bank Royal Bank of Canada (Suisse) SA to local rival SYZ Group. Terms of the sale were not disclosed. Royal Bank of Canada (Suisse) manages CHF 10 billion (US$10.5 billion, C$13.4 billion) of assets for clients in Africa, the Middle East and South America.
2015: RBC completed the acquisition of City National Bank (November)
2016: On January 21, 2016, Aviva announced the acquisition of RBC General Insurance Company, for C$582 million.
2019: RBC agreed to sell its Eastern Caribbean banking operations, in places such as Antigua, Dominica, and Saint Lucia, to a consortium of banks in the region.
2022: RBC announced the acquisition of wealth manager Brewin Dolphin in the United Kingdom, in a deal which valued Brewin Dolphin at C$2.4bn (£1.6bn).
2024 RBC completed the acquisition of HSBC Canada, splitting some assets with the National Bank for competition issues.
Branding
Logo
The bank's first modern identity was designed by firm Lippincott & Margulies, and was introduced in January 1962. From this point forward the bank's logo has contained the same basic element of a stylized lion clutching a globe, becoming more simplified with each iteration. Alongside promotion of the Royal Bank Plaza, a tweaked version of the mark by Montreal design consultancy Gottschalk + Ash silently debuted in June 1979. The same basic form was retained, however many lines were thickened and details simplified to facilitate printing at small sizes. The total brand overhaul and shortening of the Royal Bank name to RBC in August 2001 coincided with their expansion into the United States market. The direction of the lion, now further simplified, was reversed, the crown above omitted, and both the symbol and wordmark were placed within a blue shield.
Sponsorship
RBC sponsors cultural events including the Toronto International Film Festival. It also sponsors the RBC Taylor Prize, a literary award for non-fiction writing in Canada, and hosts a yearly Canadian Women Entrepreneur Award. In July 2013, the RBC Foundation partnered with the University of Toronto to revive the Siminovitch Prize in Theatre, given to recognize achievement in Canadian theatre.
RBC is one of Canada's largest sponsors of amateur sports and is the longest-running Canadian sponsor of the Olympic Games. It employs dozens of top-tier amateur athletes as part-time spokespeople through the RBC Olympians program. RBC is a former premier sponsor of Hockey Canada and previously owned the naming rights to the National Junior A Championship, then called the Royal Bank Cup (later the RBC Cup). In addition, it supports Canadian hockey at the grassroots level through the RBC Play Hockey program.
RBC owns naming rights to the RBC Centre, RBC Convention Centre Winnipeg, RBC Canadian Open, and RBC Heritage (formerly the Heritage Classic). From 2002 to 2012, RBC previously held the naming rights to what is now the Lenovo Center in Raleigh, North Carolina.
RBC has owned naming rights for the Top 25 Canadian Immigrants Award, presented annually by Canadian Immigrant, since 2013.
RBC has also sponsored Major League Soccer in the United States since 2023. In 2025, RBC and its Los Angeles-based subsidiary City National Bank signed with the LA Galaxy to have its logo placed on the team's jersey sleeve and throughout the stadium.
Head offices
The head office for the institution was initially located at the Merchants' Bank of Halifax Building, on Bedford Row, Halifax, Nova Scotia. The building served as the head office for the bank from 1864 to 1907. In 1907, the RBC relocated its head office to the Four Pillars Building, at 147 Saint Jacques Street (renumbered 221 in 1928), Montreal. The building was used as RBC's head office until 1928. The Four Pillars Building was later demolished, with only its facade remaining. In 1928, RBC moved its head office to the Old Royal Bank Building, at 360 Saint Jacques Street, Montreal.
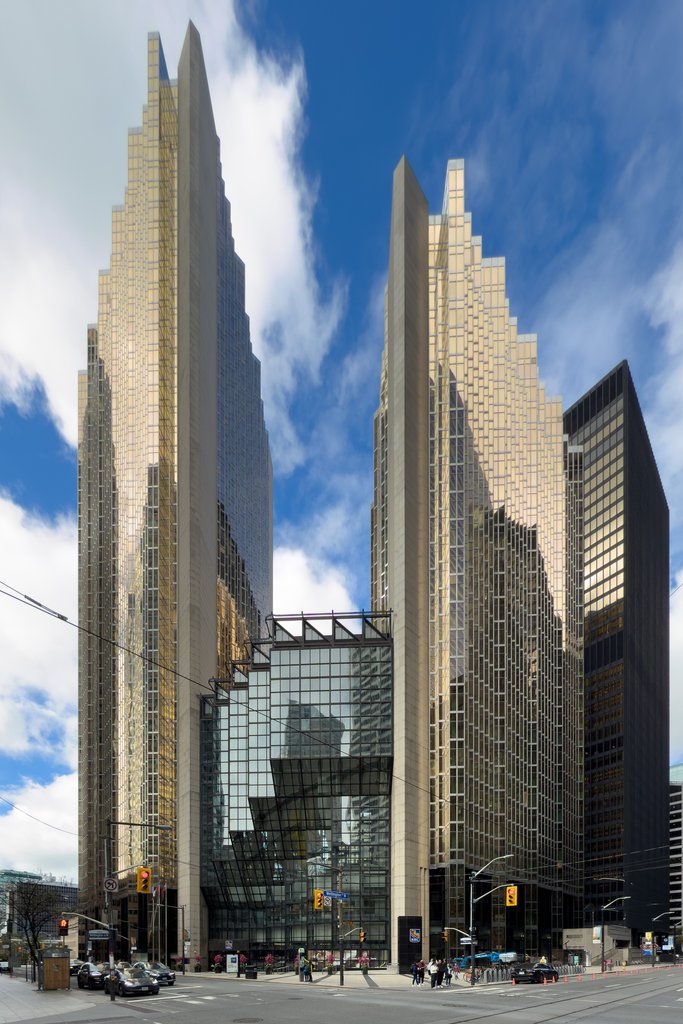
In 1962, RBC moved its head office to Place Ville-Marie, at University Street and René-Lévesque Boulevard in Montreal. In 1976, RBC moved its corporate headquarters to Royal Bank Plaza to 200 Bay Street in Toronto, although Place Ville-Marie remained its registered head office under the Bank Act. RBC makes the distinction that Royal Bank Plaza in Toronto is its corporate headquarters, while Place Ville-Marie in Montreal is its head office.
Controversies
Discrimination
On January 15, 2007, CBC Radio reported RBC was "refusing" to open US dollar accounts for people of certain nationalities. Canadian citizens with dual citizenship in Cuba, Iran, Iraq, Myanmar, North Korea or Sudan (mostly countries with US sanctions) were affected. The US Treasury Department restricts certain foreign nationals from using the US dollar payment system to limit terrorism and money laundering after the September 11, 2001, attacks. RBC replied that compliance with such laws does not represent an endorsement by the bank and on January 17, clarified its position on the application of the US laws, specifying that "with some exceptions" it does open accounts for dual citizens of the sanctioned countries. There have also been reports that the bank had closed the accounts of some Iranian-Canadian citizens.
Environment
According to a report by Rainforest Action Network, RBC's financing of oil sands bitumen extraction and expansion amounted to "more than $2.3 billion in loans and financing [of] more than $6.9 billion in [corporate] debt between 2003 and 2007 for 13 companies including: Encana, Husky Energy, OPTI Canada, Delphi Energy, Canadian Oil Sands Trust, Northwest Upgrading, Suncor, TotalEnergies, Connacher Oil and Gas, InterPipeline and Enbridge".
A 2020 report on fossil fuel finance by the Sierra Club and Rainforest Action Network found that RBC was the fifth largest funder of fossil fuels in the world, and largest in Canada, investing over US$160 billion on fossil fuel projects since the Paris Agreement in 2015. This sparked criticism from environmental groups and climate activists.
A more recent 2023 report from a coalition of environmental group places RBC as the largest financier of fossil fuel in the world in 2022, investing US$42 billion in fossil fuel projects in that year alone.
Funding of SCO litigation on Linux
RBC invested in SCO Group during the series of court cases seeking to collect royalties from the users of Linux.
Investor protection
In 2014, the Commodity Futures Trading Commission fined RBC $35,000,000 for engaging in more than 1,000 wash sales, fictitious sales, and other non-competitive practices over a three-year period.
Mismarking
In 2007, the Royal Bank of Canada fired several traders in its corporate bond business, after another trader accused them of mismarking bonds the bank held by overpricing them, and marked down the values of the bonds and recognized $13 million of trading losses relating to the bonds. The bank said it investigated the accusations, and took remedial action. The Globe and Mail noted: "traders might have an incentive to boost [the bonds'] prices because it could have an impact on their bonuses."
Temporary foreign workers and Canadian layoffs
In April 2013, the CBC reported that the Royal Bank of Canada was indirectly hiring temporary foreign workers to replace 45 Canadian information technology workers.
The CBC reported on May 7, 2013, that, during Question Period in Parliament, the NDP leveled accusations against the government and then Prime Minister Stephen Harper. Harper responded that the government has been working on problems with the Temporary Foreign Worker Program for more than a year.
Vacation pay class action lawsuit
On December 29, 2022, the Supreme Court of Ontario certified a class action lawsuit permitting employees of RBC Dominion Securities to seek $800 million in damages, over alleged unpaid wages for holidays and other vacation days.
Memberships
RBC is a member of the Canadian Bankers Association which includes Canada's Big Five banks, and is a registered member with the Canada Deposit Insurance Corporation, a federal agency insuring deposits at all of Canada's chartered banks.
It is also a member of:
Leadership
The office of chairman of the Board was created in October 1949 for outgoing president Sydney Dobson. Until 2001, the chairmanship was given to the current or former president. After John Cleghorn's retirement in 2001, the chairmanship was made a separate, non-executive position.
President
James W. Merkel, 1864–1869
Thomas Clifford Kinnear, 1869–1870
Thomas Edward Kenny, 1870–1908
Herbert Samuel Holt, 1908–1934
Morris Watson Wilson, 1934 – 13 May 1946
Sydney George Dobson, 4 June 1946 – 18 October 1949
James Muir, 18 October 1949 – 10 April 1960
Madison Melville Walter, 26 April 1960 – 9 December 1960
William Earle McLaughlin, 19 December 1960– 30 June 1977
Rowland Cardwell Frazee 1 July 1977 – 30 September 1980
Jock Kinghorn Finlayson, 1 October 1980 – 31 May 1983
Allan Richard Taylor, 1 June 1983 – 31 May 1986
John Edward Cleghorn, 1 June 1986 – 30 March 2001
Gordon Melbourne Nixon, 1 April 2001 – 31 July 2014
David Ian McKay 1 August 2014 –
Chairman of the Board
Sydney George Dobson, 18 October 1949 – 30 November 1954
James Muir, 1 December 1954 – 10 April 1960
Madison Melville Walter, 26 April 1960 – 9 December 1960
William Earle McLaughlin, 1962 – 30 September 1980
Rowland Cardwell Frazee, 1 October 1980 – 31 May 1986
Allan Richard Taylor, 1 June 1986 – 26 January 1995
John Edward Cleghorn, 26 January 1995 – 31 July 2001
Guy Saint-Pierre, 1 August 2001 – 27 February 2004
David Peter O'Brien, 27 February 2004 – 31 December 2013
Kathleen Patricia Taylor, 1 January 2014 – 5 April 2023
Jacynthe Côté, 5 April 2023 –
Awards
2025 - "Customer Service Excellence," "Recommended to Friends or Family (Net Promoter Score," "Financial Planning & Advice," "ATM Banking Excellence," "Online Banking Excellence," Ipsos 2025 Financial Service Excellence Awards
2025 - Ranked highest in customer satisfaction, J.D. Power 2025 Canada Retail Banking Advice Satisfaction Study
2025 - Canada's Best Investment Bank, Euromoney Awards for Excellence, 2025
2025 - North America's Best Bank for Research, Euromoney Awards for Excellence, 2025
2025 - "Most Valuable Canadian Brand 2025", Kantar BrandZ
2024 – RBC Dominion Securities, the highest-ranked bank-owned investment dealer in Canada, Investment Executive 2024 Brokerage Report Card
2024 – "Best Bank in Canada for Small and Medium-Sized Business," Global Finance
Operating Units
RBC has six divisions:
Personal Banking offers a range of banking and financial services to individuals and businesses across Canada, such as mortgages, loans, credit cards and bank and investment accounts.
Commercial Banking works with small to medium-sized businesses and large enterprises to deliver a variety of banking and commercial finance services, including bank accounts, loans, lines of credit and equipment financing. Its RBCx platform supports company founders and venture capital firms in the innovation economy with a wide range of financial services.
Wealth Management provides a variety of financial advisory services to its clients, including wealth, estate and retirement planning, business succession planning, private banking and philanthropic assistance. In September 2022, RBC acquired Brewin Dolphin, one of the U.K.'s largest wealth management firms.
Capital Markets is a global investment bank providing services in banking, finance, and capital markets to corporations, institutional investors, asset managers, and governments globally.
Insurance offers a range of personal and business-related insurance products, including health, home, auto, travel, wealth, and reinsurance advice and solutions. It also offers creditor and business insurance services to individual, business, and group clients.
Investor and Treasury Services (I&TS) provides custodial, advisory, financing, and other services to safeguard clients' assets, while also maximizing liquidity and managing risk. RBC Borealis, a division of I&TS, conducts finance-focused AI research and develops AI models for financial services.
Bank histories
McDowall, Duncan. Quick to the Frontier: Canada's Royal Bank. McClelland & Stewart, 1993.
Royal Bank of Canada. Fiftieth Anniversary of the Royal Bank of Canada: A Record of Its Progress during the Past Half Century. Royal Bank of Canada, 1920.
Source: Wikipedia, CC BY-SA 4.0 · View on Wikipedia ↗
10-Year Performance Revenue, net income, margins and EPS trends
Valuation P/E, P/S, P/B, EV/EBITDA ratios — is the stock expensive or cheap?
| Metric | 5Y trend | RY | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| P/E | 10.45Y avg ≈9.3 | ≈9.3 | · | · |
Peer median is calculated on a standardized basis per metric and may not always match the TTM/MRQ basis shown for this stock.
Profitability Gross, operating and net margins; ROE, ROA, ROIC
| Metric | 5Y trend | RY | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| EBITDA Margin | 4.6%5Y avg ≈5.0% | ≈5.0% | · | · | |
| Pretax Margin | 38.5%5Y avg ≈37.7% | ≈37.7% | · | · | |
| Net Profit Margin | 30.6%5Y avg ≈30.0% | ≈30.0% | · | · | |
| ROA | 0.91%5Y avg ≈0.86% | ≈0.86% | · | · | |
| ROE | 15.3%5Y avg ≈14.9% | ≈14.9% | · | · |
Financial Health Debt, liquidity, solvency — balance sheet strength
Not enough fundamentals data to compute this ratio group yet.
Growth Revenue, EPS and net income growth: YoY, 3Y CAGR, 5Y CAGR
Not enough fundamentals data to compute this ratio group yet.
Capital Efficiency Asset turnover, inventory turnover, receivables turnover
| Metric | 5Y trend | RY | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Asset Turnover | 0.05Y avg ≈0.0 | ≈0.0 | · | · | |
| Revenue / Employee | ≈$657.7K | · | · | · |
value · ≈ 5Y avg · industry median · verdict relative to median
Dividends Yield, payout ratio, dividend history, 5Y CAGR
| Ex-date | Amount | Currency | Yield |
|---|---|---|---|
| Jul 27, 2026 | $1.25 | USD | ≈1.2% |
| Apr 23, 2026 | $1.20 | USD | ≈1.3% |
| Jul 24, 2025 | $1.13 | USD | ≈3.2% |
| Apr 24, 2025 | $1.07 | USD | ≈3.5% |
| Jan 27, 2025 | $1.03 | USD | ≈3.3% |
| Oct 24, 2024 | $1.03 | USD | ≈3.3% |
| Jul 25, 2024 | $1.03 | USD | ≈3.7% |
| Apr 24, 2024 | $1.01 | USD | ≈4.2% |
| Jan 24, 2024 | $1.03 | USD | ≈4.1% |
| Oct 25, 2023 | $0.98 | USD | ≈5.0% |
| Jul 25, 2023 | $1.03 | USD | ≈4.0% |
| Apr 24, 2023 | $0.98 | USD | ≈3.9% |
| Jan 25, 2023 | $0.99 | USD | ≈3.9% |
| Oct 25, 2022 | $0.93 | USD | ≈4.2% |
| Jul 25, 2022 | $0.99 | USD | ≈3.9% |
| Apr 22, 2022 | $0.95 | USD | ≈3.5% |
| Jan 25, 2022 | $0.95 | USD | ≈3.2% |
| Oct 25, 2021 | $0.87 | USD | ≈3.2% |
| Jul 23, 2021 | $0.86 | USD | ≈3.4% |
| Apr 21, 2021 | $0.86 | USD | ≈3.6% |
Earnings History EPS actual vs estimate, surprise %, beat rate, next earnings date
| Period | Report | EPS Actual | EPS Est | Surprise |
|---|---|---|---|---|
| Sept. 30, 2026 | $4.28 | $4.20 | 1.9% | |
| June 30, 2026 | $3.90 | $3.90 | 0.04% | |
| March 31, 2026 | $4.08 | $3.96 | 3.0% | |
| Dec. 31, 2025 | $3.85 | $3.63 | 6.0% | |
| Sept. 30, 2025 | $3.84 | $3.42 | 12.3% | |
| June 30, 2025 | $3.12 | $3.28 | -4.9% |
Full Fundamentals All metrics by year — income statement, balance sheet, cash flow
Income Statement
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Revenue | $66.61B | $57.34B | $51.46B | $48.98B | $49.69B | $47.18B | $46.00B | $42.58B | |
| Interest Expense | $70.83B | $77.00B | $61.86B | $18.05B | $8.14B | $14.05B | $21.58B | $15.07B | |
| Interest Income | $103.83B | $104.95B | $86.99B | $40.77B | $28.14B | $34.88B | $41.33B | $33.02B | |
| Pretax Income | $25.65B | $19.86B | $18.18B | $20.11B | $20.63B | $14.39B | $15.91B | $15.76B | |
| Income Tax | $5.28B | $3.62B | $3.57B | $4.30B | $4.58B | $2.95B | $3.04B | $3.33B | |
| Net Income | $20.36B | $16.23B | $14.61B | $15.79B | $16.04B | $11.43B | $12.86B | $12.40B | |
| EPS (Basic) | $14.10 | $11.27 | $10.33 | $11.08 | $11.08 | $7.84 | $8.78 | $8.39 | |
| EPS (Diluted) | $14.07 | $11.25 | $10.32 | $11.06 | $11.06 | $7.82 | $8.75 | $8.36 | |
| Shares (Basic) | 1,409,072,000 | 1,411,903,000 | 1,391,020,000 | 1,403,654,000 | 1,424,343,000 | 1,423,915,000 | 1,434,779,000 | 1,443,894 | |
| Shares (Diluted) | 1,411,589,000 | 1,413,755,000 | 1,392,529,000 | 1,406,034,000 | 1,426,735,000 | 1,428,770,000 | 1,440,682,000 | 1,450,485 | |
| EBITDA | $3.04B | $2.91B | $2.76B | $2.63B | $2.56B | $2.61B | $1.82B | $1.65B |
Balance Sheet
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $37.02B | $56.72B | $61.99B | $72.40B | $113.85B | $118.89B | $26.31B | $30.21B | |
| PP&E (Net) | $6.82B | $6.85B | $6.75B | $7.21B | $7.42B | $7.93B | $3.19B | $2.83B | |
| Goodwill | $19.41B | $19.29B | $12.59B | $12.28B | $10.85B | $11.30B | $11.24B | $11.14B | |
| Intangibles | $7.40B | $7.80B | $5.90B | $6.08B | $4.47B | $4.75B | $4.67B | $4.69B | |
| Total Assets | $2.33T | $2.17T | $2.01T | $1.92T | $1.71T | $1.62T | $1.43T | $1.33T | |
| Total Liabilities | $2.19T | $2.04T | $1.89T | $1.81T | $1.61T | $1.54T | $1.35T | $1.25T | |
| Retained Earnings | $96.94B | $88.61B | $81.72B | $78.04B | $71.80B | $59.81B | $55.98B | $51.11B | |
| Stockholders' Equity | $139.09B | $127.09B | $115.05B | $108.06B | $98.67B | $86.66B | $83.52B | $79.86B |
Cash Flow
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| D&A | $3.04B | $2.91B | $2.75B | $2.63B | $2.56B | $2.61B | $1.82B | $1.65B | |
| Other Non-cash | $31.81B | $4.00B | $8.46B | $3.51B | $42.44B | $124.78B | $-419M | $3.43B | |
| Operating Cash Flow | $55.22B | $23.14B | $26.08B | $21.94B | $61.04B | $138.82B | $14.27B | $17.47B | |
| Investing Cash Flow | $-68.57B | $-20.89B | $-28.27B | $-57.05B | $-57.35B | $-39.56B | $-11.13B | $-8.02B | |
| Dividends Paid | · | · | · | $6.96B | $6.42B | $6.33B | $6.03B | $5.64B | |
| Financing Cash Flow | $-6.71B | $-8.15B | $-9.83B | $-2.19B | $-5.93B | $-7.75B | $-7.46B | $-7.72B |
Profitability
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Net Margin | 30.6% | 28.3% | 26.5% | 32.2% | 32.3% | 24.2% | 28.0% | 29.1% | |
| Pretax Margin | 38.5% | 34.6% | 32.9% | 41.0% | 41.5% | 30.5% | 34.6% | 37.0% | |
| EBITDA Margin | 4.6% | 5.1% | 4.9% | 5.4% | 5.2% | 5.5% | 4.0% | 3.9% | |
| ROA | 0.91% | 0.78% | 0.76% | 0.87% | 0.96% | 0.75% | 0.93% | 0.97% | |
| ROE | 15.3% | 13.4% | 13.2% | 15.3% | 17.3% | 13.4% | 15.7% | 16.1% |
Efficiency
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
Per Share
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Revenue / Share | $47.18 | $40.56 | $40.31 | $34.84 | $34.83 | $33.02 | $31930.71 | $29352.94 | |
| Cash Flow / Share | $39.12 | $16.37 | $18.73 | $15.61 | $42.79 | $97.16 | $9901.56 | $12047.00 | |
| EPS (TTM) | $14.07 | $11.25 | $10.32 | $11.06 | $11.06 | $7.82 | $8.75 | $8.36 |
Valuation (TTM)
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $66.61B | $57.34B | $51.46B | $48.98B | $49.69B | $47.18B | $46.00B | $42.58B | |
| Net Income TTM | $20.36B | $16.23B | $14.61B | $15.79B | $16.04B | $11.43B | $12.86B | $12.40B | |
| P/E | 10.4 | 10.7 | 7.7 | 8.4 | 9.4 | 9.0 | 9.2 | 8.7 | |
| Earnings Yield | 9.6% | 9.3% | 12.9% | 12.0% | 10.6% | 11.2% | 10.8% | 11.5% | |
| Payout Ratio | · | · | · | 44.1% | 40.0% | 55.4% | 46.9% | 45.5% | |
| Annual Payout | · | · | · | $6.96B | $6.42B | $6.33B | $6.03B | $5.64B |
Per Share
| Metric | Trend | Q4 2025 | Q4 2017 | Q4 2016 | Q4 2015 | Q4 2014 | Q4 2013 | Q4 2012 | Q4 2011 | Q4 2010 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| EPS (TTM) | $14.07 | $7.56 | · | · | · | · | · | · | · | · | · | · | · | · | · |
Valuation (TTM)
| Metric | Trend | Q4 2025 | Q4 2017 | Q4 2016 | Q4 2015 | Q4 2014 | Q4 2013 | Q4 2012 | Q4 2011 | Q4 2010 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $66.61B | $40.67B | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| Net Income TTM | $20.36B | $11.43B | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| P/E | 10.4 | 10.3 | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| Earnings Yield | 9.6% | 9.7% | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| Annual Payout | · | $5.31B | · | · | · | · | · | · | · | · | · | · | · | · | · |
Most recent period on the left · null values shown as ·
Financial Statements Income statement, balance sheet, cash flow — annual, last 5 years
| Metric | 2025-10-31 | 2024-10-31 | 2023-10-31 | 2022-10-31 | 2021-10-31 |
|---|---|---|---|---|---|
| Revenue | $66.61B | $57.34B | $51.46B | $48.98B | $49.69B |
| Net Income | $20.36B | $16.23B | $14.61B | $15.79B | $16.04B |
| Diluted EPS | $14.07 | $11.25 | $10.32 | $11.06 | $11.06 |
Not enough fundamentals data to build this statement yet.
Not enough fundamentals data to build this statement yet.
Institutional owners (13F) 1,083 filers · $142.3B total · As of Sept. 30, 2026
Institutions that report holding this stock in their quarterly SEC Form 13F. Long positions only; a single filer may appear twice for separate option legs. Large offsetting put/call legs typically reflect market-making or hedged inventory, not directional conviction.
| New positions | Exited positions | Increased | Decreased | Net shares change |
|---|---|---|---|---|
| 120 (-12 vs prior Q) | 64 (+4 vs prior Q) | 334 (0 vs prior Q) | 341 (+42 vs prior Q) | +13.9M |
Compared to Q1 2026. SEC Form 13F filings are due within 45 days of quarter-end plus a short buffer for late filers — quarters still inside that window are skipped in favor of the most recent fully-reported pair.
| Institution | Value | Shares | % of tracked 13F | Type |
|---|---|---|---|---|
| ROYAL BANK OF CANADA | $14,533,563,000 | 70,220,631 | 10.21% | Shares |
| BANK OF MONTREAL /CAN/ | $12,529,569,629 | 60,568,915 | 8.81% | Shares |
| VANGUARD GROUP INC | $11,529,165,258 | 67,628,463 | 8.10% | Shares |
| VANGUARD CAPITAL MANAGEMENT LLC | $8,837,424,821 | 42,678,029 | 6.21% | Shares |
| MACKENZIE FINANCIAL CORP | $5,474,404,300 | 18,640,712 | 3.85% | Shares |
| FIL Ltd | $4,864,230,588 | 23,490,517 | 3.42% | Shares |
| TD Asset Management Inc | $4,753,876,354 | 22,965,684 | 3.34% | Shares |
| NORGES BANK | $4,117,728,095 | 19,905,354 | 2.89% | Shares |
| CIBC WORLD MARKET INC. | $3,786,735,367 | 18,303,156 | 2.66% | Shares |
| FMR LLC | $3,686,407,722 | 17,803,517 | 2.59% | Shares |
| 1832 Asset Management L.P. | $3,526,088,076 | 17,036,711 | 2.48% | Shares |
| GEODE CAPITAL MANAGEMENT, LLC | $3,426,400,630 | 16,045,736 | 2.41% | Shares |
| NATIONAL BANK OF CANADA /FI/ | $3,378,842,571 | 16,356,045 | 2.37% | Shares |
| Federation des caisses Desjardins du Quebec | $2,695,312,709 | 13,071,369 | 1.89% | Shares |
| VANGUARD FIDUCIARY TRUST CO | $2,567,442,657 | 12,398,792 | 1.80% | Shares |
| BANK OF NOVA SCOTIA | $2,549,157,156 | 12,311,637 | 1.79% | Shares |
| TD Waterhouse Canada Inc. | $2,427,208,742 | 11,636,208 | 1.71% | Shares |
| MANUFACTURERS LIFE INSURANCE COMPANY, THE | $2,296,716,877 | 11,113,364 | 1.61% | Shares |
| CANADA PENSION PLAN INVESTMENT BOARD | $2,275,796,586 | 11,001,378 | 1.60% | Shares |
| Connor, Clark & Lunn Investment Management Ltd. | $2,260,819,710 | 10,928,916 | 1.59% | Shares |
| Vanguard Global Advisers, LLC | $2,224,443,419 | 10,742,367 | 1.56% | Shares |
| CIBC Asset Management Inc | $2,117,783,569 | 10,212,043 | 1.49% | Shares |
| SCOTIA CAPITAL INC. | $1,758,288,574 | 8,511,247 | 1.24% | Shares |
| Legal & General Group Plc | $1,645,757,717 | 7,950,572 | 1.16% | Shares |
| TORONTO DOMINION BANK | $1,634,521,110 | 7,900,458 | 1.15% | Shares |
| Fisher Asset Management, LLC | $1,461,695,402 | 7,062,353 | 1.03% | Shares |
| JPMORGAN CHASE & CO | $1,403,946,317 | 6,855,539 | 0.99% | Shares |
| GOLDMAN SACHS GROUP INC | $1,089,906,023 | 5,266,010 | 0.77% | Shares |
| MORGAN STANLEY | $824,775,725 | 3,985,000 | 0.58% | Shares |
| CHARLES SCHWAB INVESTMENT MANAGEMENT INC | $815,298,736 | 3,938,658 | 0.57% | Shares |
| Fiera Capital Corp | $800,513,843 | 3,872,821 | 0.56% | Shares |
| BAILLIE GIFFORD & CO | $740,153,088 | 3,575,634 | 0.52% | Shares |
| PICTON MAHONEY ASSET MANAGEMENT | $684,750,909 | 3,315,100 | 0.48% | Shares |
| VANGUARD ASSET MANAGEMENT, Ltd | $653,186,284 | 3,154,398 | 0.46% | Shares |
| HEALTHCARE OF ONTARIO PENSION PLAN TRUST FUND | $635,819,791 | 3,073,436 | 0.45% | Shares |
| Public Sector Pension Investment Board | $625,129,975 | 3,021,927 | 0.44% | Shares |
| BRITISH COLUMBIA INVESTMENT MANAGEMENT Corp | $588,345,296 | 2,844,107 | 0.41% | Shares |
| MASSACHUSETTS FINANCIAL SERVICES CO /MA/ | $577,116,710 | 2,000,754 | 0.41% | Shares |
| DIMENSIONAL FUND ADVISORS LP | $540,485,863 | 2,611,521 | 0.38% | Shares |
| DEUTSCHE BANK AG\ | $540,037,301 | 2,609,254 | 0.38% | Shares |
| Amundi | $535,456,408 | 2,586,842 | 0.38% | Shares |
| WELLINGTON MANAGEMENT GROUP LLP | $528,596,674 | 2,553,618 | 0.37% | Shares |
| AGF MANAGEMENT LTD | $522,781,370 | 2,228,739 | 0.37% | Shares |
| OMERS ADMINISTRATION Corp | $430,658,976 | 2,080,487 | 0.30% | Shares |
| FRANKLIN RESOURCES INC | $412,609,381 | 1,994,581 | 0.29% | Shares |
| MUFG SECURITIES (CANADA), LTD. | $408,754,132 | 1,977,134 | 0.29% | Shares |
| Caisse de depot et placement du Quebec | $360,367,457 | 1,740,913 | 0.25% | Shares |
| Invesco Ltd. | $331,336,278 | 1,600,890 | 0.23% | Shares |
| GUARDIAN CAPITAL LP | $330,433,521 | 1,596,304 | 0.23% | Shares |
| Assenagon Asset Management S.A. | $329,001,942 | 1,589,605 | 0.23% | Shares |
Activists & 5%+ owners 4 positions
Investors who filed SEC Schedule 13D — beneficial ownership above 5% with an intent to influence the issuer (activist stakes, board campaigns, M&A). Each row shows the most recent known state of that filer's position.
| Filer | Filed | Stake | Status | Purpose | Filing |
|---|---|---|---|---|---|
| Royal Bank of Canada, RBC Municipal Products, LLC ×9 filings | Aug. 28, 2017 | · | Initial filing | · | SEC |
| Undisclosed reporting person | Oct. 16, 2002 | · | Initial filing | M&A / sale | SEC |
| Undisclosed reporting person | Aug. 13, 2001 | · | Initial filing | M&A / sale | SEC |
| Undisclosed reporting person | July 10, 2001 | · | Initial filing | · | SEC |
Purpose is an automated classification of the filer's own stated purpose (SEC Item 4) — not investment advice. "—" means no clear purpose was stated or the text could not be classified.
ETF ownership Held by 71 ETFs
Weight reflects direct equity holdings (N-PORT) only; leveraged or derivative-based funds may hold additional swap exposure not shown.
| Fund | Weight | Units | As of | Source |
|---|---|---|---|---|
| BBCA · J.P. Morgan Exchange-Traded Fund Tr… | 9.59% | 4,974,197 NS | July 31, 2026 | N-PORT |
| EWC · iShares, Inc. | 9.27% | 3,070,526 SH | Sept. 11, 2026 | Daily |
| IDMO · Invesco Exchange-Traded Fund Trust … | 5.14% | 1,121,704 SH | Oct. 1, 2026 | Daily |
| VIGI · VANGUARD WHITEHALL FUNDS | 4.90% | 2,153,489 SH | Aug. 19, 2026 | Daily |
| IMTM · iShares Trust | 3.29% | 690,878 SH | Sept. 11, 2026 | Daily |
| QLVD · FlexShares Trust | 2.97% | 7,776 NS | July 31, 2026 | N-PORT |
| IGRO · iShares Trust | 2.80% | 175,358 SH | Sept. 11, 2026 | Daily |
| PIZ · Invesco Exchange-Traded Fund Trust … | 2.23% | 74,655 SH | Oct. 1, 2026 | Daily |
| DIVD · EA Series Trust | 2.12% | 2,166 NS | July 31, 2026 | N-PORT |
| FEDM · FlexShares Trust | 1.98% | 7,497 NS | July 31, 2026 | N-PORT |
| IXG · iShares Trust | 1.80% | 60,633 SH | Sept. 11, 2026 | Daily |
| PABD · iShares Trust | 1.58% | 25,388 SH | Sept. 11, 2026 | Daily |
| VYMI · VANGUARD WHITEHALL FUNDS | 1.57% | 1,562,557 SH | Aug. 19, 2026 | Daily |
| EFFI · Harbor ETF Trust | 1.49% | 10,987 NS | July 31, 2026 | N-PORT |
| PID · Invesco Exchange-Traded Fund Trust | 1.35% | 57,689 SH | Oct. 1, 2026 | Daily |
| BSCR · Invesco Exchange-Traded Self-Indexe… | 1.28% | 58,104,000 | Oct. 1, 2026 | Daily |
| FIDI · Fidelity Covington Trust | 1.23% | 21,306 NS | July 31, 2026 | N-PORT |
| RODM · Lattice Strategies Trust | 1.22% | 95,068 NS | July 31, 2026 | N-PORT |
| PTIN · Pacer Funds Trust | 1.22% | 10,763 NS | July 31, 2026 | N-PORT |
| PICB · Invesco Exchange-Traded Fund Trust … | 1.19% | 5,300,000 | Oct. 1, 2026 | Daily |
| INTF · iShares Trust | 1.18% | 214,432 SH | Sept. 11, 2026 | Daily |
| FDEV · Fidelity Covington Trust | 1.13% | 15,359 NS | July 31, 2026 | N-PORT |
| BKIE · BNY Mellon ETF Trust | 1.13% | 70,741 NS | July 31, 2026 | N-PORT |
| DFSI · Dimensional ETF Trust | 1.12% | 61,409 NS | July 31, 2026 | N-PORT |
| JIVE · J.P. Morgan Exchange-Traded Fund Tr… | 1.09% | 181,623 NS | July 31, 2026 | N-PORT |
| DFAI · Dimensional ETF Trust | 0.99% | 829,128 NS | July 31, 2026 | N-PORT |
| IDEV · iShares Trust | 0.97% | 1,531,433 SH | Sept. 11, 2026 | Daily |
| VEA · VANGUARD TAX-MANAGED FUNDS | 0.88% | 13,680,318 SH | Aug. 19, 2026 | Daily |
| DFIC · Dimensional ETF Trust | 0.87% | 614,054 NS | July 31, 2026 | N-PORT |
| VSGX · VANGUARD WORLD FUND | 0.86% | 280,967 SH | Aug. 19, 2026 | Daily |
| IQDY · FlexShares Trust | 0.84% | 4,446 NS | July 31, 2026 | N-PORT |
| ACWX · iShares Trust | 0.76% | 459,819 SH | Sept. 11, 2026 | Daily |
| COMT · iShares U.S. ETF Trust | 0.74% | 10,070,000 SH | Sept. 11, 2026 | Daily |
| VEU · VANGUARD INTERNATIONAL EQUITY INDEX… | 0.70% | 3,272,998 SH | Aug. 19, 2026 | Daily |
| GLBL · Pacer Funds Trust | 0.70% | 37 NS | July 31, 2026 | N-PORT |
| IDLV · Invesco Exchange-Traded Fund Trust … | 0.67% | 10,859 SH | Oct. 1, 2026 | Daily |
| IXUS · iShares Trust | 0.66% | 1,919,984 SH | Sept. 11, 2026 | Daily |
| VXUS · VANGUARD STAR FUNDS | 0.64% | 20,563,849 SH | Aug. 19, 2026 | Daily |
| IQDF · FlexShares Trust | 0.63% | 34,650 NS | July 31, 2026 | N-PORT |
| DFAX · Dimensional ETF Trust | 0.61% | 351,449 NS | July 31, 2026 | N-PORT |
| PXF · Invesco Exchange-Traded Fund Trust … | 0.55% | 81,239 SH | Oct. 1, 2026 | Daily |
| TLTD · FlexShares Trust | 0.54% | 17,391 NS | July 31, 2026 | N-PORT |
| RCGE · EA Series Trust | 0.49% | 2,340 NS | July 31, 2026 | N-PORT |
| GSY · Invesco Actively Managed Exchange-T… | 0.47% | 17,933,000 | Oct. 1, 2026 | Daily |
| BSCS · Invesco Exchange-Traded Self-Indexe… | 0.41% | 14,181,000 | Oct. 1, 2026 | Daily |
| DXIV · Dimensional ETF Trust | 0.38% | 3,700 NS | July 31, 2026 | N-PORT |
| TOK · iShares Trust | 0.34% | 3,893 SH | Sept. 11, 2026 | Daily |
| URTH · iShares, Inc. | 0.32% | 125,484 SH | Sept. 11, 2026 | Daily |
| VOXP · Advisors Series Trust | 0.31% | 87 NS | July 31, 2026 | N-PORT |
| CRBN · iShares Trust | 0.31% | 17,690 SH | Sept. 11, 2026 | Daily |
| ACWI · iShares Trust | 0.28% | 442,504 SH | Sept. 11, 2026 | Daily |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0.25% | 1,160,961 SH | Aug. 19, 2026 | Daily |
| BSCT · Invesco Exchange-Traded Self-Indexe… | 0.23% | 6,883,000 | Sept. 30, 2026 | Daily |
| IMFL · Invesco Exchange-Traded Self-Indexe… | 0.15% | 8,234 SH | Oct. 1, 2026 | Daily |
| DIHP · Dimensional ETF Trust | 0.05% | 14,362 NS | July 31, 2026 | N-PORT |
| GTO · Invesco Actively Managed Exchange-T… | 0.03% | 1,028,000 | Oct. 1, 2026 | Daily |
| GTOS · Invesco Actively Managed Exchange-T… | 0.03% | 38,000 | Oct. 1, 2026 | Daily |
| GLOF · iShares Trust | 0.02% | 205 SH | Sept. 11, 2026 | Daily |
| VRIG · Invesco Actively Managed Exchange-T… | 0.01% | 200,000 | Sept. 29, 2026 | Daily |
| FTLS · First Trust Exchange-Traded Fund III | -0.22% | -25,586 NS | July 31, 2026 | N-PORT |
| BIV · VANGUARD BOND INDEX FUNDS | · | · | July 15, 2026 | Daily |
| BSV · VANGUARD BOND INDEX FUNDS | · | · | July 15, 2026 | Daily |
| BND · VANGUARD BOND INDEX FUNDS | · | · | July 15, 2026 | Daily |
| VUSB · VANGUARD BOND INDEX FUNDS | · | · | July 15, 2026 | Daily |
| VCRB · VANGUARD MALVERN FUNDS | · | · | July 15, 2026 | Daily |
| VCSH · VANGUARD SCOTTSDALE FUNDS | · | · | July 15, 2026 | Daily |
| VCIT · VANGUARD SCOTTSDALE FUNDS | · | · | July 15, 2026 | Daily |
| VTC · VANGUARD SCOTTSDALE FUNDS | · | · | July 30, 2026 | Daily |
| BNDW · VANGUARD SCOTTSDALE FUNDS | · | · | July 30, 2026 | Daily |
| BNDX · VANGUARD CHARLOTTE FUNDS | · | · | July 15, 2026 | Daily |
| VCEB · VANGUARD WORLD FUND | · | · | July 30, 2026 | Daily |
RY Analyst Consensus Bullish and bearish analyst opinions, 12-month price target, upside
12-Month Price Target
3 analysts · 2026-10-01Mean target $207.80 +6.2%
Latest News Recent headlines mentioning this company
RY AI Analyst Panel — Bullish and Bearish Views 2026Q2 debate: Claude, Grok, Gemini, ChatGPT on the stock's prospects
Royal Bank of Canada faces a tug-of-war between its status as a high-efficiency lender and the reality of a cooling interest rate environment. Grok remains bullish, betting that resilient margins will drive the stock higher, while Claude, Gemini, and ChatGPT warn that the current 15.7 P/E multiple is already pricing in perfection. The panel split sharply on whether the bank's 15.4% ROE justifies its premium valuation or if a looming rate-cut cycle will inevitably compress future earnings.
Round 1 — Opening Takes
I see RY delivering steady growth as Canada's largest bank capitalizes on a soft economic landing and higher-for-longer rates. Its ROE has risen to 15.37%, proving efficient use of equity to generate profits amid stabilizing loans. EPS TTM hit $14.94, reflecting resilient earnings power that funds reliable dividends. At a P/E of 15.7, the stock trades at a reasonable multiple, leaving room for multiple expansion if trends hold.
RY crumbles if aggressive rate cuts spark loan defaults and squeeze net interest margins in a downturn. Debt-to-equity lingers around 2.5, amplifying risks from any credit cycle turn that hits asset quality. P/B at 2.07 feels full when ROE growth stalls, exposing shareholders to book value erosion. Recent price stalls near $132 after a run-up, signaling potential exhaustion if macro headwinds hit.
Royal Bank is a fortress balance sheet generating fortress returns in a sector where capital discipline matters. My read is that a 15.4% ROE — that's the profit generated per dollar of shareholder equity — is genuinely strong for a regulated bank, and the 26% net margin tells you pricing power is real even in a competitive Canadian market. The stock has climbed from $117 to $132 in four months, yet the P/E has only ticked from 13.0 to 15.7. That suggests the market is still pricing in caution, not euphoria. If rate volatility stabilizes and loan growth accelerates, this trades higher.
The bull case assumes rates stay elevated and loan demand rebounds — but I see structural headwinds. The P/B ratio of 2.07 is not cheap for a bank, especially one levered 2.5 times debt-to-equity, which is normal for the sector but leaves zero room for credit surprises. More important: the market cap has shrunk from $337B to $329B in one quarter while the stock price held flat. That's a warning sign of multiple compression. If Canadian economic growth disappoints or deposit competition intensifies, net margins compress and the stock re-rates lower.
Royal Bank of Canada remains a defensive fortress that consistently turns shareholder capital into meaningful profit. The company generates a 15.37% return on equity. This level of efficiency shows that management is adept at squeezing value out of its capital base even in a tightening interest rate environment. Furthermore, the bank maintains a robust 26.26% net profit margin. This indicates that more than a quarter of every dollar brought in as revenue actually hits the bottom line, providing a significant cushion against potential loan losses or economic volatility in the Canadian housing market.
The stock is starting to look expensive relative to its own historical valuation, suggesting the market may have already priced in the best-case scenario. The P/E ratio has climbed to 15.67 times trailing earnings. This multiple is trending upward, meaning investors are paying more today for the same dollar of profit than they were just a few quarters ago. Additionally, the price-to-book ratio sits at 2.07. Paying double the accounting value for a bank stock is a steep premium that leaves very little room for error if growth stalls or credit conditions deteriorate.
I think RBC's strongest bullish case is that it combines durable earnings power with a reasonable valuation. P/E TTM is about 15.7x. That implies the market pays a fair multiple for a high-quality bank with steady earnings. Net profit margin runs around 26.3%. That means RBC converts a large share of revenue into profit, supporting steadier earnings power. ROE is about 15.4%. That shows efficient use of equity and returns that can support dividend growth. If these trends hold, the stock could compound on earnings resilience plus favorable multiple support.
I think RBC's strongest bearish case is that leverage and cyclicality could bite if growth slows. P/S TTM sits near 3.0x. That signals the market has priced in solid growth; a slowdown could compress the multiple. Debt/Equity around 2.5x. High leverage increases sensitivity to credit costs and economic downturns. P/B annual is about 2.07x. That leaves little cushion if ROE normalizes or regulatory/credit headwinds rise. Bottom line: valuation looks robust enough to cap upside if macro surprises tilt negative.
Round 2 — Responses & Rebuttals
Round 2 — Responses & Rebuttals
Claude, your market cap shrink from $337 billion to $329 billion misses the real price action story — shares have rallied 12% from $118 in late April to $132 today. That climb shows investor demand overriding any share dilution, backing my buy case as higher-for-longer rates boost net interest income. P/B at 2.07 still looks fair when ROE efficiency hits 15.4%, signaling room for expansion if loan growth resumes.
I need to push back on Grok's confidence here. Grok says the P/E of 15.7 leaves room for multiple expansion, but that misses what I flagged in Round 1 — the P/E has jumped from 13.0 to 15.7 in just nine months while the stock climbed only 12%. That's multiple expansion already happening, and it's happening faster than earnings growth. If the market has already re-rated RY from a 13x to a 15.7x multiple on the same earnings power, the easy money is gone. The next move requires actual earnings acceleration, not just multiple support. Grok's 'buy' case leans too heavily on valuation staying elevated.
Claude, your point about the market cap shrinking while the stock price held steady is a critical observation that highlights a subtle liquidity or share-count dilution risk. The market cap fell from $337 billion to $329 billion in one quarter. This signals that the total value the market assigns to the bank is contracting even as the share price remains range-bound, which often precedes a deeper correction. I agree that we are seeing multiple compression, and this divergence between price action and total equity value makes me even more cautious about chasing the stock at these levels.
Claude, your point about P/E expansion implying caution misses why the multiple can still reflect earnings power here. P/E is about 15.7x, up from roughly 13x earlier. That means investors are pricing in steadier profits and resilient returns, which could support a selective upside for RBC if rates stabilize and credit risk remains manageable; the risk is that leverage and cyclicality still blur the cushion, so entry timing matters.
Round 3 — Final Rebuttals
Round 3 — Final Rebuttals
Gemini, your share-count dilution warning from the market cap dip misses the technical breakout that's drawing in buyers. RY surged 12% from $118 in late April to $132 now, smashing $130 resistance on weekly volumes topping 5 million shares. That flow pattern shows institutions positioning long ahead of Bank of Canada rate stability boosting NIM into 2026Q2, overriding any issuance noise.
I want to push back on ChatGPT's framing here. ChatGPT says the P/E of 15.7x reflects 'steadier profits and resilient returns,' but that's backwards — it reflects what the market is *willing to pay*, not what the earnings justify. The real question is whether those earnings are actually accelerating. Look at the data: EPS TTM is $14.94, but I don't see quarter-over-quarter EPS growth in the raw fundamentals you've given us. The P/E expanded from 13.0 to 15.7 while the stock climbed 12%, which means multiple expansion is outpacing earnings growth. That's not a vote of confidence in future earnings — that's the market front-running a story that hasn't proven out yet. Until I see actual EPS acceleration, not just multiple support, I'm staying cautious.
I am widening the frame to address the macro regime, specifically the impact of the Bank of Canada's recent policy pivot. Grok, your buy thesis assumes higher-for-longer rates, but the market is already pricing in a shift toward a neutral rate environment by 2026. This transition will compress net interest margins, which is the primary engine for RBC’s 26.26% net profit margin. That metric represents the actual slice of revenue RBC keeps after all costs, and it is highly sensitive to yield curve flattening. Relying on rate-driven income is a dangerous bet when the central bank is actively moving to lower borrowing costs.
I think the big remaining swing for RBC in 2026Q2 lies outside the bank's quarterly numbers: macro and regulatory regime. Claude, Grok, Gemini, the rate path set by the Bank of Canada and OSFI's capital/dividend policy are the levers that can re-rate RBC independently of ROE or margins. If the BoC stays higher-for-longer and regulators keep a tight stance on capital and payouts, the stock can drift lower even with steady earnings. A clearer rate path and predictable rules could unlock multiple expansion.
Price Forecasts
| Model | 3M Target | 6M Target | Reasoning |
|---|---|---|---|
| Grok | $140.00 | $152.00 | I expect RY to rally on resilient NIM from rate stability, rewarding its top-tier ROE as Canada's loan market recovers. The key catalyst is the Bank of Canada's September 3, 2025 policy meeting, where a hold or shallow cut confirms higher-for-longer rates, unlocking NIM expansion into Q4. The big risk is Q3 2025 earnings revealing higher credit provisions from housing weakness, crushing margins. ROE at 15.4% means RY generates strong profits per equity dollar versus peers, justifying a P/E re-rating to 17x on $14.94 EPS for my $152 target. |
| Claude | $128.00 | $124.00 | My thesis is that RY has already priced in the easy multiple expansion, and the next 6 months will test whether earnings actually accelerate or whether the market re-rates lower on macro disappointment. The concrete catalyst that could push toward $135+ is a Q2 2026 earnings beat with quarter-over-quarter EPS growth above 5% — that would validate the P/E re-rating from 13.0 to 15.7. The concrete risk that breaks this is a Bank of Canada rate cut cycle that compresses net margins below 25%, which is the engine of RY's 26.3% margin today. At 15.7x trailing earnings, the market is already paying a full multiple for a bank in a normalizing rate environment, leaving little cushion. I see consolidation to $128 in 3 months, then drift to $124 by 6 months as rate-cut expectations intensify and multiple compression resumes. |
| Gemini | $122.00 | $115.00 | My thesis is that RBC faces a valuation correction as the market realizes that current multiples are unsustainable in a softening interest rate environment. The key catalyst for a decline will be the 2026Q3 earnings report, where I expect to see margin compression as the Bank of Canada’s rate cuts finally hit net interest income. Conversely, a surprise spike in Canadian household credit demand would break my bearish thesis. We are currently looking at a P/E of 15.67, which means investors are paying a premium for earnings that are likely to peak in the current cycle. This valuation is simply too rich for a bank entering a period of margin contraction. |
| Chatgpt | $121.00 | $126.00 | I think RBC offers durable earnings power with modest upside if the rate path stays constructive. The catalyst is the Bank of Canada’s upcoming rate decision signaling rates staying higher-for-longer, which would keep NIM healthy and could lift the stock's multiple. The risk is a sharper macro downturn or a housing-led credit shock that would squeeze margins and ROE, potentially triggering multiple compression. EPS TTM is $14.94. That earnings base supports a steady dividend and gives the stock room to rise if rate visibility remains supportive. |
My Metrics Your personal watchlist — selected rows from Full Fundamentals
Pick the metrics that matter to you — click the + next to any row in Full Fundamentals above.
Your selection is saved and follows you across all tickers.