SNY Sanofi - American Depositary Shares
NASDAQ · Pharmaceuticals · Ver en SEC EDGAR ↗ cerrar Oct 2, 2026 10-K/10-Q Feb 17, 2026SNY Instantánea de la Acción Precio, capitalización bursátil, P/E, BPA, ROE, deuda/capital, rango de 52 semanas
SNY Gráfico del Precio de la Acción OHLCV diario con indicadores técnicos — desplace, amplíe y personalice su vista
La granularidad de las barras se adapta al período seleccionado; pase el ratón sobre el gráfico para ver la apertura/máximo/mínimo/cierre de una barra.
Acerca de Sanofi - American Depositary Shares Descripción general de la empresa de Wikipedia
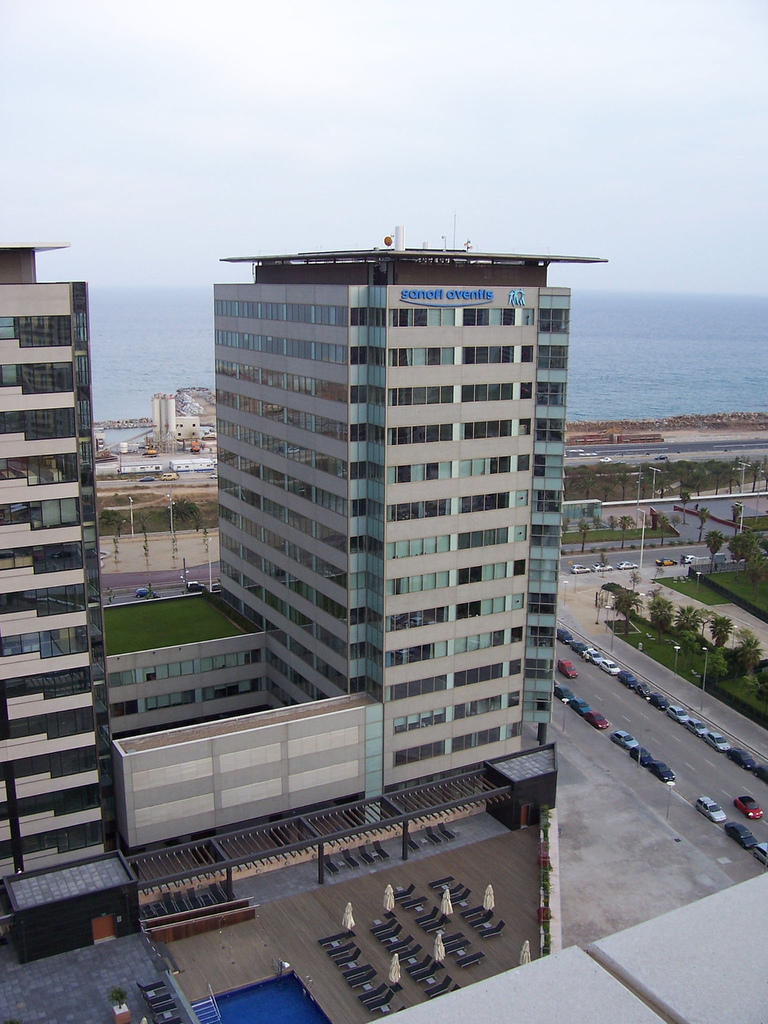
La firma Sanofi es la sucesora directa de los anteriores conglomerados Aventis-pharma y Sanofi-Synthélabo, surgida en el año 2004 mediante su fusión por la compra de la segunda por la primera (OPA hostil). A su vez, Sanofi-Synthelabó es la sucesora legal de las firmas Hoechst, de Alemania, y Rhône-Poulenc Rorer y Sanofi, de Francia.
Historia
Sanofi-Aventis es un grupo farmacéutico europeo nacido en 2004 de la fusión de la francesa Sanofi-Synthélabo y la francoalemana Aventis (que fue, a su vez, el resultado de la fusión de la empresa alemana Hoechst y la francesa Rhône Poulenc). Sanofi-Aventis es una de las compañías farmacéuticas líderes en el mundo, la primera en Europa y la tercera a nivel mundial. Está presente en más de 100 países de los cinco continentes, y tiene más de 80 plantas industriales y cerca de 100 000 empleados en todo el mundo.
Investigación
Basada en una amplia red de centros para la investigación a nivel internacional, la actividad de Sanofi-Aventis se concentra en siete importantes áreas terapéuticas:
cardiovascular
trombosis
oncología
enfermedades metabólicas
sistema nervioso central
medicina interna
vacunas (aunque dejaron de fabricar antídotos contra el veneno de serpientes en 2012)
Situación a nivel global
Sanofi-Aventis cuenta con más de veinte centros de investigación en tres continentes. El presupuesto anual para I+D abarca algo más de 4000 millones de euros, siendo uno de los tres más importantes de la industria farmacéutica a nivel mundial.[cita requerida]
Los beneficios de la empresa, como los de toda la industria farmacéutica, proceden principalmente de los fondos públicos dedicados a la sanidad y la seguridad social. En 2017, Sanofi se benefició así de 561 millones en reembolsos del seguro médico francés.
En 2018, el grupo pagó casi 5000 millones de euros a sus accionistas en forma de dividendos y recompra de acciones, es decir, el 114 % de sus beneficios.
Presencia en Argentina
En Argentina se encuentra entre las diez más importantes empresas del sector farmacéutico. A nivel local, comercializa medicamentos de venta bajo receta, venta libre y vacunas. Además, desarrolla actividades de responsabilidad social y compromiso con el cuidado del medio ambiente.
Presencia en México
Sanofi está presente en México desde hace 91 años comercializando productos para salud humana para enfermedades cardiovasculares, diabetes, enfermedades huérfanas, medicamentos genéricos a través de su línea Medley, medicamentos para las áreas pediátricos, oncológicos y vacunas para la prevención de enfermedades como influenza. Actualmente suma a su portafolio una gama de productos para el cuidado de la salud animal.
Presencia en Colombia
La firma Sanofi hace presencia en el mercado centro y suramericano de forma directa desde su base de producción, adquirida a la local Genfar, por un valor superior a los US$ 250 millones, en el Valle del Cauca, Cauca y Bogotá; donde tiene distribuidas sus plantas en Colombia.
La firma produce para los citados mercados productos de farma humana y farma animal, incluidas vacunas (Sanofi-Pasteur) y medicinas genéricas de uso humano (Genfar).
Comercio en bolsas de valores
Sanofi-Aventis cotiza en las bolsas de París (Euronext: SAN) y Nueva York (NYSE: SNY) y en el CAC 40.
Línea de productos
Estos son algunos de los medicamentos de Sanofi-Aventis:
Lantus® (insulina glargina).
Toujeo® (insulina glargina).
Plavix® (clopidogrel).
Clexane© / Lovenox© (enoxaparina).
Amaryl© / Allegra© (neomelubrina).
Aprovel© / Avapro© (irbesartán).
Hiperlipen® (ciprofibrato).
Multaq® (dronedarona, aprobado por la FDA en julio de 2009; recomendada su autorización por parte de la EMEA en septiembre de 2009).
Vacuna para el COVID-19
Sanofi junto con GSK firmaron un acuerdo con la Operación Warp Speed del gobierno de Estados Unidos Para proporcionar 300 millones de dosis de la vacuna COVID-19 para Europa y 100 millones para los Estados Unidos.
A partir de agosto de 2020, el desarrollo de la vacuna COVID-19 en Sanofi subraya su debilidad fundamental de competitividad, que la administración ha estado luchando y no ha podido abordar durante los últimos años más allá de reducir más costos. Desafortunadamente, aunque el enfoque de Sanofi-GSK se basa en una plataforma y tecnología aprobadas y preexistentes (como con la gripe Flublok) sin reinventar la rueda de la infraestructura necesaria, la empresa va por detrás de muchos otros rivales en la entrega de una vacuna que funcione. Sanofi planea comenzar las pruebas clínicas de Fase 1 solo en septiembre y espera la aprobación de uso de emergencia en el primer semestre de 2021. Competidores como Novavax ya completaron la Fase 1 con resultados prometedores y Moderna-NIH ya inició su ensayo de Fase 3. Según los informes de CNBC, como parte del acuerdo del gobierno de Estados Unidos por 2100 millones, más de 750 millones se destinan a apoyar a Sanofi-GSK en el desarrollo de vacunas y ensayos clínicos. Sanofi resulta "acelerar" el desarrollo a través de la empresa de biotecnología más pequeña Translate Bio, con una asociación de 425 millones.
== Referencias ==
Fuente: Wikipedia, CC BY-SA 4.0 · Ver en Wikipedia ↗
Rendimiento a 10 años Tendencias de ingresos, beneficio neto, márgenes y BPA
Valoración Ratios P/E, P/S, P/B, EV/EBITDA: ¿está la acción cara o barata?
| Métrica | Tendencia a 5 años | SNY | promedio 5A | Mediana de Pares | Veredicto |
|---|---|---|---|---|---|
| P/E | 7.6promedio 5A ≈9.3 | ≈9.3 | · | · |
La mediana de empresas comparables se calcula sobre una base estandarizada por métrica y puede no coincidir siempre con la base TTM/MRQ que se muestra para esta acción.
Rentabilidad Márgenes brutos, operativos y netos; ROE, ROA, ROIC
| Métrica | Tendencia a 5 años | SNY | promedio 5A | Mediana de Pares | Veredicto |
|---|---|---|---|---|---|
| ROA | 6.0%promedio 5A ≈5.3% | ≈5.3% | · | · | |
| ROE | 10.5%promedio 5A ≈9.2% | ≈9.2% | · | · |
Salud financiera Deuda, liquidez, solvencia — solidez del balance general
| Métrica | Tendencia a 5 años | SNY | promedio 5A | Mediana de Pares | Veredicto |
|---|---|---|---|---|---|
| Current Ratio (Ratio corriente) | 1.1 | · | · | · | |
| Quick Ratio (Ratio Rápido) | 0.0 | · | · | · | |
| Interest Coverage (Cobertura de Intereses) | 11.3promedio 5A ≈14.1 | ≈14.1 | · | · |
Crecimiento Crecimiento de ingresos, BPA y beneficio neto: interanual, CAGR a 3 años, CAGR a 5 años
Aún no hay datos fundamentales para este ticker.
Eficiencia de capital Rotación de activos, rotación de inventario, rotación de cuentas por cobrar
| Métrica | Tendencia a 5 años | SNY | promedio 5A | Mediana de Pares | Veredicto |
|---|---|---|---|---|---|
| Inventory Turnover (Rotación de Inventario) | 1.3promedio 5A ≈1.4 | ≈1.4 | · | · |
valor · ≈ promedio 5A · mediana sectorial · veredicto relativo a la mediana
Dividendos Rendimiento, ratio de pago, historial de dividendos, CAGR a 5 años
| Fecha ex-dividendo | Monto | Moneda | Rendimiento |
|---|---|---|---|
| May 4, 2026 | $2,42 | USD | ≈5.6% |
| May 9, 2025 | $2,21 | USD | ≈4.4% |
| May 9, 2024 | $2,04 | USD | ≈4.2% |
| May 30, 2023 | $1,90 | USD | ≈3.8% |
| May 26, 2022 | $0,30 | USD | ≈3.7% |
| May 4, 2022 | $1,75 | USD | ≈3.3% |
| May 3, 2021 | $1,91 | USD | ≈3.7% |
| Abr 30, 2020 | $1,75 | USD | ≈3.7% |
| May 7, 2019 | $1,74 | USD | ≈4.2% |
| May 9, 2018 | $1,86 | USD | ≈4.9% |
| May 11, 2017 | $1,58 | USD | ≈3.3% |
| May 5, 2016 | $1,63 | USD | ≈4.2% |
| May 6, 2015 | $1,62 | USD | ≈3.3% |
| May 7, 2014 | $1,91 | USD | ≈3.6% |
| May 6, 2013 | $1,86 | USD | ≈3.5% |
| May 7, 2012 | $1,76 | USD | ≈4.8% |
| May 11, 2011 | $1,82 | USD | ≈4.8% |
| May 17, 2010 | $1,63 | USD | ≈5.4% |
| Abr 20, 2009 | $1,42 | USD | ≈5.4% |
| May 16, 2008 | $1,51 | USD | ≈4.1% |
Historial de Ganancias EPS real vs estimado, sorpresa %, tasa de aciertos, próxima fecha de resultados
| Período | Informe | EPS Actual | EPS est. | Sorpresa |
|---|---|---|---|---|
| 30 de junio de 2026 | $2.09 | $1.92 | 8.9% | |
| 31 de marzo de 2026 | $1.88 | $1.81 | 4.1% | |
| 31 de diciembre de 2025 | $1.53 | $1.46 | 4.6% | |
| 30 de septiembre de 2025 | $2.91 | $2.75 | 5.9% | |
| 30 de junio de 2025 | $1.59 | $1.63 | -2.3% | |
| 31 de marzo de 2025 | $1.53 | $1.46 | 4.6% |
Fundamentales Completos Todas las métricas por año — estado de resultados, balance general, flujo de caja
Estado de resultados
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Cost of Revenue | $13.05B | $13.21B | $12.63B | $11.88B | $12.26B | $12.16B | $11.98B | $11.44B | $11.61B | $10.70B | |
| Gross Profit | $33.67B | $31.08B | $28.99B | $28.68B | $26.92B | $25.21B | $25.65B | $24.24B | $24.61B | $24.00B | |
| R&D Expense | $7.84B | $7.39B | $6.51B | $6.50B | $5.69B | $5.53B | $6.02B | $5.89B | $5.47B | $5.17B | |
| SG&A Expense | $9.54B | $9.18B | $8.93B | $8.74B | $9.55B | $9.39B | $9.88B | $9.86B | $10.07B | $9.48B | |
| Operating Income | $6.34B | $7.25B | $6.96B | $10.16B | $8.13B | $14.11B | $3.05B | $4.68B | $5.80B | $6.53B | |
| Interest Expense | $563M | $1.07B | $1.29B | $430M | $368M | $388M | $440M | $435M | $420M | $924M | |
| Interest Income | $394M | $519M | $584M | $205M | $40M | $53M | $141M | $164M | $147M | $68M | |
| Income Tax | $1.04B | $1.20B | $1.02B | $1.91B | $1.56B | $1.81B | $121M | $481M | $1.72B | $1.32B | |
| Net Income | $7.81B | $5.56B | $5.40B | $8.37B | $6.22B | $12.29B | $2.75B | $4.31B | $8.42B | $4.71B | |
| EPS (Basic) | $6.40 | $4.44 | $4.31 | $6.69 | · | $9.82 | $2.24 | $3.45 | $6.70 | $3.66 | |
| EPS (Diluted) | $6.37 | $4.43 | $4.30 | $6.66 | · | $9.77 | $2.23 | $3.43 | $6.64 | $3.63 | |
| Shares (Basic) | 1,220,400,000 | 1,251,400,000 | 1,251,700,000 | 1,251,900,000 | 1,252,500,000 | 1,253,600,000 | 1,249,900,000 | 1,247,100,000 | 1,256,900,000 | 1,286,600,000 | |
| Shares (Diluted) | 1,225,600,000 | 1,256,100,000 | 1,256,400,000 | 1,256,900,000 | 1,256,900,000 | 1,260,100,000 | 1,257,100,000 | 1,255,200,000 | 1,266,800,000 | 1,296,000,000 | |
| EBITDA | $6.34B | $7.25B | $7.88B | $10.66B | $8.13B | $14.14B | $3.12B | $4.68B | $5.80B | · |
Balance general
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $877M | $1.27B | $1.46B | $1.39B | $1.36B | $1.14B | $701M | $661M | $472M | $1.08B | |
| Inventory | $10.21B | $9.43B | $9.67B | $8.96B | $8.71B | $8.35B | $7.99B | $7.48B | $6.82B | $6.90B | |
| Current Assets | $30.95B | $42.59B | $30.67B | $34.11B | · | · | · | · | · | · | |
| PP&E (Net) | $10.05B | $10.09B | $10.16B | $9.87B | $10.03B | $9.37B | $9.72B | $9.65B | $9.58B | $10.02B | |
| Goodwill | $41.30B | $43.38B | $49.40B | $49.89B | $48.06B | $44.36B | $44.52B | $44.23B | $40.26B | $40.29B | |
| Intangibles | $26.26B | $22.63B | $24.32B | $21.64B | $21.41B | $18.34B | $16.51B | $21.89B | $13.08B | $10.88B | |
| Total Assets | $126.81B | $132.80B | $126.46B | $126.72B | $120.24B | $114.41B | $112.63B | $111.41B | $99.81B | $104.68B | |
| Current Liabilities | $28.34B | $29.16B | $24.21B | $23.97B | · | · | · | · | · | · | |
| Stockholders' Equity | $71.38B | $77.51B | $74.04B | $74.78B | $68.68B | $63.11B | $59.06B | $58.88B | $58.07B | $57.55B |
Flujo de Efectivo
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Cash Flow | $10.75B | $9.08B | $10.26B | $10.53B | $10.52B | $7.42B | $7.71B | $5.55B | $7.38B | $7.84B | |
| Investing Cash Flow | $-2.45B | $-4.41B | $-6.20B | $-2.08B | $-7.30B | $3.62B | $-1.18B | $-12.87B | $-2.90B | $-2.51B | |
| Financing Cash Flow | $-8.21B | $-5.76B | $-8.05B | $-5.82B | $-7.06B | $-6.49B | $-4.19B | $3.93B | $-7.90B | $-4.10B |
Rentabilidad
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| ROA | 6.0% | 4.3% | 4.3% | 6.8% | 5.3% | 10.8% | 2.5% | 4.1% | 8.2% | · | |
| ROE | 10.5% | 7.3% | 7.3% | 11.7% | 9.4% | 20.2% | 4.8% | 7.4% | 14.6% | · |
Liquidez y Solvencia
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.1 | 1.5 | · | · | · | · | · | · | · | · | |
| Quick Ratio | 0.0 | 0.0 | · | · | · | · | · | · | · | · | |
| Interest Coverage | 11.3 | 6.8 | 6.0 | 24.2 | 22.1 | 36.3 | 7.0 | 10.7 | 13.8 | · |
Eficiencia
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Inventory Turnover | 1.3 | 1.4 | 1.5 | 1.5 | 1.4 | 1.5 | 1.5 | 1.6 | 1.7 | · |
Por Acción
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash Flow / Share | $8.77 | $7.23 | $8.16 | $8.37 | $8.36 | $5.91 | $6.16 | $4.42 | $5.82 | · | |
| EPS (TTM) | $6.37 | $4.43 | $4.30 | $6.66 | · | $9.77 | $2.23 | $3.43 | $6.64 | · |
Valoración (TTM)
| Métrica | Tendencia | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Net Income TTM | $7.81B | $5.56B | $5.40B | $8.37B | $6.22B | $12.29B | $2.75B | $4.31B | $8.42B | · | |
| P/E | 7.6 | 10.9 | 11.6 | 7.3 | · | 5.0 | 22.5 | 12.7 | 6.5 | · | |
| Earnings Yield | 13.1% | 9.2% | 8.6% | 13.8% | · | 20.1% | 4.4% | 7.9% | 15.4% | · |
Por Acción
| Métrica | Tendencia | Q4 2017 | Q4 2016 | Q4 2015 | Q4 2014 | Q4 2013 | Q4 2012 | Q4 2011 | Q4 2010 | Q4 2009 | Q4 2008 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| EPS (TTM) | $6.64 | $3.63 | $3.25 | · | · | · | · | · | · | · | · | · | · | · | · | · |
Valoración (TTM)
| Métrica | Tendencia | Q4 2017 | Q4 2016 | Q4 2015 | Q4 2014 | Q4 2013 | Q4 2012 | Q4 2011 | Q4 2010 | Q4 2009 | Q4 2008 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Net Income TTM | $8.42B | $4.71B | $4.29B | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| P/E | 6.5 | 11.1 | 13.1 | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| Earnings Yield | 15.4% | 9.0% | 7.6% | · | · | · | · | · | · | · | · | · | · | · | · | · |
Período más reciente a la izquierda · valores nulos mostrados como ·
Estados Financieros Estado de resultados, balance general, flujo de caja — anual, últimos 5 años
| Métrica | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Beneficio neto | $7.81B | $5.56B | $5.40B | $8.37B | $6.22B |
| EPS Diluido | $6.37 | $4.43 | $4.30 | $6.66 | · |
| Métrica | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Ratio corriente | 1.1 | 1.5 | · | · | · |
| Ratio Rápido | 0.0 | 0.0 | · | · | · |
Aún no hay suficientes datos fundamentales para generar este estado.
Propietarios institucionales (13F) 776 declarantes · $8.3B total · A fecha de 30 de septiembre de 2026
Instituciones que informan tener esta acción en su Formulario 13F trimestral de la SEC. Solo posiciones largas; un solo presentador puede aparecer dos veces para tramos de opciones separados. Las patas de put/call de compensación grandes suelen reflejar la creación de mercado o el inventario cubierto, no la convicción direccional.
| Nuevas posiciones | Posiciones cerradas | Aumentado | Disminuido | Cambio neto de acciones |
|---|---|---|---|---|
| 85 (-25 vs trimestre anterior) | 99 (-1 vs trimestre anterior) | 210 (-80 vs trimestre anterior) | 296 (+77 vs trimestre anterior) | -12.3M |
Comparado con Q1 2026. Las presentaciones del Formulario 13F de la SEC vencen dentro de los 45 días posteriores al final del trimestre, más un pequeño margen para los presentadores tardíos; los trimestres que aún se encuentran dentro de esa ventana se omiten en favor del par más reciente completamente reportado.
| Institución | Valor | Acciones | % de 13F rastreadas | Tipo |
|---|---|---|---|---|
| Dodge & Cox | $1 198 245 769 | 28 088 274 | 14,52% | Acciones |
| MORGAN STANLEY | $456 569 944 | 10 702 527 | 5,53% | Acciones |
| Fisher Asset Management, LLC | $453 351 578 | 10 627 088 | 5,49% | Acciones |
| BANK OF AMERICA CORP /DE/ | $341 645 673 | 8 008 572 | 4,14% | Acciones |
| Invesco Ltd. | $290 043 700 | 6 798 961 | 3,52% | Acciones |
| JPMORGAN CHASE & CO | $285 495 097 | 6 573 682 | 3,46% | Acciones |
| Mondrian Investment Partners LTD | $235 592 600 | 5 522 564 | 2,86% | Acciones |
| BRANDES INVESTMENT PARTNERS, LP | $176 460 653 | 4 136 417 | 2,14% | Acciones |
| FEDERATED HERMES, INC. | $164 232 553 | 3 849 802 | 1,99% | Acciones |
| Boston Partners | $164 041 530 | 3 844 844 | 1,99% | Acciones |
| MILLENNIUM MANAGEMENT LLC | $159 031 787 | 3 727 890 | 1,93% | Acciones |
| FMR LLC | $156 921 511 | 3 678 422 | 1,90% | Acciones |
| ENVESTNET ASSET MANAGEMENT INC | $145 160 917 | 3 402 765 | 1,76% | Acciones |
| WELLS FARGO & COMPANY/MN | $139 661 128 | 3 273 820 | 1,69% | Acciones |
| RAYMOND JAMES FINANCIAL INC | $137 058 515 | 3 212 810 | 1,66% | Acciones |
| ROYAL BANK OF CANADA | $135 265 000 | 3 170 755 | 1,64% | Acciones |
| GOLDMAN SACHS GROUP INC | $127 755 834 | 2 994 745 | 1,55% | Acciones |
| BARCLAYS PLC | $114 495 258 | 2 683 902 | 1,39% | Acciones |
| BARROW HANLEY MEWHINNEY & STRAUSS LLC | $114 370 308 | 2 680 973 | 1,39% | Acciones |
| Regal Partners Ltd | $113 218 530 | 2 653 974 | 1,37% | Acciones |
| EQUITY INVESTMENT CORP | $111 000 095 | 2 601 971 | 1,35% | Acciones |
| Balyasny Asset Management L.P. | $102 624 602 | 2 405 640 | 1,24% | Acciones |
| AMERICAN CENTURY COMPANIES INC | $94 078 141 | 2 205 301 | 1,14% | Acciones |
| LPL Financial LLC | $90 797 168 | 2 128 391 | 1,10% | Acciones |
| Alyeska Investment Group, L.P. | $90 098 432 | 2 112 012 | 1,09% | Acciones |
| DAVENPORT & Co LLC | $85 787 584 | 2 001 451 | 1,04% | Acciones |
| Vestal Point Capital, LP | $85 320 000 | 2 000 000 | 1,03% | Acciones |
| BlackRock, Inc. | $82 611 179 | 1 936 502 | 1,00% | Acciones |
| CITADEL ADVISORS LLC | $79 015 151 | 1 852 207 | 0,96% | Acciones |
| Connor, Clark & Lunn Investment Management Ltd. | $78 317 745 | 1 835 859 | 0,95% | Acciones |
| VICTORY CAPITAL MANAGEMENT INC | $77 830 111 | 1 824 428 | 0,94% | Acciones |
| UBS Group AG | $72 242 237 | 1 693 442 | 0,88% | Acciones |
| NORTHERN TRUST CORP | $72 110 075 | 1 690 344 | 0,87% | Acciones |
| Capital Research Global Investors | $71 557 841 | 1 677 399 | 0,87% | Acciones |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $60 265 782 | 1 412 700 | 0,73% | Opción de venta |
| Brandywine Global Investment Management, LLC | $58 179 671 | 1 200 571 | 0,71% | Acciones |
| MANNING & NAPIER ADVISORS LLC | $53 099 690 | 1 222 650 | 0,64% | Acciones |
| AMERIPRISE FINANCIAL INC | $46 693 947 | 1 095 251 | 0,57% | Acciones |
| ARMISTICE CAPITAL, LLC | $45 390 240 | 1 064 000 | 0,55% | Acciones |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $41 145 570 | 964 500 | 0,50% | Opción de compra |
| VAN ECK ASSOCIATES CORP | $37 413 673 | 877 020 | 0,45% | Acciones |
| Federation des caisses Desjardins du Quebec | $37 253 812 | 873 273 | 0,45% | Acciones |
| Point72 Asset Management, L.P. | $34 984 527 | 820 078 | 0,42% | Acciones |
| CAUSEWAY CAPITAL MANAGEMENT LLC | $34 301 031 | 804 056 | 0,42% | Acciones |
| STIFEL FINANCIAL CORP | $32 925 910 | 771 821 | 0,40% | Acciones |
| FIRST TRUST ADVISORS LP | $32 577 459 | 763 654 | 0,39% | Acciones |
| JANUS HENDERSON GROUP PLC | $30 940 793 | 642 277 | 0,38% | Acciones |
| Newport Trust Company, LLC | $29 705 510 | 696 331 | 0,36% | Acciones |
| TODD ASSET MANAGEMENT LLC | $28 759 321 | 674 143 | 0,35% | Acciones |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $27 204 410 | 637 703 | 0,33% | Acciones |
Activistas y propietarios del %+ 5 4 tenencias
Inversores que presentaron el Anexo 13D de la SEC — propiedad beneficiosa superior al % 5 con la intención de influir en el emisor (participaciones activistas, campañas de la junta directiva, M&A). Cada fila muestra el estado conocido más reciente de la posición de ese declarante.
| Declarante | Presentado | Participación | Estado | Propósito | Presentación |
|---|---|---|---|---|---|
| Sanofi ×3 presentaciones | 12 de agosto de 2021 | · | Presentación inicial | M&A / venta | SEC |
| SANOFI-AVENTIS, GC MERGER CORP. ×3 presentaciones | 13 de abril de 2011 | · | Presentación inicial | M&A / venta | SEC |
| Persona informante no revelada | 13 de enero de 2004 | · | Presentación inicial | Inversión pasiva | SEC |
| Persona informante no revelada | 8 de enero de 2001 | · | Presentación inicial | Inversión pasiva | SEC |
Purpose is an automated classification of the filer's own stated purpose (SEC Item 4) — not investment advice. "—" means no clear purpose was stated or the text could not be classified.
Informantes de la empresa 1 insider · 0 directivos · 0 consejeros
| Insider | Rol | Última actividad | Acciones en propiedad | Compras 12m | Ventas 12m | Neto 12m |
|---|---|---|---|---|---|---|
| Sanofi | · | 10 de agosto de 2026 C | 672 788 | 1 | 0 | $5 100 000 |
Informantes de las presentaciones SEC Form 3/4/5; neto = solo P/S de mercado abierto
Propiedad de ETFs Mantenido por 14 ETFs
El peso refleja solo las tenencias directas de acciones (N-PORT); los fondos apalancados o basados en derivados pueden tener exposición adicional a swaps no mostrada.
| Fondo | Ponderación | Unidades | A fecha de | Fuente |
|---|---|---|---|---|
| PID · Invesco Exchange-Traded Fund Trust | 3,05% | 622 913 SH | 1 de octubre de 2026 | Diario |
| IDVZ · Elevation Series Trust | 3,04% | 138 907 NS | 31 de julio de 2026 | N-PORT |
| PAYR · Federated Hermes ETF Trust | 2,91% | 38 585 NS | 31 de julio de 2026 | N-PORT |
| DIVD · EA Series Trust | 2,09% | 10 396 NS | 31 de julio de 2026 | N-PORT |
| CVGD · Elevation Series Trust | 1,92% | 61 723 NS | 31 de julio de 2026 | N-PORT |
| GENW · Spinnaker ETF Series | 1,39% | 1 651 NS | 31 de julio de 2026 | N-PORT |
| TIIV · ETF Series Solutions | 0,90% | 6 875 NS | 31 de julio de 2026 | N-PORT |
| IBBQ · Invesco Exchange-Traded Fund Trust … | 0,58% | 15 256 SH | 1 de octubre de 2026 | Diario |
| SPWO · SP Funds Trust | 0,47% | 21 903 NS | 31 de julio de 2026 | N-PORT |
| QQQJ · Invesco Exchange-Traded Fund Trust … | 0,45% | 127 313 SH | 1 de octubre de 2026 | Diario |
| DFAX · Dimensional ETF Trust | 0,00% | 3 669 NS | 31 de julio de 2026 | N-PORT |
| DFIC · Dimensional ETF Trust | 0,00% | 776 NS | 31 de julio de 2026 | N-PORT |
| DXIV · Dimensional ETF Trust | 0,00% | 8 NS | 31 de julio de 2026 | N-PORT |
| DFIV · Dimensional ETF Trust | 0,00% | 218 NS | 31 de julio de 2026 | N-PORT |
SNY Consenso de analistas Opiniones de analistas alcistas y bajistas, precio objetivo a 12 meses, potencial alcista
Precio objetivo a 12 meses
9 analistas · 2026-10-02Objetivo medio $53.72 +34,6%
Últimas noticias Noticias recientes que mencionan a esta empresa
SNY Panel de Analistas IA — Vistas alcistas y bajistas Debate de 2026Q2: Claude, Grok, Gemini, ChatGPT sobre las perspectivas de la acción
Sanofi is currently priced like a stagnant company, but the panel sees potential for a re-rating as its new drug pipeline matures. Gemini and Grok argue the stock is a bargain at 7.2 times earnings, while Claude and ChatGPT warn that regulatory pricing pressures and tightening liquidity could cap upside. The panel converged on the view that amlitelimab is the critical catalyst, though they split on whether the company's current financial health provides enough of a safety net for investors.
Ronda 1 — Primeras Opiniones
Sanofi offers a rare value play in big pharma, with rock-bottom valuation and rising profitability that could drive a sharp re-rating by mid-2026 if the drug pipeline converts. Its TTM P/E sits at just 7.25, meaning investors pay pennies on the dollar for every bit of earnings despite stable 20.7% net margins that prove pricing power holds up. ROE has climbed to 18.8%, signaling management squeezes more profit from each dollar of equity than in prior quarters. Positive Phase 3 data for amlitelimab in atopic dermatitis as of March 28 adds a high-conviction catalyst.
Sanofi's downtrend signals fading momentum and potential trouble ahead, breaking lower without signs of stabilization into 2026Q2. Shares have shed 12% from 55.44 in early May to 48.61 now, with volume spiking on the downside to reflect real selling pressure. Current ratio has slipped to 1.06, dipping toward liquidity stress that could force tough choices if working capital tightens further. Flat market cap around $100 billion masks stagnant growth amid peers.
Sanofi is trading at a valuation that assumes the company is broken, but the fundamentals suggest it is healing. The P/E of 7.2 is a full third below the pharma median, yet EPS grew 26% year-over-year and ROE climbed to 18.8%, signaling genuine operational leverage. The Phase 3 win in amlitelimab for atopic dermatitis (announced March 28) opens a new revenue stream in a large immunology market. If the market reprices this stock to reflect normalized pharma multiples—say 12 to 14 times earnings—the upside is substantial without requiring heroic assumptions.
Sanofi's cheap valuation may be cheap for a reason: the company is trapped in a slow-growth, high-leverage trap. Debt-to-equity of 29.7% is manageable but rising relative to cash generation, and the current ratio of 1.06 leaves almost no margin for error if cash flow stumbles. The stock has fallen 8% in six weeks despite the amlitelimab news, suggesting the market is unconvinced the pipeline can offset patent cliffs and generic competition. Without evidence that revenue growth is accelerating—not just earnings per share through buybacks—this looks like a value trap, not a bargain.
Sanofi is currently priced like a stagnant utility despite a pipeline that suggests significant growth potential. The market is currently valuing the company at just 7.24 times trailing earnings. This low multiple implies that investors expect no future growth, which ignores the recent positive Phase 3 results for amlitelimab. Furthermore, the company maintains a robust 72.29% gross margin. This high margin indicates that Sanofi retains significant pricing power on its core drug portfolio, providing a solid cushion to fund the R&D necessary to bring new blockbusters like amlitelimab to market.
The company’s liquidity profile is tightening, which could limit its flexibility to navigate competitive pharmaceutical headwinds. The current ratio has slipped to 1.06. This means the company has barely enough short-term assets to cover its immediate liabilities, leaving little room for operational error. Additionally, the stock has struggled to find momentum, hovering near its 52-week lows. This price action suggests that the market remains skeptical of the company's ability to offset expiring drug patents, keeping a lid on any potential valuation expansion regardless of recent clinical trial successes.
I think the strongest bullish case for SNY is that Sanofi trades cheaply and has a clear near-term catalyst from amlitelimab Phase 3 results. P/E TTM: 7.25. This low multiple implies the market hasn't priced in strong growth; upside hinges on resilient earnings and amlitelimab translating into sales. EPS TTM: 11.20. This level signals solid profitability and cash generation to fund pipelines and shareholder returns. ROE TTM: 18.76%. This indicates efficient use of equity and pricing power, supporting per-share value in a steady growth scenario. News: On 2026-03-28, Sanofi reported positive Phase 3 results for amlitelimab, a potential growth driver.
The stock faces downside risk from growth concerns and potential pipeline underdelivery. P/E TTM: 7.25. This low multiple may reflect growth anxiety; any pipeline miss or competition could compress the multiple further. Current ratio: 1.0603. This near-breakeven liquidity puts stress on working capital in a tougher macro backdrop. Debt/Equity: 29.69. With rates rising, debt service could squeeze cash flow and cap buybacks or dividends.
Ronda 2 — Respuestas y refutaciones
Ronda 2 — Respuestas y refutaciones
Claude, your bear case claims debt-to-equity is rising relative to cash generation, but it's actually down to 29.7 from 31.8 last quarter. That deleveraging eases interest burdens and boosts flexibility to invest in pipeline wins like amlitelimab, turning a perceived trap into tailwind for earnings growth. This reinforces why the 7.2 P/E looks like a mispricing, not a warning.
I need to push back on Grok's read of the price action. Yes, SNY is down 12% from May's peak to 48.61 now, but that's noise against a backdrop where the stock has been range-bound between 47 and 51 for the past eight weeks. Grok frames this as 'fading momentum' and 'breaking lower,' but the volume data tells a different story — the 12.5M shares that moved on the June 20 selloff haven't repeated. That's not capitulation; that's consolidation. The real question isn't whether the stock is trending down; it's whether the market is waiting for amlitelimab label expansion or revenue guidance before it reprices. That's a timing call, not a momentum call.
Claude, your focus on the debt-to-equity ratio as a major headwind for Sanofi misses the broader context of their capital efficiency. A debt-to-equity ratio of 29.69 is actually quite conservative for a pharmaceutical giant with this level of cash flow. This means the company is not overly reliant on borrowed money to fund its operations or its pipeline development. While you worry about the leverage trap, I see a balance sheet that is actually well-positioned to aggressively commercialize the amlitelimab breakthrough without needing to take on dangerous levels of new debt.
Claude, your point about a re-rating to a higher multiple hinges on AMLI delivering durable revenue; I think that's a big conditional. P/E TTM is 7.25. That suggests the market is already pricing Sanofi as a slow-grower, and any meaningful upside will depend on AMLI actually translating into revenue and on pipeline risk materializing, rather than on hope or a one-off buyback.
Ronda 3 — Refutaciones finales
Ronda 3 — Refutaciones finales
Gemini, I'm fully with you on debt-to-equity — Claude's claim it's rising relative to cash generation doesn't match the data. It fell from 31.8 in 2025Q3 to 29.7 now. Lower leverage shrinks interest expenses, giving Sanofi more firepower to commercialize amlitelimab and sustain high ROE without dilution risks. That's no trap; it's tailwind for 2026 earnings.
I want to push back on Gemini's framing of the debt-to-equity ratio. Gemini, you're right that 29.7% is conservative in absolute terms, but you're missing the direction. Debt-to-equity fell from 31.8% last quarter, which Grok correctly flagged — that's deleveraging, and I was wrong to call it a trap. But here's what neither of you addressed: the current ratio dropped from 1.27 to 1.06 in the same window. That's not just tightening; that's a 17% compression in working capital cushion while the company is supposedly in growth mode. If amlitelimab requires upfront commercialization spend before revenue hits, Sanofi may face a cash flow timing crunch in late 2026. That's the real liquidity risk, not the leverage itself.
I want to widen the frame to address the macro regime, specifically the USD strength that Claude and Grok have overlooked. Sanofi is a French company reporting in Euros but trading as an ADS in New York, meaning a strong dollar acts as a structural headwind for their translated earnings. With a net profit margin of 20.66%, any further appreciation of the greenback will mechanically erode the bottom line for US-based investors. Even if the pipeline succeeds, the currency tailwind is currently working against us, which explains why the stock is range-bound despite the positive clinical data.
I think the biggest swing factor for SNY into 2026Q2 is regulatory and macro policy, not just pipeline chatter from amlitelimab. Grok, your focus on the valuation is useful, but P/E around 7.3 signals the market isn’t pricing growth and policy shifts could re-rate the stock. Look at US price negotiation under the Inflation Reduction Act starting 2026 and EU reference pricing; those policies could cap margins on major franchises even if AMLI lands, so the stock’s upside hinges on policy clarity as much as science.
Pronósticos de Precios
| Modelo | Objetivo a 3M | Objetivo a 6M | Razonamiento |
|---|---|---|---|
| Grok | $55.00 | $62.00 | I see Sanofi's rock-bottom valuation expanding toward pharma peers as amlitelimab de-risks and deleveraging frees up cash for growth. My key catalyst is the Q2 2026 earnings release in late July, where Sanofi should quantify amlitelimab's peak sales potential and commercialization spend. The top risk is Inflation Reduction Act price controls hitting key franchises from mid-2026, crimping margins as ChatGPT flagged. A P/E re-rating to 10x TTM earnings—signaling the market credits pipeline offset to patent losses—implies $60+ fairly soon, justifying my buy call from the current 48.61 close. |
| Claude | $54.50 | $58.75 | Sanofi is repricing from a valuation floor to fair value as the market digests that deleveraging and rising ROE signal genuine operational healing, not financial engineering. The single catalyst that moves this stock is amlitelimab's label expansion timeline — if Sanofi guides to 2026 launch and early peak-sales estimates in Q2 earnings, the market reprices from 7.2x to 10–11x earnings, a 40% re-rating. The risk is that IRA price negotiation or EU reference pricing caps margins faster than amlitelimab offsets patent cliff losses, collapsing the multiple back down. At 7.2 times trailing earnings of 11.20, the market is pricing zero growth; even 3% organic growth justifies 10x, worth 56 dollars per share from current 52.32. |
| Gemini | $54.50 | $58.00 | I believe Sanofi is currently mispriced as a terminal decline story, and the market will eventually reward its deleveraging and clear pipeline progress with a modest valuation expansion. The primary catalyst for my 6-month target is the Q3 2026 earnings release, where I expect management to provide concrete revenue guidance for the amlitelimab commercial rollout. A major risk remains the potential for unfavorable regulatory pricing adjustments in the US market, which could compress margins. The company's current P/E of 7.25 is extremely low, meaning the market is paying almost nothing for future growth, which provides a significant floor for the stock price if these clinical successes translate into actual cash flow. |
| Chatgpt | $56.00 | $64.00 | I think SNY can grind higher as amlitelimab delivers revenue and the stock begins to re-rate from its cheap base. Catalyst: durable AMLI revenue realization and a positive guidance update tied to near-term commercialization. Risk: policy headwinds from US IRA price negotiation and EU pricing that could cap margins. At 52.32 now, a path to 56 in 3 months and 64 in 6 months would imply a modest re-rate on AMLI upside. |
Señales de trading Señales recientes de compra/venta con precio de entrada y ratio riesgo/recompensa
Ninguna señal abierta en este momento — ninguna tarjeta está completada, y eso es honesto.
Mis Métricas Tu lista de seguimiento personal — filas seleccionadas de Fundamentales Completos
Seleccione las métricas que le importan: haga clic en el + junto a cualquier fila en Fundamentales completos arriba.
Tu selección se guarda y te sigue en todos los tickers.