NFLX Netflix, Inc. - Common Stock
NASDAQ · Media · Voir sur SEC EDGAR ↗ clôture Oct 2, 2026 10-K/10-Q Jul 17, 2026NFLX Aperçu de l'action Prix, capitalisation boursière, P/E, EPS, ROE, dette/capitaux propres, fourchette sur 52 semaines
NFLX Graphique du cours de l'action OHLCV quotidien avec indicateurs techniques — panoramique, zoom et personnalisez votre vue
La granularité des barres s'adapte à la période sélectionnée — survolez le graphique pour voir l'ouverture/le maximum/le minimum/la clôture d'une barre.
| Date ex-dividende | Division | Type |
|---|---|---|
| 17 novembre 2025 | 10-for-1 | Avant |
| 15 juillet 2015 | 7-for-1 | Avant |
| 12 février 2004 | 2-for-1 | Avant |
À propos de Netflix, Inc. - Common Stock Présentation de l'entreprise depuis Wikipedia
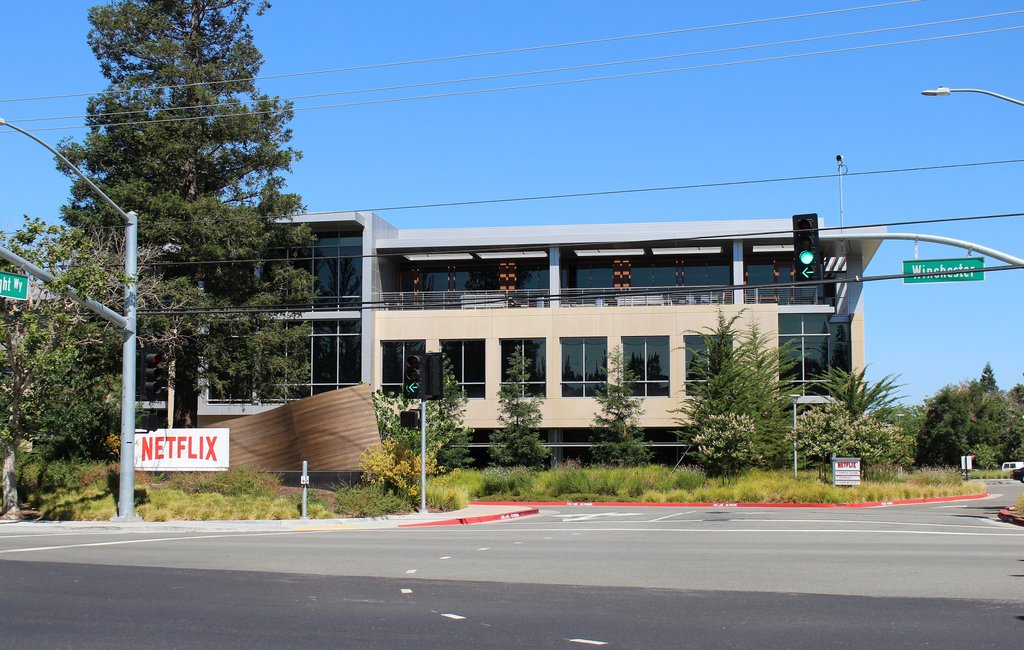
Netflix, Inc. is an American media company founded on August 29, 1997, by Reed Hastings and Marc Randolph in Scotts Valley, California, and currently based in Los Gatos, California, with production offices and stages at the Los Angeles–based Hollywood studios (formerly old Warner Brothers studios) and the Albuquerque Studios (formerly ABQ studios). It owns and operates an eponymous over-the-top subscription video on-demand service, which showcases acquired and original programming as well as third-party content licensed from other production companies and distributors. Netflix is also the first streaming media company to be a member of the Motion Picture Association.
Netflix initially both sold and rented DVDs by mail, but the sales were eliminated within a year to focus on the DVD rental business. In 2007, Netflix introduced streaming media and video on demand. The company expanded to Canada in 2010, followed by Latin America and the Caribbean. In 2011, the service began to acquire and produce original content, beginning with the crime drama Lilyhammer.
The company has been listed on Nasdaq since 2002 and is ranked 117th on the Fortune 500 and 219th on the Forbes Global 2000. It is the largest entertainment/media company by market capitalization as of 2026 estimated at $450 billion. In 2021, Netflix was ranked as the eighth-most trusted brand globally by Morning Consult. During the 2010s, Netflix was the top-performing stock in the S&P 500 stock market index, with a total return of 3,693%.
The company has two CEOs, Greg Peters and Ted Sarandos, who are split between Los Gatos and Los Angeles, respectively. It also operates international offices in Asia, Europe and Latin America including in Canada, France, Brazil, the Netherlands, India, Italy, Japan, Poland, South Korea, and the United Kingdom. The company has production hubs in Los Angeles, Albuquerque, London, Madrid, Vancouver and Toronto.
History
Launch as a mail-based rental business (1997–2006)
Netflix was founded by Marc Randolph and Reed Hastings on August 29, 1997, in Scotts Valley, California. Hastings, a computer scientist and mathematician, was a cofounder of Pure Software, which was acquired by Rational Software that year for $750 million, the then biggest acquisition in Silicon Valley history. Randolph had worked as a marketing director for Pure Software after Pure Atria acquired a company where Randolph worked. He was previously a co-founder of MicroWarehouse, a computer mail-order company as well as vice president of marketing for Borland. Hastings and Randolph came up with the idea for Netflix while carpooling between their homes in Santa Cruz, California, and Pure Atria's headquarters in Sunnyvale. Patty McCord, later head of human resources at Netflix, was also in the carpool group. Randolph admired Amazon and wanted to find a large category of portable items to sell over the Internet using a similar model. Hastings and Randolph considered and rejected selling and renting VHS as too expensive to stock and too delicate to ship. When they heard about DVDs, first introduced in the United States in early 1997, they tested the concept of selling or renting DVDs by mail by mailing a compact disc to Hastings's house in Santa Cruz. When the disc arrived intact, they decided to enter the $16 billion home video sales and rental industry. Hastings is often quoted saying that he decided to start Netflix after being fined $40 at a Blockbuster store for being late to return a copy of Apollo 13, a claim since repudiated by Randolph. Hastings invested $2.5 million into Netflix from the sale of Pure Atria. Netflix launched as the first DVD rental and sales website with 30 employees and 925 titles available—nearly all DVDs published. Randolph and Hastings met with Jeff Bezos, where Amazon offered to acquire Netflix for between $14 and $16 million. Fearing competition from Amazon, Randolph at first thought the offer was fair, but Hastings, who owned 70% of the company, turned it down on the plane ride home.
Initially, Netflix offered a per-rental model for each DVD but introduced a monthly subscription concept in September 1999. The per-rental model was dropped by early 2000, allowing the company to focus on the business model of flat-fee unlimited rentals without due dates, late fees, shipping and handling fees, or per-title rental fees. In September 2000, during the dot-com bubble, while Netflix was suffering losses, Hastings and Randolph offered to sell the company to Blockbuster for $50 million. John Antioco, CEO of Blockbuster, thought the offer was a joke and declined, saying, "The dot-com hysteria is completely overblown." While Netflix experienced fast growth in early 2001, the continued effects of the dot-com bubble collapse and the September 11 attacks caused the company to hold off plans for its initial public offering (IPO) and to lay off one-third of its 120 employees.
DVD players were a popular gift for holiday sales in late 2001, and demand for DVD subscription services were "growing like crazy", according to chief talent officer Patty McCord. The company went public on NASDAQ under the ticker symbol NFLX on May 29, 2002, selling 5.5 million shares of common stock at US$15.00 per share. In 2003, Netflix was issued a patent by the U.S. Patent and Trademark Office to cover its subscription rental service and several extensions. Netflix posted its first profit in 2003, earning $6.5 million on revenues of $272 million; by 2004, profit had increased to $49 million on over $500 million in revenues. In 2005, 35,000 different films were available, and Netflix shipped 1 million DVDs out every day.
In 2004, Blockbuster introduced a DVD rental service, which not only allowed users to check out titles through online sites but allowed for them to return them at brick and-mortar stores. By 2006, Blockbuster's service reached two million users, and while trailing Netflix's subscriber count, was drawing business away from Netflix. Netflix lowered fees in 2007. While it was an urban legend that Netflix ultimately "killed" Blockbuster in the DVD rental market, Blockbuster's debt load and internal disagreements hurt the company.
On April 4, 2006, Netflix filed a patent infringement lawsuit in which it demanded a jury trial in the U.S. District Court for the Northern District of California, alleging that Blockbuster's online DVD rental subscription program violated two patents held by Netflix. The first cause of action alleged Blockbuster's infringement of copying the "dynamic queue" of DVDs available for each customer, Netflix's method of using the ranked preferences in the queue to send DVDs to subscribers, and Netflix's method permitting the queue to be updated and reordered. The second cause of action alleged infringement of the subscription rental service as well as Netflix's methods of communication and delivery. The companies settled their dispute on June 25, 2007; terms were not disclosed.
On October 1, 2006, Netflix announced the Netflix Prize, $1,000,000 to the first developer of a video recommendation algorithm that could beat its existing algorithm Cinematch, at predicting customer ratings by more than 10%. On September 21, 2009, it awarded the $1,000,000 prize to team "BellKor's Pragmatic Chaos". Cinematch, launched in 2000, is a recommendation system that recommended movies to its users, many of which they might not ever had heard of before.
Through its division Red Envelope Entertainment, Netflix licensed and distributed independent films such as Born into Brothels and Sherrybaby. In late 2006, Red Envelope Entertainment also expanded into producing original content with filmmakers such as John Waters. Netflix closed Red Envelope Entertainment in 2008.
Transition to streaming services (2007–2012)
In January 2007, the company launched a streaming media service, introducing video on demand via the Internet. However, at that time it only had 1,000 films available for streaming, compared to 70,000 available on DVD. The company had for some time considered offering movies online, but it was only in the mid-2000s that data speeds and bandwidth costs had improved sufficiently to allow customers to download movies from the net. The original idea was a "Netflix box" that could download movies overnight, and be ready to watch the next day. By 2005, Netflix had acquired movie rights and designed the box and service. But after witnessing how popular streaming services such as YouTube were despite the lack of high-definition content, the concept of using a hardware device was scrapped and replaced with a streaming concept.
In February 2007, Netflix delivered its billionth DVD, a copy of Babel to a customer in Texas. In April 2007, Netflix recruited ReplayTV founder Anthony Wood, to build a "Netflix Player" that would allow streaming content to be played directly on a television rather than a desktop or laptop. Hastings eventually shut down the project to help encourage other hardware manufacturers to include built-in Netflix support, which would be spun off as the digital media player product Roku.
In January 2008, all rental-disc subscribers became entitled to unlimited streaming at no additional cost. This change came in a response to the introduction of Hulu and to Apple's new video-rental services. In August 2008, the Netflix database was corrupted and the company was not able to ship DVDs to customers for 3 days, leading the company to move all its data to the Amazon Web Services cloud. In November 2008, Netflix began offering subscribers rentals on Blu-ray and discontinued its sale of used DVDs. In 2009, Netflix streams overtook DVD shipments.
On January 6, 2010, Netflix agreed with Warner Bros. to delay new release rentals 28 days prior to retail, in an attempt to help studios sell physical copies, and similar deals involving Universal Pictures and 20th Century Fox were reached on April 9. In July 2010, Netflix signed a deal to stream movies of Relativity Media. In August 2010, Netflix reached a five-year deal worth nearly $1 billion to stream films from Paramount, Lionsgate and Metro-Goldwyn-Mayer. The deal increased Netflix's annual spending fees, adding roughly $200 million per year. It spent $117 million in the first six months of 2010 on streaming, up from $31 million in 2009. On September 22, 2010, Netflix launched in Canada, its first international market. In November 2010, Netflix began offering a standalone streaming service separate from DVD rentals.
In 2010, Netflix acquired the rights to Breaking Bad, produced by Sony Pictures Television, after the show's third season, at a point where original broadcaster AMC had expressed the possibility of cancelling the show. Sony pushed Netflix to release Breaking Bad in time for the fourth season, which as a result greatly expanded the show's audience on AMC due to new viewers binging on the Netflix past episodes, and doubling the viewership by the time of the fifth season. Breaking Bad is considered the first such show to have this "Netflix effect".
In January 2011, Netflix announced agreements with several manufacturers to include branded Netflix buttons on the remote controls of devices compatible with the service, such as Blu-ray players. By May 2011, Netflix had become the largest source of Internet streaming traffic in North America, accounting for 30% of traffic during peak hours.
On July 12, 2011, Netflix announced that it would separate its existing subscription plans into two separate plans: one covering the streaming and the other DVD rental services. The cost for streaming would be $7.99 per month, while DVD rental would start at the same price. On September 11, 2011, Netflix expanded to 43 countries in Latin America. On September 18, 2011, Netflix announced its intentions to rebrand and restructure its DVD home media rental service as an independent subsidiary called Qwikster, separating DVD rental and streaming services. On September 26, 2011, Netflix announced a content deal with DreamWorks Animation. On October 10, 2011, Netflix announced that it would retain its DVD service under the name Netflix and that its streaming and DVD-rental plans would remain branded together.
On January 9, 2012, Netflix started its expansion to Europe, launching in the United Kingdom and Ireland. In February 2012, Netflix reached a multi-year agreement with The Weinstein Company. In March 2012, Netflix acquired the domain name DVD.com. By 2016, Netflix rebranded its DVD-by-mail service under the name DVD.com, A Netflix Company. In April 2012, Netflix filed with the Federal Election Commission (FEC) to form a political action committee (PAC) called FLIXPAC. Netflix spokesperson Joris Evers tweeted that the intent was to "engage on issues like net neutrality, bandwidth caps, UBB and VPPA". In June 2012, Netflix signed a deal with Open Road Films.
On August 23, 2012, Netflix and The Weinstein Company signed a multi-year output deal for RADiUS-TWC films. In August 2010, Epix signed a five-year streaming deal with Netflix. For the initial two years of this agreement, first-run and back-catalog content from Epix was exclusive to Netflix. Epix films came to Netflix 90 days after premiering on Epix. These included films from Paramount, Metro-Goldwyn-Mayer and Lionsgate.
On October 18, 2012, Netflix launched in Denmark, Finland, Norway and Sweden. On December 4, 2012, Netflix and Disney announced an exclusive multi-year agreement for first-run United States subscription television rights to Walt Disney Studios' animated and live-action films, with classics such as Dumbo, Alice in Wonderland and Pocahontas available immediately and others available on Netflix beginning in 2016. Direct-to-video releases were made available in 2013.
On January 14, 2013, Netflix signed an agreement with Time Warner's Turner Broadcasting System and Warner Bros. Television to distribute Cartoon Network, Warner Bros. Animation, and Adult Swim content, as well as TNT's Dallas, beginning in March 2013. The rights to these programs were given to Netflix shortly after deals with Viacom to stream Nickelodeon and Nick Jr. Channel programs expired.
For cost reasons, Netflix stated that it would limit its expansion in 2013, adding only one new market—the Netherlands—in September of that year. This expanded its availability to 40 territories.
Development of original programming (2013–2017)
Netflix began efforts to develop original content in 2011; in March, Netflix made a straight-to-series order for the Kevin Spacey-led political drama House of Cards from MRC. Beating out other U.S. cable networks, it marked the first first-run television series to be specifically commissioned by the service. In November 2011, Netflix then ordered Orange is the New Black, a comedy-drama adapted from Piper Kerman's memoir of the same name, and a new season of the cancelled Fox sitcom Arrested Development. Netflix also acquired U.S. rights to the Norwegian drama Lilyhammer; following its television premiere on Norway's NRK1 on January 25, 2012, the entirety of its first season was released by Netflix on February 8—a notable departure from the broadcast television model of premiering episodes on a weekly basis.
House of Cards was released by Netflix on February 1, 2013, marketed as the first "Netflix Original" production. Later that month, Netflix announced an agreement with DreamWorks Animation to commission children's television series based on its properties, beginning with Turbo: F.A.S.T., a spin-off of its film Turbo. Orange is the New Black would premiere in July 2013; Netflix stated that Orange is the New Black had been its most-watched original series so far, with all of them having "an audience comparable with successful shows on cable and broadcast TV."
On March 13, 2013, Netflix added a Facebook sharing feature, letting United States subscribers access "Watched by your friends" and "Friends' Favorites" by agreeing. This was not legal until the Video Privacy Protection Act was modified in early 2013. On August 1, 2013, Netflix reintroduced the "Profiles" feature that permits accounts to accommodate up to five user profiles.
In November 2013, Marvel Television and ABC Studios announced Netflix had ordered a slate of four television series based on the Marvel Comics characters Daredevil, Jessica Jones, Iron Fist and Luke Cage. Each of the four series received an initial order of 13 episodes, and Netflix also ordered a Defenders miniseries that would tie them together. Daredevil and Jessica Jones premiered in 2015. The Luke Cage series premiered on September 30, 2016, followed by Iron Fist on March 17, 2017, and The Defenders on August 18, 2017. Marvel owner Disney later entered into other content agreements with Netflix, including acquiring its animated Star Wars series Star Wars: The Clone Wars, and a new sixth season.
In February 2014, Netflix began to enter into agreements with U.S. internet service providers, beginning with Comcast (whose customers had repeatedly complained of frequent buffering when streaming Netflix), to provide the service a direct connection to their networks. In April 2014, Netflix signed Arrested Development creator Mitchell Hurwitz and his production firm The Hurwitz Company to a multi-year deal to create original projects for the service. In May 2014, Netflix acquired streaming rights to films produced by Sony Pictures Animation. It also quietly began to introduce an updated logo, with a flatter appearance and updated typography.
In September 2014, Netflix expanded into six new European markets, including Austria, Belgium, France, Germany, Luxembourg, and Switzerland. On September 10, 2014, Netflix participated in Internet Slowdown Day by deliberately slowing down its speed in support of net neutrality regulations in the United States. In October 2014, Netflix announced a four-film deal with Adam Sandler and his Happy Madison Productions.
In April 2015, following the launch of Daredevil, Netflix director of content operations Tracy Wright announced that Netflix had added support for audio description (a narration track with aural descriptions of key visual elements for the blind or visually impaired), and had begun to work with its partners to add descriptions to its other original series over time. The following year, as part of a settlement with the American Council of the Blind, Netflix agreed to provide descriptions for its original series within 30 days of their premiere, and add screen reader support and the ability to browse content by availability of descriptions.
In March 2015, Netflix expanded to Australia and New Zealand. In September 2015, Netflix launched in Japan, its first country in Asia. In October 2015, Netflix launched in Italy, Portugal, and Spain.
In January 2016, at the Consumer Electronics Show, Netflix announced a major international expansion of its service into 130 additional countries. It then had become available worldwide except China, Syria, North Korea, Kosovo and Crimea. In May 2016, Netflix created a tool called Fast.com to determine the speed of an Internet connection. It received praise for being "simple" and "easy to use", and does not include online advertising, unlike competitors. On November 30, 2016, Netflix launched an offline playback feature, allowing users of the Netflix mobile apps on Android or iOS to cache content on their devices in standard or high quality for viewing offline, without an Internet connection.
In 2016, Netflix released an estimated 126 original series or films, more than any other network or cable channel. In April 2016, Hastings stated that the company planned to expand its in-house, Los Angeles-based Netflix Studios to grow its output; Hastings ruled out any potential acquisitions of existing studios, stating that "It's been 15 years we've been public and 20 years existing, and we've done no [mergers and acquisitions]. So I think that probably speaks for itself."
In February 2017, Netflix signed a music publishing deal with BMG Rights Management, whereby BMG will oversee rights outside of the United States for music associated with Netflix original content. Netflix continues to handle these tasks in-house in the United States. On April 25, 2017, Netflix signed a licensing deal with IQiyi, a Chinese video streaming platform owned by Baidu, to allow selected Netflix original content to be distributed in China on the platform.
On August 7, 2017, Netflix acquired Millarworld, the creator-owned publishing company of comic book writer Mark Millar. The purchase marked the first corporate acquisition to have been made by Netflix. On August 14, 2017, Netflix entered into an exclusive development deal with Shonda Rhimes and her production company Shondaland.
In September 2017, Netflix announced it would offer its low-broadband mobile technology to airlines to provide better in-flight Wi-Fi so that passengers can watch movies on Netflix while on planes.
In September 2017, Minister of Heritage Mélanie Joly announced that Netflix had agreed to make a CA$500 million (US$400 million) investment over the next five years in producing content in Canada. The company denied that the deal was intended to result in a tax break. Netflix realized this goal by December 2018.
In October 2017, Netflix iterated a goal of having half of its library consist of original content by 2019, announcing a plan to invest $8 billion on original content in 2018. There will be a particular focus on films and anime through this investment, with a plan to produce 80 original films and 30 anime series. In October 2017, Netflix introduced the "Skip Intro" feature which allows customers to skip the intros to shows on its platform through a variety of techniques including manual reviewing, audio tagging, and machine learning.
In November 2017, Netflix signed an exclusive multi-year deal with Orange Is the New Black creator Jenji Kohan. In November 2017, Netflix withdrew from co-hosting a party at the 75th Golden Globe Awards with The Weinstein Company due to the Harvey Weinstein sexual abuse cases.
Expansion into international productions (2017–2020)
In November 2017, Netflix announced that it would be making its first original Colombian series, to be executive produced by Ciro Guerra. In December 2017, Netflix signed Stranger Things director-producer Shawn Levy and his production company 21 Laps Entertainment to what sources say is a four-year deal. In 2017, Netflix invested in distributing exclusive stand-up comedy specials from Dave Chappelle, Louis C.K., Chris Rock, Jim Gaffigan, Bill Burr and Jerry Seinfeld.
In February 2018, Netflix acquired the rights to The Cloverfield Paradox from Paramount Pictures for $50 million and launched on its service on February 4, 2018, shortly after airing its first trailer during Super Bowl LII. Analysts believed that Netflix's purchase of the film helped to make the film instantly profitable for Paramount compared to a more traditional theatrical release, while Netflix benefited from the surprise reveal. Other films acquired by Netflix include international distribution for Paramount's Annihilation and Universal's News of the World and worldwide distribution of Universal's Extinction, Warner Bros.' Mowgli: Legend of the Jungle, Paramount's The Lovebirds and 20th Century Studios' The Woman in the Window. In March, the service ordered Formula 1: Drive to Survive, a racing docuseries following teams in the Formula One world championship.
In March 2018, Sky UK announced an agreement with Netflix to integrate Netflix's subscription VOD offering into its pay-TV service. Customers with its high-end Sky Q set-top box and service will be able to see Netflix titles alongside their regular Sky channels. In October 2022, Netflix revealed that its annual revenue from the UK subscribers in 2021 was £1.4bn.
In April 2018, Netflix pulled out of the Cannes Film Festival, in response to new rules requiring competition films to have been released in French theaters. The Cannes premiere of Okja in 2017 was controversial, and led to discussions over the appropriateness of films with simultaneous digital releases being screened at an event showcasing theatrical film; audience members also booed the Netflix production logo at the screening. Netflix's attempts to negotiate to allow a limited release in France were curtailed by organizers, as well as French cultural exception law—where theatrically screened films are legally forbidden from being made available via video-on-demand services until at least 36 months after their release. Besides traditional Hollywood markets as well as from partners like the BBC, Sarandos said the company also looking to expand investments in non-traditional foreign markets due to the growth of viewers outside of North America. At the time, this included programs such as Dark from Germany, Ingobernable from Mexico and 3% from Brazil.
On May 22, 2018, former president, Barack Obama, and his wife, Michelle Obama, signed a deal to produce docu-series, documentaries and features for Netflix under the Obamas' newly formed production company, Higher Ground Productions.
In June 2018, Netflix announced a partnership with Telltale Games to port its adventure games to the service in a streaming video format, allowing simple controls through a television remote. The first game, Minecraft: Story Mode, was released in November 2018. In July 2018, Netflix earned the most Emmy nominations of any network for the first time with 112 nods. On August 27, 2018, the company signed a five-year exclusive overall deal with international best–selling author Harlan Coben. On the same day, the company inked an overall deal with Gravity Falls creator Alex Hirsch. In October 2018, Netflix paid under $30 million to acquire Albuquerque Studios (ABQ Studios), a $91 million film and TV production facility with eight sound stages in Albuquerque, New Mexico, for its first U.S. production hub, pledging to spend over $1 billion over the next decade to create one of the largest film studios in North America. In November 2018, Paramount Pictures signed a multi-picture film deal with Netflix, making Paramount the first major film studio to sign a deal with Netflix. A sequel to AwesomenessTV's To All the Boys I've Loved Before was released on Netflix under the title To All the Boys: P.S. I Still Love You as part of the agreement. In December 2018, the company announced a partnership with ESPN Films on a television documentary chronicling Michael Jordan and the 1997–98 Chicago Bulls season titled The Last Dance. It was released internationally on Netflix and became available for streaming in the United States three months after a broadcast airing on ESPN.
In January 2019, Sex Education made its debut as a Netflix original series with much critical acclaim. On January 22, 2019, Netflix sought and was approved for membership into the Motion Picture Association of America (MPAA), as the first streaming service to become a member of the association. In February 2019, The Haunting creator Mike Flanagan joined frequent collaborator Trevor Macy as a partner in Intrepid Pictures and the duo signed an exclusive overall deal with Netflix to produce television content. On May 9, 2019, Netflix contracted with Dark Horse Entertainment to make television series and films based on comics from Dark Horse Comics. In July 2019, Netflix announced that it would be opening a hub at Shepperton Studios as part of a deal with Pinewood Group. In early-August 2019, Netflix negotiated an exclusive multi-year film and television deal with Game of Thrones creators and showrunners David Benioff and D.B. Weiss. The first Netflix production created by Benioff and Weiss was planned as an adaptation of Liu Cixin's science fiction novel The Three-Body Problem, part of the Remembrance of Earth's Past trilogy. On September 30, 2019, in addition to renewing Stranger Things for a fourth season, Netflix signed The Duffer Brothers to an overall deal covering future film and television projects for the service.
On November 13, 2019, Netflix and Nickelodeon entered into a multi-year agreement to produce several original animated feature films and television series based on Nickelodeon's library of characters. This agreement expanded on their existing relationship, in which new specials based on the past Nickelodeon series Invader Zim and Rocko's Modern Life (Invader Zim: Enter the Florpus and Rocko's Modern Life: Static Cling respectively) were released by Netflix. Other new projects planned under the team-up include a music project featuring Squidward Tentacles from the animated television series SpongeBob SquarePants, and films based on The Loud House and Rise of the Teenage Mutant Ninja Turtles. The agreement with Disney ended in 2019 due to the launch of Disney+, with its Marvel productions moving exclusively to the service in 2022.
In November 2019, Netflix announced that it had signed a long-term lease to save the Paris Theatre, the last single-screen movie theater in Manhattan. The company oversaw several renovations at the theater, including new seats and a concession stand.
In January 2020, Netflix announced a new four-film deal with Adam Sandler worth up to $275 million. On February 25, 2020, Netflix formed partnerships with six Japanese creators to produce an original Japanese anime project. This partnership includes manga creator group CLAMP, mangaka Shin Kibayashi, mangaka Yasuo Ohtagaki, novelist and film director Otsuichi, novelist Tow Ubukata, and manga creator Mari Yamazaki. On March 4, 2020, ViacomCBS announced that it will be producing two spin-off films based on SpongeBob SquarePants for Netflix. On April 7, 2020, Peter Chernin's Chernin Entertainment made a multi-year first-look deal with Netflix to make films. On May 29, 2020, Netflix announced the acquisition of Grauman's Egyptian Theatre from the American Cinematheque to use as a special events venue. In July 2020, Netflix appointed Sarandos as co-CEO. In July 2020, Netflix invested in Black Mirror creators Charlie Brooker and Annabel Jones' new production outfit Broke And Bones.
Expansion into gaming, end of DVDs, etc. (2021–2025)
In March 2021, Netflix earned the most Academy Award nominations of any studio, with 36. Netflix won seven Academy Awards, which was the most by any studio. Later that year, Netflix also won more Emmys than any other network or studio with 44 wins, tying the record for most Emmys won in a single year set by CBS in 1974. On April 8, 2021, Sony Pictures Entertainment announced an agreement for Netflix to hold the U.S. pay television window rights to its releases beginning in 2022, replacing Starz and expanding upon an existing agreement with Sony Pictures Animation. The agreement also includes a first-look deal for any future direct-to-streaming films being produced by Sony Pictures, with Netflix required to commit to a minimum number of them. On April 27, 2021, Netflix announced that it was opening its first Canadian headquarters in Toronto. The company also announced that it would open an office in Sweden as well as Rome and Istanbul to increase its original content in those regions.
In early-June, Netflix hosted a first-ever week-long virtual event called "Geeked Week", where it shared exclusive news, new trailers, cast appearances and more about upcoming genre titles like The Witcher, The Cuphead Show!, and The Sandman.
In July 2021, Netflix hired Mike Verdu, a former executive from Electronic Arts and Facebook, as vice president of game development, along with plans to add video games by 2022. Netflix announced plans to release mobile games which would be included in subscribers' plans to the service. Trial offerings were first launched for Netflix users in Poland in August 2021, offering premium mobile games based on Stranger Things including Stranger Things 3: The Game, for free to subscribers through the Netflix mobile app.
Also in September, the company announced The Queen's Ball: A Bridgerton Experience, launching in 2022 in Los Angeles, Chicago, Montreal, and Washington, D.C.
On September 20, 2021, Netflix signed a long-term lease with Aviva Investors to operate and expand the Longcross Studios in Surrey, UK. On September 21, 2021, Netflix announced that it would acquire the Roald Dahl Story Company, which manages the rights to Roald Dahl's stories and characters, for an undisclosed price and would operate it as an independent company. The company acquired Night School Studio, an independent video game developer, on September 28, 2021. Netflix officially launched mobile games on November 2, 2021, for Android users around the world. Through the app, subscribers had free access to five games, including two previously made Stranger Things titles. Netflix intends to add more games to this service over time. On November 9, the collection launched for iOS. Some games in the collection require an active internet connection to play, while others will be available offline. Netflix Kids' accounts will not have games available.
On October 13, 2021, Netflix announced the launch of the Netflix Book Club, where readers will hear about new books, films, and series adaptations and have exclusive access to each book's adaptation process. Netflix will partner with Starbucks to bring the book club to life via a social series called But Have You Read the Book?. Uzo Aduba will serve as the inaugural host of the series and announce monthly book selections set to be adapted by the streamer. Aduba will also speak with the cast, creators, and authors about the book adaptation process over a cup of coffee at Starbucks. Through October 2021, Netflix commonly reported viewership for its programming based on the number of viewers or households that watched a show in a given period (such as the first 28 days from its premiere) for at least two minutes. On the announcement of its quarterly earnings in October 2021, the company stated that it would switch its viewership metrics to measuring the number of hours that a show was watched, including rewatches, which the company said was closer to the measurements used in linear broadcast television, and thus "our members and the industry can better measure success in the streaming world." On November 16, 2021, Netflix announced the launch of "Top10 on Netflix.com", a new website with weekly global and country lists of the most popular titles on their service based on their new viewership metrics.
On November 22, 2021, Netflix announced that it would acquire Scanline VFX, the visual effects and animation company behind Cowboy Bebop and Stranger Things. On the same day, Roberto Patino signed a deal with Netflix and established his own production banner, Analog Inc., in partnership with the company. Patino's first project under the deal is a series adaptation of Image Comics' Nocterra. On December 6, 2021, Netflix and Stage 32 announced that they have teamed up the workshops at the Creating Content for the Global Marketplace program. On December 7, 2021, Netflix partnered with IllumiNative, a woman-led non-profit organization, for the Indigenous Producers Training Program.
On December 9, 2021, Netflix announced the launch of "Tudum", an official companion website that offers news, exclusive interviews, and behind-the-scenes videos for its original television shows and films. On December 13, 2021, Netflix signed a multi-year overall deal with Kalinda Vazquez. On December 16, 2021, Netflix signed a multi-year creative partnership with Spike Lee and his production company 40 Acres and a Mule Filmworks to develop film and television projects. In December 2021, former Netflix engineer Sung Mo Jun was sentenced to 2 years in prison for an insider trading scheme where he leaked subscriber numbers in advance of official releases.
In compliance with the EU Audiovisual Media Services Directive and its implementation in France, Netflix reached commitments with French broadcasting authorities and film guilds, as required by law, to invest a specific amount of its annual revenue into original French films and series. These films must be theatrically released and would not be allowed to be carried on Netflix until 15 months after their release.
The company announced plans to acquire Next Games in March 2022 for €65 million as part of Netflix's expansions into gaming. Next Games had developed the mobile title Stranger Things: Puzzle Tales as well as two The Walking Dead mobile games. Later in the month, Netflix also acquired the Texas-based mobile game developer, Boss Fight Entertainment, for an undisclosed sum.
Following the 2022 Russian invasion of Ukraine, Netflix suspended its operations and future projects in Russia. It also announced that it would not comply with a proposed directive by Roskomnadzor requiring all internet streaming services with more than 100,000 subscribers to integrate the major free-to-air channels (which are primarily state-owned). A month later, ex-Russian subscribers filed a class action lawsuit against Netflix.
At the end of Q1 2022, Netflix announced a decline in subscribers, with almost 200,000 fewer viewers than at the end of the previous year. Netflix stated that 100 million households globally were sharing passwords to their account with others, and that Canada and the United States accounted for 30 million of them. Following these announcements, Netflix's stock price fell by 35 percent. By June 2022, Netflix had laid off 450 full-time and contract employees as part of the company's plan to trim costs amid lower than expected subscriber growth. The layoffs represented approximately 2 percent of the workforce and spread across the company globally.
On April 28, 2022, the company launched its inaugural Netflix Is a Joke comedy festival, featuring more than 250 shows over 12 nights at 30-plus locations across Los Angeles, including the first-ever stand-up show at Dodger Stadium.
On July 19, 2022, Netflix announced plans to acquire Australian animation studio Animal Logic.
On September 5, 2022, Netflix opened an office in Warsaw, Poland responsible for the service's operations in 28 markets in Central and Eastern Europe.
On October 4, 2022, Netflix have signed a creative partnership with Andrea Berloff and John Gatins.
On October 11, 2022, Netflix signed up to the Broadcasters' Audience Research Board for external measurement of viewership in the UK.
On October 12, 2022, Netflix signed to build a production complex at Fort Monmouth in Eatontown, New Jersey.
On October 18, 2022, Netflix began exploring a cloud gaming offering and opened a new gaming studio in Southern California.
On January 10, 2023, Netflix announced plans to open an engineering hub in its Warsaw office. The hub is to provide Netflix's creative partners with software solutions in the production of films and series.
On April 18, 2023, Netflix announced that it would discontinue their DVD-by-mail service on September 29.
Netflix reworked its viewership metrics again in June 2023. Viewership of shows were measured during the first 91 days of availability, instead of the first 28 days, and now are based on the total viewership hours divided by the total hours of the show itself. This provided more equal considerations for shorter shows and movies compared to longer ones.
In August 2023, the company announced Netflix Stories, a collection of interactive narrative games from Netflix series and films such as Love is Blind, Money Heist and Virgin River.
Netflix discontinued its DVD mailing service as planned on September 29, 2023, in favor of its streaming business. Users of the service were able to keep the DVDs that they had received. Over its lifetime the service had sent out over 5 billion shipments.
In October 2023, Eunice Kim was promoted to Chief Product Officer and Elizabeth Stone was promoted to Chief Technology Officer. That same month, Netflix and Skydance Media entered a multi-year pact to develop and produce animated films, ending Skydance's partnership with Apple. First one under the deal was Spellbound, which premiered in 2024. Netflix would also take over distribution of preexisting Skydance Animation titles, including Ray Gunn and Swapped.
In April 2024, Netflix announced that starting in 2025, it would stop regularly reporting subscriber numbers.
In November 2024, Netflix offices in Paris and Amsterdam have been raided by the French and Dutch authorities as part of an investigation into tax fraud. The company is also under investigation for tax filings for 2019, 2020 and 2021.
The service began venturing into live sports broadcasting with the Jake Paul vs. Mike Tyson boxing match in November 2024, followed by a pair of National Football League games on Christmas Day. In January 2025, Netflix began a global broadcasting agreement with professional wrestling company WWE, under which its weekly series WWE Raw moved to Netflix worldwide, as well as rights outside of the United States to its library content, main roster live events, and all three of its main weekly programs.
In March 2026, Netflix announced its acquisition of Ben Affleck's artificial intelligence startup InterPositive, which was developing a generative AI model for use in filmmaking, trained initially on specially-filmed footage and designed to "understand visual logic and editorial consistency, while preserving cinematic rules under real-world production challenges". Affleck, Matt Damon, and Gerry Cardinale's studio Artists Equity also recently agreed to a first-look deal with Netflix.
Attempted acquisition of Warner Bros. (2025–2026)
On October 31, 2025, Netflix, Inc. was reported to be actively exploring a bid for the studios and streaming assets of Warner Bros. Discovery. According to the report, Netflix retained investment bank Moelis & Co. to evaluate a potential offer and had been granted access to Warner Bros. Discovery's financial data room as part of its preparatory due-diligence. Netflix stressed that it remains "predominantly focused on growing organically" and is not interested in owning legacy cable networks such as CNN, TBS and TNT.
Netflix had previously considered buying other companies such as 20th Century Fox (now 20th Century Studios), Paramount, The Walt Disney Company, and even Electronic Arts. But the price and the fear of a possible shareholder reaction prevented that.
On December 4, 2025, Netflix won the bidding war for Warner Bros. Discovery, to be followed by exclusive talks to finalize a deal. On December 5, Netflix announced a proposed agreement to acquire Warner Bros. Discovery's "Streaming and Studios" businesses for $72 billion, with a total asset value of $82.7 billion. As part of the deal, Netflix would acquire the Warner Bros. division, including its film, television and video game studios, HBO/HBO Max and their respective libraries, DC Entertainment/DC Studios and WBD's distribution, publishing and licensing divisions. The acquisition would have excluded the company's "Global Linear Networks" division (aside from Turner Classic Movies, which is aligned with the Warner Bros. film studio), which would have been divested as the separate company Discovery Global.
Paramount Skydance entered a hostile bid for the entirety of WBD at $30 per share, in an all-cash offer higher than Netflix's $27.75 per share offer for just the studios division; Paramount Skydance assessed its offer as having fewer regulatory hurdles than the Netflix offer. WBD rejected the offer due to concerns over its credibility, believing that it was inferior to Netflix's offer. On January 20, 2026, Netflix amended its own offer to an all-cash offer; WBD shareholders were expected to vote on the deal by April. On February 26, 2026, WBD agreed to a competing bid by Paramount Skydance at $31 per-share, valuing the company at approximately $111 billion. Netflix subsequently backed out, with its co-CEOs issuing a statement that its offer was "no longer financially attractive." Netflix received a $2.8 billion breakup fee from Paramount Skydance, and later announced that it would add $25 billion to its share buyback program.
Corporate affairs
Historical financials and membership growth
Board of directors
As of November 2024, the company's board consisted of the following directors:
Rich Barton (co-founder of Zillow)
Mathias Döpfner (CEO of Axel Springer SE)
Timothy M. Haley (co-founder of Redpoint Ventures)
Jay Hoag (chairman of Netflix, founding partner at TCV)
Leslie Kilgore (former Chief Marketing Officer of Netlix)
Strive Masiyiwa (chairman and founder of Econet)
Ann Mather (former Executive Vice President and Chief Financial Officer of Pixar)
Greg Peters (co-CEO of Netflix)
Susan Rice (former US National Security Advisor and ambassador to the United Nations)
Ted Sarandos (co-CEO of Netflix)
Brad Smith (vice chairman of Microsoft)
Anne Sweeney (former President of the Disney–ABC Television Group)
Corporate culture
Netflix grants all employees extremely broad discretion with respect to business decisions, expenses, and vacation—but in return expects consistently high performance, as enforced by what is known as the "keeper test". All supervisors are expected to constantly ask themselves if they would fight to keep an employee. If the answer is no, then the employee is dismissed. A slide from an internal presentation on Netflix's corporate culture summed up the test as: "Adequate performance gets a generous severance package." Such packages reportedly range from four months' salary in the United States to as much as six months in the Netherlands.
The company offers unlimited vacation time for salaried workers and allows employees to take any amount of their paychecks in stock options.
About the culture that results from applying such a demanding test, Hastings has said that "You gotta earn your job every year at Netflix," and, "There's no question it's a tough place ... There's no question it's not for everyone." Hastings has drawn an analogy to athletics: professional athletes lack long-term job security because an injury could end their career in any particular game, but they learn to put aside their fear of that constant risk and focus on working with great colleagues in the current moment.
Environmental impact
According to a study conducted by the International Energy Agency, streaming a 30-minute show on Netflix in 2019 released around 0.018 kg CO2.
In March 2021, Netflix announced that it would work to reach net zero greenhouse gas emissions by the end of 2022, while investing in programs to preserve or restore ecosystems. The company stated that it would cut emissions from its operations and electricity use by 45 percent by 2030. Due to the COVID-19 pandemic and lack of content production, Netflix had a 14 percent drop in emissions in 2020.
Source : Wikipedia (Anglais), CC BY-SA 4.0 · Voir sur Wikipedia ↗
Performance sur 10 ans Tendances du chiffre d'affaires, du bénéfice net, des marges et du BPA
Valorisation Ratios P/E, P/S, P/B, EV/EBITDA — l'action est-elle chère ou bon marché ?
| Métrique | Tendance sur 5 ans | NFLX | moyenne 5 ans | Médiane des pairs | Verdict |
|---|---|---|---|---|---|
| P/E (TTM) | -20.4moyenne 5 ans ≈195.2 | ≈195.2 | · | · | |
| P/S (TTM) | 5.8moyenne 5 ans ≈7.6 | ≈7.6 | 1.9 | Surévalué | |
| P/B (MRQ) | 9.3moyenne 5 ans ≈12.7 | ≈12.7 | 7.3 | Surévalué | |
| EV / EBITDA (TTM) | 19.3moyenne 5 ans ≈32.4 | ≈32.4 | · | · | |
| Cours / FCF (TTM) | 25.0moyenne 5 ans ≈-363.6 | ≈-363.6 | · | · | |
| Cours / Flux de trésorerie (TTM) | 23.3moyenne 5 ans ≈173.2 | ≈173.2 | 24.0 | Surévalué | |
| VE / Chiffre d'affaires (TTM) | 5.9moyenne 5 ans ≈7.8 | ≈7.8 | · | · | |
| VE / FCF (TTM) | 25.5moyenne 5 ans ≈-376.3 | ≈-376.3 | · | · | |
| Cours / Actif net tangible (MRQ) | -75.8moyenne 5 ans ≈11.1 | ≈11.1 | · | · |
La médiane des pairs est calculée sur une base standardisée par métrique et peut ne pas toujours correspondre à la base TTM/MRQ indiquée pour cette action.
Rentabilité Marges brutes, d'exploitation et nettes ; ROE, ROA, ROIC
| Métrique | Tendance sur 5 ans | NFLX | moyenne 5 ans | Médiane des pairs | Verdict |
|---|---|---|---|---|---|
| Marge d'exploitation (TTM) | 29.7%moyenne 5 ans ≈23.1% | ≈23.1% | 9.9% | Premier rang | |
| Marge EBITDA (TTM) | 30.4%moyenne 5 ans ≈24.0% | ≈24.0% | 10.3% | Premier rang | |
| Marge avant impôts (TTM) | 34.1%moyenne 5 ans ≈21.7% | ≈21.7% | 10.3% | Premier rang | |
| Marge nette (TTM) | 28.2%moyenne 5 ans ≈18.8% | ≈18.8% | 7.3% | Premier rang | |
| ROA (TTM) | 24.5%moyenne 5 ans ≈14.0% | ≈14.0% | 2.2% | Premier rang | |
| ROE (TTM) | 49.5%moyenne 5 ans ≈31.8% | ≈31.8% | 6.2% | Premier rang | |
| ROIC | 28.0%moyenne 5 ans ≈19.8% | ≈19.8% | 6.7% | Premier rang |
Santé financière Dette, liquidité, solvabilité — solidité du bilan
| Métrique | Tendance sur 5 ans | NFLX | moyenne 5 ans | Médiane des pairs | Verdict |
|---|---|---|---|---|---|
| Dette / Capitaux propres (MRQ) | 0.5moyenne 5 ans ≈0.7 | ≈0.7 | 0.4 | Endettement élevé | |
| Ratio de liquidité (MRQ) | 1.1moyenne 5 ans ≈1.1 | ≈1.1 | 1.0 | En ligne | |
| Quick Ratio (Ratio de liquidité réduite) | 0.8moyenne 5 ans ≈0.8 | ≈0.8 | 0.7 | En ligne | |
| Dette à long terme / Capitaux propres (MRQ) | 0.4moyenne 5 ans ≈0.7 | ≈0.7 | 0.4 | En ligne |
Croissance Croissance du chiffre d'affaires, du BPA et du bénéfice net : Année/Année, TCAC 3 ans, TCAC 5 ans
| Métrique | Tendance sur 5 ans | NFLX | moyenne 5 ans | Médiane des pairs | Verdict |
|---|---|---|---|---|---|
| Revenue YoY (Chiffre d'affaires YoY) | 15.8%moyenne 5 ans ≈12.7% | ≈12.7% | · | · | |
| Revenue CAGR 3Y (CAGR du chiffre d'affaires 3 ans) | 12.6%moyenne 5 ans ≈10.9% | ≈10.9% | · | · | |
| Revenue CAGR 5Y (CAGR du chiffre d'affaires 5 ans) | 12.6% | · | · | · | |
| EPS YoY (BPA Année/Année) | 27.8%moyenne 5 ans ≈15.6% | ≈15.6% | · | · | |
| Net Income YoY (Bénéfice net YoY) | 26.1%moyenne 5 ans ≈36.1% | ≈36.1% | · | · | |
| EPS CAGR 3Y (TCAC BPA 3 ans) | -36.6%moyenne 5 ans ≈-40.8% | ≈-40.8% | · | · | |
| EPS CAGR 5Y (TCAC BPA 5 ans) | -16.1% | · | · | · | |
| Net Income CAGR 3Y (TCAC Bénéfice net 3 ans) | 34.7%moyenne 5 ans ≈26.4% | ≈26.4% | · | · | |
| Net Income CAGR 5Y (TCAC Bénéfice net 5 ans) | 31.8% | · | · | · |
Efficacité du capital Rotation des actifs, rotation des stocks, rotation des créances
| Métrique | Tendance sur 5 ans | NFLX | moyenne 5 ans | Médiane des pairs | Verdict |
|---|---|---|---|---|---|
| Asset Turnover (Rotation des actifs) | 0.8moyenne 5 ans ≈0.7 | ≈0.7 | 0.6 | Premier rang | |
| Revenue / Employee (Chiffre d'affaires annuel ÷ employés (effectif déclaré, yfinance). Dérivé — pas un concept SEC-XBRL stocké.) | ≈$2.8M | · | · | · |
valeur · ≈ moyenne 5 ans · médiane du secteur · verdict par rapport à la médiane
Historique des bénéfices BPA réel vs estimation, surprise %, taux de succès, prochaine date de publication des résultats
| Période | Rapport | EPS Actual | BPA est. | Surprise |
|---|---|---|---|---|
| 30 juin 2026 | Jul 16, 2026 | $0.80 | $0.80 | -0.52% |
| 31 mars 2026 | $0.70 | $0.78 | -10.2% | |
| 31 décembre 2025 | $0.56 | $0.56 | -0.50% | |
| 30 septembre 2025 | $0.59 | $0.71 | -17.4% | |
| 30 juin 2025 | $0.72 | $0.72 | -0.40% | |
| 31 mars 2025 | $0.66 | $0.58 | 13.4% |
Fondamentaux complets Tous les indicateurs par an — compte de résultat, bilan, flux de trésorerie
Compte de résultat
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $45.18B | $39.00B | $33.72B | $31.62B | $29.70B | $25.00B | $20.16B | $15.79B | $11.69B | $8.83B | $6.78B | $5.50B | |
| Cost of Revenue | $23.28B | $21.04B | $19.72B | $19.17B | $17.33B | $15.28B | $12.44B | $9.97B | $8.03B | $6.26B | $4.59B | $3.75B | |
| R&D Expense | $3.39B | $2.93B | $2.68B | $2.71B | $2.27B | $1.83B | $1.67B | $1.22B | $981M | $768M | $570M | $398M | |
| SG&A Expense | $1.89B | $1.70B | $1.72B | $1.57B | $1.35B | $1.08B | $914M | $630M | $431M | $316M | $407M | $270M | |
| Operating Income | $13.33B | $10.42B | $6.95B | $5.63B | $6.19B | $4.59B | $2.60B | $1.61B | $839M | $380M | $306M | $403M | |
| Interest Expense | · | · | $700M | $706M | $766M | $767M | $626M | $420M | $238M | $150M | $133M | $50M | |
| Interest Income | · | $294M | $281M | $60M | · | · | · | · | · | · | · | · | |
| Other Non-op | $172M | $267M | $-49M | $337M | $411M | $-618M | $84M | $42M | $-115M | $31M | $-31M | $-3M | |
| Pretax Income | $12.72B | $9.97B | $6.21B | $5.26B | $5.84B | $3.20B | $2.06B | $1.23B | $485M | $261M | $142M | $349M | |
| Income Tax | $1.74B | $1.25B | $797M | $772M | $724M | $438M | $195M | $15M | $-74M | $74M | $19M | $83M | |
| Net Income | $10.98B | $8.71B | $5.41B | $4.49B | $5.12B | $2.76B | $1.87B | $1.21B | $559M | $187M | $123M | $267M | |
| EPS (Basic) | $2.58 | $2.03 | $1.22 | $10.10 | $11.55 | $6.26 | $4.26 | $2.78 | $1.29 | $0.44 | $0.29 | $0.63 | |
| EPS (Diluted) | $2.53 | $1.98 | $1.20 | $9.95 | $11.24 | $6.08 | $4.13 | $2.68 | $1.25 | $0.43 | $0.28 | $0.62 | |
| Shares (Basic) | 4,249,512,000 | 4,295,191,000 | 4,415,712,000 | 444,698,000 | 443,155,000 | 440,922,000 | 437,799,000 | 435,374,000 | 431,885,000 | 428,822,000 | 425,889,000 | 420,544,000 | |
| Shares (Diluted) | 4,343,863,000 | 4,392,608,000 | 4,494,966,000 | 451,290,000 | 455,372,000 | 454,208,000 | 451,765,000 | 451,244,000 | 446,814,000 | 438,652,000 | 436,456,000 | 431,894,000 | |
| EBITDA | $13.66B | $10.75B | $7.31B | $5.97B | $6.40B | $4.70B | $2.71B | · | $911M | $437M | $368M | $457M |
Bilan
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $9.03B | $7.80B | $7.12B | $5.15B | $6.03B | $8.21B | $5.02B | $3.79B | $2.82B | $1.47B | $1.81B | $1.11B | |
| Short-term Investments | $29M | $1.78B | $21M | $911M | $0 | · | · | · | $0 | $266M | $501M | $495M | |
| Prepaid Expense | $498M | $432M | $409M | $393M | $324M | $203M | $181M | $179M | · | · | · | · | |
| Other Current Assets | $3.96B | $3.52B | $2.78B | $3.21B | $2.04B | $1.56B | $1.16B | $748M | $536M | $260M | $215M | $152M | |
| Current Assets | $13.02B | $13.10B | $9.92B | $9.27B | $8.07B | $9.76B | $6.18B | $9.69B | $7.67B | $5.72B | $5.43B | $3.93B | |
| PP&E (Net) | $2.00B | $1.59B | $1.49B | $1.40B | $1.32B | $960M | $565M | $418M | $319M | $250M | $173M | $150M | |
| PP&E (Gross) | $3.10B | $2.51B | $2.35B | $2.15B | $1.94B | $1.45B | $981M | $787M | $641M | $545M | $471M | $415M | |
| Accum. Depreciation | $1.10B | $918M | $855M | $754M | $616M | $495M | $416M | $369M | $322M | $294M | $297M | $265M | |
| Intangibles | $32.78B | $32.45B | · | · | · | · | · | · | · | · | · | · | |
| Other Non-current Assets | $7.79B | $6.48B | $5.66B | $5.19B | $4.27B | $3.17B | $2.73B | $911M | $652M | $341M | $285M | $192M | |
| Total Assets | $55.60B | $53.63B | $48.73B | $48.59B | $44.58B | $39.28B | $33.98B | $25.97B | $19.01B | $13.59B | $10.20B | $7.04B | |
| Accounts Payable | $901M | $900M | $747M | $672M | $837M | $656M | $674M | $563M | $360M | $313M | $253M | $202M | |
| Accrued Liabilities | $3.22B | $2.16B | $1.80B | $1.51B | $1.45B | $1.10B | $843M | $482M | $315M | $198M | $140M | $70M | |
| Short-term Debt | $999M | $1.78B | $400M | $0 | $700M | $500M | $0 | · | · | · | · | · | |
| Current Liabilities | $10.98B | $10.76B | $8.86B | $7.93B | $8.49B | $7.81B | $6.86B | $6.49B | $5.47B | $4.59B | $3.53B | $2.66B | |
| Capital Leases | $2.05B | $1.98B | $2.05B | $2.22B | $2.41B | $1.95B | $1.42B | · | · | · | · | · | |
| Other Non-current Liabilities | $2.96B | $2.55B | $2.56B | $2.45B | $2.46B | $1.98B | $1.44B | $129M | $135M | $61M | $52M | $60M | |
| Total Liabilities | $28.98B | $28.89B | $28.14B | $27.82B | $28.74B | $28.22B | $26.39B | $20.74B | $15.43B | $10.91B | $7.98B | $5.18B | |
| Long-term Debt | · | · | · | · | · | $21.86B | $20.72B | $14.87B | $9.05B | · | · | · | |
| Total Debt | $14.46B | $15.58B | $14.54B | $14.35B | $15.39B | $16.31B | $14.76B | · | $6.50B | $3.36B | $2.37B | $900M | |
| Common Stock | $7.29B | $6.25B | $5.15B | $4.64B | $4.02B | $3.45B | $2.79B | $2.32B | $1.87B | $1.60B | $1.32B | $1.04B | |
| Retained Earnings | $42.28B | $31.30B | $22.59B | $17.18B | $12.69B | $7.57B | $4.81B | $2.94B | $1.73B | $1.13B | $942M | $819M | |
| Treasury Stock | $22.37B | $13.17B | $6.92B | $824M | $824M | $0 | · | · | · | · | · | · | |
| AOCI | $-580M | $362M | $-224M | $-217M | $-40M | $44M | $-24M | $-20M | $-21M | $-49M | $-43M | $-4M | |
| Stockholders' Equity | $26.62B | $24.74B | $20.59B | $20.78B | $15.85B | $11.07B | $7.58B | $5.24B | $3.58B | $2.68B | $2.22B | $1.86B | |
| Liabilities + Equity | $55.60B | $53.63B | $48.73B | $48.59B | $44.58B | $39.28B | $33.98B | $25.97B | $19.01B | $13.59B | $10.20B | $7.04B | |
| Shares Outstanding | 4,222,162,150 | 4,277,571,000 | 432,759,584 | 445,346,776 | 443,963,107 | 442,895,261 | 438,806,649 | 436,598,597 | 433,392,686 | 430,054,212 | 427,940,440 | 422,910,887 |
Flux de trésorerie
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $333M | $329M | $357M | $337M | $208M | $116M | $104M | $83M | $72M | $58M | $62M | $54M | |
| Stock-based Comp | $368M | $273M | $339M | $575M | $403M | $415M | $405M | $321M | $182M | $174M | $125M | $115M | |
| Deferred Tax | $-449M | $-591M | $-543M | $-135M | $200M | $70M | $-95M | $-86M | $-209M | $-47M | $-59M | $-30M | |
| Other Non-cash | $-1.08B | $-1.36B | $1.71B | $-3.24B | $-5.53B | $-935M | $-5.17B | · | $-2.39B | $-1.85B | $-1.00B | $-390M | |
| Operating Cash Flow | $10.15B | $7.36B | $7.27B | $2.03B | $393M | $2.43B | $-2.89B | $-2.68B | $-1.79B | $-1.47B | $-749M | $16M | |
| CapEx | $688M | $440M | $349M | $408M | $525M | $498M | $253M | $174M | $173M | $108M | $91M | $70M | |
| Investing Cash Flow | $1.04B | $-2.18B | $542M | $-2.08B | $-1.34B | $-505M | $-387M | $-339M | $34M | $50M | $-179M | $-43M | |
| Debt Issued | · | · | · | · | · | · | · | · | $3.02B | $1.00B | $1.50B | $400M | |
| Net Debt Issued | $-1.83B | $-400M | $0 | $-700M | $-500M | · | · | · | $3.02B | $1.00B | $1.50B | $400M | |
| Stock Issued | · | · | · | · | $174M | $235M | $72M | $125M | $88M | $37M | $78M | $61M | |
| Stock Repurchased | $9.13B | $6.26B | $6.05B | $0 | $600M | $0 | $0 | · | · | · | · | · | |
| Net Stock Activity | $-9.13B | $-6.26B | $-6.05B | $0 | $-426M | $235M | $72M | · | $88M | $37M | $78M | $61M | |
| Financing Cash Flow | $-10.35B | $-4.07B | $-5.95B | $-664M | $-1.15B | $1.24B | $4.51B | $4.05B | $3.08B | $1.09B | $1.64B | $542M | |
| Net Change in Cash | $1.23B | $689M | $1.95B | $-885M | $-2.18B | $3.20B | $1.23B | $989M | $1.36B | $-342M | $696M | $509M | |
| Taxes Paid | $2.22B | $1.64B | $1.16B | · | · | · | · | · | · | · | · | · | |
| Free Cash Flow | $9.46B | $6.92B | $6.93B | $1.62B | $-132M | $1.93B | $-3.14B | · | $-1.96B | $-1.58B | $-841M | $-53M | |
| Levered FCF | · | · | $6.32B | $1.02B | $-803M | $1.27B | $-3.71B | · | $-2.23B | $-1.69B | $-955M | $-92M |
Rentabilité
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | 29.5% | 26.7% | 20.6% | 17.8% | 20.9% | 18.3% | 12.9% | · | 7.2% | 4.3% | 4.5% | 7.3% | |
| Net Margin | 24.3% | 22.3% | 16.0% | 14.2% | 17.2% | 11.1% | 9.3% | · | 4.8% | 2.1% | 1.8% | 4.9% | |
| Pretax Margin | 28.2% | 25.6% | 18.4% | 16.7% | 19.7% | 12.8% | 10.2% | · | 4.2% | 2.9% | 2.1% | 6.3% | |
| EBITDA Margin | 30.2% | 27.6% | 21.7% | 18.9% | 21.6% | 18.8% | 13.4% | · | 7.8% | 5.0% | 5.4% | 8.3% | |
| ROA | 20.1% | 17.0% | 11.1% | 9.6% | 12.2% | 7.5% | 6.2% | · | 3.4% | 1.6% | 1.4% | 4.3% | |
| ROE | 42.6% | 36.7% | 25.3% | 21.8% | 32.8% | 25.8% | 25.9% | · | 17.8% | 7.6% | 6.0% | 16.7% | |
| ROIC | 28.0% | 22.6% | 17.2% | 13.7% | 17.4% | 14.5% | 10.5% | · | 9.6% | 4.5% | 5.8% | 11.2% |
Liquidité et Solvabilité
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.2 | 1.2 | 1.1 | 1.2 | 1.0 | 1.3 | 0.9 | · | 1.4 | 1.2 | 1.5 | 1.5 | |
| Quick Ratio | 0.8 | 0.9 | 0.8 | 0.8 | 0.7 | 1.1 | 0.7 | · | 0.5 | 0.4 | 0.7 | 0.6 | |
| Debt / Equity | 0.5 | 0.6 | 0.7 | 0.7 | 1.0 | 1.5 | 1.9 | · | 1.8 | 1.3 | 1.1 | 0.5 | |
| LT Debt / Equity | 0.5 | 0.6 | 0.7 | 0.7 | 0.9 | 1.4 | 1.9 | · | 1.8 | 1.3 | 1.1 | 0.5 | |
| Interest Coverage | · | · | 9.9 | 8.0 | 8.1 | 6.0 | 4.2 | · | 3.5 | 2.5 | 2.3 | 8.0 |
Efficacité
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.8 | 0.8 | 0.7 | 0.7 | 0.7 | 0.7 | 0.7 | · | 0.7 | 0.7 | 0.8 | 0.9 |
Par action
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $6.30 | $57.84 | $47.57 | $46.65 | $35.70 | $24.98 | $17.28 | · | $8.26 | $6.23 | $5.20 | $30.75 | |
| Revenue / Share | $10.40 | $88.79 | $75.02 | $70.06 | $65.22 | $55.03 | $44.62 | · | $26.17 | $20.13 | $15.53 | $89.22 | |
| Cash Flow / Share | $2.34 | $16.76 | $16.18 | $4.49 | $0.86 | $5.34 | $-6.39 | · | $-4.00 | $-3.36 | $-1.72 | $0.27 | |
| Cash / Share | $2.14 | $18.25 | $16.45 | $11.56 | $13.58 | $18.53 | $11.44 | · | $6.51 | $3.41 | $4.23 | $18.43 | |
| EPS (TTM) | $2.53 | $1.98 | $1.20 | $9.95 | $11.24 | $6.08 | $4.13 | $2.68 | $1.25 | $0.43 | $0.28 | $0.62 |
Taux de croissance
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue YoY | 15.8% | 15.7% | 6.7% | 6.5% | 18.8% | · | · | · | · | · | · | · | |
| Revenue CAGR 3Y | 12.6% | 9.5% | 10.5% | · | · | · | · | · | · | · | · | · | |
| Revenue CAGR 5Y | 12.6% | · | · | · | · | · | · | · | · | · | · | · | |
| EPS YoY | 27.8% | 65.0% | -87.9% | -11.5% | 84.9% | · | · | · | · | · | · | · | |
| EPS CAGR 3Y | -36.6% | -43.9% | -41.8% | · | · | · | · | · | · | · | · | · | |
| EPS CAGR 5Y | -16.1% | · | · | · | · | · | · | · | · | · | · | · | |
| Net Income YoY | 26.1% | 61.1% | 20.4% | -12.2% | 85.3% | · | · | · | · | · | · | · | |
| Net Income CAGR 3Y | 34.7% | 19.4% | 25.1% | · | · | · | · | · | · | · | · | · | |
| Net Income CAGR 5Y | 31.8% | · | · | · | · | · | · | · | · | · | · | · |
Valorisation (TTM)
| Métrique | Tendance | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $45.18B | $39.00B | $33.72B | $31.62B | $29.70B | $25.00B | $20.16B | $15.79B | $11.69B | $8.83B | $6.78B | $5.50B | |
| Net Income TTM | $10.98B | $8.71B | $5.41B | $4.49B | $5.12B | $2.76B | $1.87B | $1.21B | $559M | $187M | $123M | $267M | |
| Market Cap | $395.87B | $381.27B | $210.70B | $131.32B | $267.46B | $239.49B | $141.98B | · | $83.19B | $53.24B | $48.95B | $2.95B | |
| Enterprise Value | $401.27B | $387.27B | $218.11B | $139.62B | $276.83B | $247.59B | $151.73B | · | $86.87B | $54.87B | $49.01B | $2.24B | |
| P/E | 37.1 | 450.2 | 405.7 | 29.6 | 53.6 | 88.9 | 78.3 | 99.9 | 153.6 | 287.9 | 408.5 | 78.7 | |
| P/S | 8.8 | 9.8 | 6.2 | 4.2 | 9.0 | 9.6 | 7.0 | · | 7.1 | 6.0 | 7.2 | 0.5 | |
| P/B | 14.9 | 15.4 | 10.2 | 6.3 | 16.9 | 21.6 | 18.7 | · | 23.2 | 19.9 | 22.0 | 1.6 | |
| P / Tangible Book | · | · | 10.2 | 6.3 | 16.9 | 21.6 | · | · | · | · | · | · | |
| P / Cash Flow | 39.0 | 51.8 | 29.0 | 64.8 | 681.2 | 98.7 | -49.2 | · | -46.6 | -36.1 | -65.3 | 178.9 | |
| P / FCF | 41.8 | 55.1 | 30.4 | 81.1 | -2026.6 | 124.1 | -45.2 | · | -42.5 | -33.7 | -58.2 | -55.4 | |
| EV / EBITDA | 29.4 | 36.0 | 29.8 | 23.4 | 43.2 | 52.7 | 56.0 | · | 95.4 | 125.5 | 133.1 | 4.9 | |
| EV / FCF | 42.4 | 55.9 | 31.5 | 86.3 | -2097.6 | 128.3 | -48.3 | · | -44.3 | -34.7 | -58.3 | -42.1 | |
| EV / Revenue | 8.9 | 9.9 | 6.5 | 4.4 | 9.3 | 9.9 | 7.5 | · | 7.4 | 6.2 | 7.2 | 0.4 | |
| Earnings Yield | 2.7% | 0.22% | 0.25% | 3.4% | 1.9% | 1.1% | 1.3% | 1.0% | 0.65% | 0.35% | 0.24% | 1.3% |
Compte de résultat
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $12.56B | $12.25B | $12.05B | $11.51B | $11.08B | $10.54B | $10.25B | $9.82B | $9.56B | $9.37B | $8.83B | $8.54B | $8.19B | $8.16B | $7.85B | $7.93B | |
| Cost of Revenue | $6.04B | $5.89B | $6.52B | $6.16B | $5.33B | $5.26B | $5.77B | $5.12B | $5.17B | $4.98B | $5.31B | $4.93B | $4.67B | $4.80B | $5.40B | $4.79B | |
| R&D Expense | $1.01B | $960M | $890M | $854M | $825M | $823M | $777M | $735M | $711M | $702M | $673M | $657M | $658M | $687M | $674M | $663M | |
| SG&A Expense | $499M | $603M | $568M | $458M | $441M | $421M | $454M | $417M | $427M | $404M | $439M | $479M | $401M | $401M | $392M | $373M | |
| Operating Income | $4.19B | $3.96B | $2.96B | $3.25B | $3.77B | $3.35B | $2.27B | $2.91B | $2.60B | $2.63B | $1.50B | $1.92B | $1.83B | $1.71B | $550M | $1.53B | |
| Interest Expense | · | · | · | · | · | · | · | $185M | $168M | $173M | · | $176M | $175M | $174M | · | $173M | |
| Other Non-op | $52M | $2.85B | $45M | $36M | $40M | $51M | $54M | $-22M | $79M | $155M | $-173M | $168M | $27M | $-71M | $-340M | $261M | |
| Pretax Income | $4.07B | $6.55B | $2.77B | $3.11B | $3.63B | $3.21B | $2.13B | $2.70B | $2.51B | $2.61B | $1.15B | $1.91B | $1.68B | $1.47B | $39M | $1.62B | |
| Income Tax | $667M | $1.26B | $349M | $562M | $506M | $323M | $266M | $339M | $367M | $282M | $210M | $232M | $192M | $164M | $-16M | $224M | |
| Net Income | $3.40B | $5.28B | $2.42B | $2.55B | $3.13B | $2.89B | $1.87B | $2.36B | $2.15B | $2.33B | $938M | $1.68B | $1.49B | $1.31B | $55M | $1.40B | |
| EPS (Basic) | $0.81 | $1.25 | $-11.45 | $6.00 | $0.74 | $0.68 | $-13.88 | $5.52 | $4.99 | $5.40 | $-8.86 | $3.80 | $3.35 | $2.93 | $0.12 | $3.14 | |
| EPS (Diluted) | $0.80 | $1.23 | $-11.19 | $5.87 | $0.72 | $0.66 | $-13.58 | $5.40 | $4.88 | $5.28 | $-8.70 | $3.73 | $3.29 | $2.88 | $0.12 | $3.10 | |
| Shares (Basic) | 4,189,303,000 | 4,222,787,000 | · | 424,455,000 | 4,252,112,000 | 4,272,695,000 | · | 428,239,000 | 430,065,000 | 432,090,000 | · | 441,537,000 | 443,881,000 | 445,244,000 | · | 444,878,000 | |
| Shares (Diluted) | 4,261,300,000 | 4,298,437,000 | · | 434,039,000 | 4,348,825,000 | 4,369,623,000 | · | 437,898,000 | 439,739,000 | 441,654,000 | · | 450,011,000 | 451,572,000 | 452,417,000 | · | 450,344,000 | |
| EBITDA | $4.29B | $4.06B | · | $3.34B | $3.85B | $3.43B | · | $2.99B | $2.68B | $2.72B | · | $2.01B | $1.92B | $1.80B | · | $1.62B |
Bilan
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $9.10B | $12.26B | $9.03B | $9.29B | $8.18B | $7.20B | $7.80B | $7.46B | $6.62B | $7.02B | · | $7.35B | $7.66B | $6.71B | · | $6.11B | |
| Short-term Investments | $29M | $29M | $29M | $37M | $213M | $1.17B | $1.78B | $1.77B | $31M | $21M | · | $514M | $914M | $1.11B | · | · | |
| Prepaid Expense | $585M | $602M | $498M | $468M | $451M | $484M | $432M | $436M | $446M | $454M | · | $482M | $482M | $486M | · | $392M | |
| Other Current Assets | $4.73B | $4.78B | $3.96B | $3.64B | $3.60B | $3.33B | $3.52B | $2.91B | $2.96B | $2.88B | · | $2.91B | $2.93B | $2.66B | · | $2.70B | |
| Current Assets | $13.85B | $17.07B | $13.02B | $12.96B | $11.99B | $11.70B | $13.10B | $12.13B | $9.62B | $9.92B | · | $10.78B | $11.51B | $10.48B | · | $8.82B | |
| PP&E (Net) | $2.40B | $2.15B | $2.00B | $1.84B | $1.74B | $1.64B | $1.59B | $1.57B | $1.51B | $1.50B | · | $1.50B | $1.47B | $1.41B | · | $1.37B | |
| PP&E (Gross) | $3.62B | $3.30B | $3.10B | $2.88B | $2.78B | $2.62B | $2.51B | $2.49B | $2.43B | $2.39B | · | $2.40B | $2.34B | $2.22B | · | $2.08B | |
| Accum. Depreciation | $1.22B | $1.16B | $1.10B | $1.05B | $1.04B | $976M | $918M | $922M | $915M | $885M | · | $903M | $871M | $808M | · | $710M | |
| Intangibles | $33.84B | $33.38B | $32.78B | $32.64B | $32.09B | $32.04B | $32.45B | · | · | · | · | · | · | · | · | · | |
| Other Non-current Assets | $8.36B | $8.42B | $7.79B | $7.49B | $7.27B | $6.70B | $6.48B | $6.41B | $6.05B | $5.74B | · | $5.47B | $5.32B | $5.25B | · | $4.60B | |
| Total Assets | $58.45B | $61.02B | $55.60B | $54.93B | $53.10B | $52.09B | $53.63B | $52.28B | $49.10B | $48.83B | · | $49.50B | $50.82B | $49.49B | · | $47.56B | |
| Accounts Payable | $815M | $895M | $901M | $793M | $633M | $614M | $900M | $642M | $599M | $607M | · | $534M | $615M | $592M | · | $560M | |
| Accrued Liabilities | $3.17B | $4.44B | $3.22B | $3.11B | $2.49B | $2.36B | $2.16B | $2.24B | $1.88B | $1.98B | · | $1.84B | $1.91B | $1.72B | · | $1.80B | |
| Short-term Debt | $2.48B | $999M | $999M | $0 | $0 | $1.01B | $1.78B | $1.82B | $1.80B | $799M | · | $400M | $399M | $399M | · | $0 | |
| Current Liabilities | $12.13B | $12.13B | $10.98B | $9.73B | $8.94B | $9.72B | $10.76B | $10.71B | $10.14B | $9.29B | · | $8.34B | $8.68B | $8.32B | · | $7.77B | |
| Capital Leases | $1.90B | $1.95B | $2.05B | $2.16B | $2.03B | $1.97B | $1.98B | $2.09B | $2.13B | $2.10B | · | $2.09B | $2.15B | $2.16B | · | $2.21B | |
| Other Non-current Liabilities | $2.71B | $2.77B | $2.96B | $3.19B | $3.15B | $2.63B | $2.55B | $2.77B | $2.64B | $2.59B | · | $2.49B | $2.39B | $2.40B | · | $2.42B | |
| Total Liabilities | $28.30B | $29.89B | $28.98B | $28.98B | $28.15B | $28.06B | $28.89B | $29.56B | $26.99B | $27.46B | · | $27.39B | $27.99B | $27.66B | · | $27.03B | |
| Total Debt | $14.31B | $14.36B | · | $14.46B | $14.45B | $15.02B | · | $15.98B | $13.98B | $14.02B | · | $14.30B | $14.47B | $14.44B | · | $13.89B | |
| Common Stock | $7.67B | $7.48B | $7.29B | $7.08B | $6.93B | $6.68B | $6.25B | $5.89B | $5.68B | $5.49B | · | $5.01B | $4.87B | $4.76B | · | $4.47B | |
| Retained Earnings | $50.97B | $47.56B | $42.28B | $39.86B | $37.32B | $34.19B | $31.30B | $29.43B | $27.07B | $24.92B | · | $21.65B | $19.97B | $18.49B | · | $17.13B | |
| Treasury Stock | $28.39B | $23.68B | $22.37B | $20.27B | $18.39B | $16.75B | $13.17B | $12.25B | $10.55B | $8.93B | · | $4.40B | $1.88B | $1.23B | · | $824M | |
| AOCI | $-97M | $-235M | $-580M | $-719M | $-905M | $-86M | $362M | $-345M | $-89M | $-112M | · | $-156M | $-139M | $-192M | · | $-248M | |
| Stockholders' Equity | $30.15B | $31.13B | $26.62B | $25.95B | $24.95B | $24.03B | $24.74B | $22.72B | $22.11B | $21.37B | $20.59B | $22.11B | $22.83B | $21.83B | $20.78B | $20.53B | |
| Liabilities + Equity | $58.45B | $61.02B | $55.60B | $54.93B | $53.10B | $52.09B | $53.63B | $52.28B | $49.10B | $48.83B | · | $49.50B | $50.82B | $49.49B | · | $47.56B | |
| Shares Outstanding | 4,163,939,676 | 4,212,794,271 | 4,222,162,150 | 423,732,334 | 424,926,346 | 425,683,210 | 4,277,571,000 | 427,458,114 | 429,164,615 | 430,964,991 | · | 437,679,669 | 443,146,751 | 444,536,878 | 445,346,776 | 445,020,494 |
Flux de trésorerie
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $101M | $99M | $86M | $87M | $80M | $80M | $80M | $81M | $81M | $87M | $87M | $91M | $89M | $90M | $93M | $85M | |
| Stock-based Comp | $131M | $140M | $135M | $81M | $81M | $72M | $62M | $66M | $69M | $76M | $83M | $80M | $78M | $99M | $154M | $152M | |
| Deferred Tax | · | · | · | · | · | · | · | · | · | · | · | · | · | · | $108M | $-58M | |
| Other Non-cash | $-1.89B | $-232M | · | $110M | $-863M | $-253M | · | $-189M | $-1.01B | $-283M | · | $145M | $-215M | $684M | · | $-1.02B | |
| Operating Cash Flow | $1.74B | $5.29B | $2.11B | $2.83B | $2.42B | $2.79B | $1.54B | $2.32B | $1.29B | $2.21B | $1.66B | $1.99B | $1.44B | $2.18B | $444M | $557M | |
| CapEx | $219M | $196M | $239M | $165M | $156M | $128M | $159M | $127M | $78M | $76M | $82M | $104M | $101M | $62M | $112M | $85M | |
| Investing Cash Flow | $-219M | $-782M | $-257M | $44M | $769M | $486M | $-159M | $-1.87B | $-78M | $-76M | $412M | $296M | $98M | $-264M | $-1.59B | $-85M | |
| Net Debt Issued | $0 | $0 | · | $0 | $-1.03B | $-800M | · | $0 | $0 | $-400M | · | $0 | $0 | $0 | · | $0 | |
| Stock Repurchased | $4.71B | $1.27B | $2.08B | $1.86B | $1.65B | $3.54B | $964M | $1.70B | $1.60B | $2.00B | $2.50B | $2.50B | $645M | $400M | $0 | $0 | |
| Net Stock Activity | $-4.71B | $-1.27B | · | $-1.86B | $-1.65B | $-3.54B | · | $-1.70B | $-1.60B | $-2.00B | · | $-2.50B | $-645M | $-400M | · | $0 | |
| Financing Cash Flow | $-4.67B | $-1.23B | $-2.08B | $-1.74B | $-2.50B | $-4.03B | $-679M | $227M | $-1.49B | $-2.13B | $-2.45B | $-2.48B | $-649M | $-374M | $7M | $4M | |
| Net Change in Cash | $-3.16B | $3.23B | $-252M | $1.11B | $977M | $-603M | $348M | $832M | $-400M | $-92M | $-238M | $-309M | $928M | $1.57B | $-970M | $296M | |
| Free Cash Flow | $1.53B | $5.09B | · | $2.66B | $2.27B | $2.66B | · | $2.19B | $1.21B | $2.14B | · | $1.89B | $1.34B | $2.12B | · | $472M | |
| Levered FCF | · | · | · | · | · | · | · | $2.03B | $1.07B | $1.98B | · | $1.73B | $1.18B | $1.96B | · | $323M |
Rentabilité
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | 33.4% | 32.3% | · | 28.2% | 34.1% | 31.8% | · | 29.6% | 27.2% | 28.1% | · | 22.4% | 22.3% | 21.0% | · | 19.3% | |
| Net Margin | 27.1% | 43.1% | · | 22.1% | 28.2% | 27.4% | · | 24.1% | 22.5% | 24.9% | · | 19.6% | 18.2% | 16.0% | · | 17.6% | |
| Pretax Margin | 32.4% | 53.4% | · | 27.0% | 32.8% | 30.5% | · | 27.5% | 26.3% | 27.9% | · | 22.4% | 20.5% | 18.0% | · | 20.5% | |
| EBITDA Margin | 34.2% | 33.1% | · | 29.0% | 34.8% | 32.5% | · | 30.4% | 28.1% | 29.0% | · | 23.5% | 23.4% | 22.1% | · | 20.4% | |
| ROA | 6.1% | 9.3% | · | 4.8% | 6.1% | 5.7% | · | 4.6% | 4.3% | 4.7% | · | 3.5% | 3.1% | 2.8% | · | 3.1% | |
| ROE | 12.3% | 19.2% | · | 10.5% | 13.3% | 12.7% | · | 10.5% | 9.6% | 10.8% | · | 7.9% | 7.1% | 6.6% | · | 7.8% | |
| ROIC | 7.9% | 7.0% | · | 6.6% | 8.2% | 7.7% | · | 6.6% | 6.2% | 6.6% | · | 4.6% | 4.3% | 4.2% | · | 3.8% |
Liquidité et Solvabilité
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.1 | 1.4 | · | 1.3 | 1.3 | 1.2 | · | 1.1 | 0.9 | 1.1 | · | 1.3 | 1.3 | 1.3 | · | 1.1 | |
| Quick Ratio | 0.8 | 1.0 | · | 1.0 | 0.9 | 0.9 | · | 0.9 | 0.7 | 0.8 | · | 0.9 | 1.0 | 0.9 | · | 0.8 | |
| Debt / Equity | 0.5 | 0.5 | · | 0.6 | 0.6 | 0.6 | · | 0.7 | 0.6 | 0.7 | · | 0.6 | 0.6 | 0.7 | · | 0.7 | |
| LT Debt / Equity | 0.4 | 0.4 | · | 0.6 | 0.6 | 0.6 | · | 0.6 | 0.6 | 0.6 | · | 0.6 | 0.6 | 0.6 | · | 0.7 | |
| Interest Coverage | · | · | · | · | · | · | · | 15.7 | 15.5 | 15.2 | · | 10.9 | 10.5 | 9.8 | · | 8.9 |
Efficacité
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 |
Par action
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $7.24 | $7.39 | · | $61.25 | $58.72 | $56.45 | · | $53.15 | $51.52 | $49.58 | · | $50.51 | $51.52 | $49.10 | · | $46.13 | |
| Revenue / Share | $2.95 | $2.85 | · | $26.52 | $25.48 | $24.13 | · | $22.44 | $21.74 | $21.22 | · | $18.98 | $18.13 | $18.04 | · | $17.60 | |
| Cash Flow / Share | $0.41 | $1.23 | · | $6.51 | $5.57 | $6.38 | · | $5.30 | $2.94 | $5.01 | · | $4.43 | $3.19 | $4.82 | · | $1.24 | |
| Cash / Share | $2.19 | $2.91 | · | $21.92 | $19.24 | $16.91 | · | $17.45 | $15.44 | $16.30 | · | $16.80 | $17.29 | $15.10 | · | $13.74 | |
| EPS (TTM) | $-3.29 | $-3.37 | · | $-6.33 | $-6.80 | $-2.64 | · | $6.86 | $5.19 | $3.60 | · | $10.02 | $9.39 | $9.30 | · | $11.16 |
Valorisation (TTM)
| Métrique | Tendance | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $48.37B | $46.89B | · | $43.38B | $41.69B | $40.17B | · | $37.59B | $36.30B | $34.93B | · | $32.74B | $32.13B | $31.91B | · | $31.47B | |
| Net Income TTM | $13.65B | $13.37B | · | $10.43B | $10.25B | $9.27B | · | $7.78B | $7.09B | $6.44B | · | $4.53B | $4.25B | $4.20B | · | $5.04B | |
| Market Cap | $297.31B | $405.06B | · | $508.02B | $569.03B | $396.96B | · | $303.18B | $289.63B | $261.74B | · | $165.27B | $195.20B | $153.58B | · | $104.78B | |
| Enterprise Value | $302.49B | $407.13B | · | $513.16B | $575.09B | $403.61B | · | $309.94B | $296.96B | $268.71B | · | $171.70B | $201.09B | $160.19B | · | $112.55B | |
| P/E | -21.7 | -28.5 | · | -189.4 | -196.9 | -353.2 | · | 103.4 | 130.0 | 168.7 | · | 37.7 | 46.9 | 37.1 | · | 21.1 | |
| P/S | 6.1 | 8.6 | · | 11.7 | 13.6 | 9.9 | · | 8.1 | 8.0 | 7.5 | · | 5.0 | 6.1 | 4.8 | · | 3.3 | |
| P/B | 9.9 | 13.0 | · | 19.6 | 22.8 | 16.5 | · | 13.3 | 13.1 | 12.3 | · | 7.5 | 8.5 | 7.0 | · | 5.1 | |
| P / Tangible Book | · | · | · | · | · | · | · | 13.3 | 13.1 | 12.3 | · | 7.5 | 8.5 | 7.0 | · | 5.1 | |
| P / Cash Flow | 170.5 | 76.6 | · | 179.8 | 234.8 | 142.3 | · | 130.6 | 224.4 | 118.3 | · | 83.0 | 135.5 | 70.5 | · | 188.2 | |
| EV / Revenue | 6.3 | 8.7 | · | 11.8 | 13.8 | 10.0 | · | 8.2 | 8.2 | 7.7 | · | 5.2 | 6.3 | 5.0 | · | 3.6 | |
| Earnings Yield | -4.6% | -3.5% | · | -0.53% | -0.51% | -0.28% | · | 0.97% | 0.77% | 0.59% | · | 2.6% | 2.1% | 2.7% | · | 4.7% |
Période la plus récente à gauche · valeurs nulles affichées comme ·
États financiers Compte de résultat, bilan, flux de trésorerie — annuel, sur les 5 dernières années
| Métrique | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Revenu | $45.18B | $39.00B | $33.72B | $31.62B | $29.70B |
| Marge d'exploitation % | 29.5% | 26.7% | 20.6% | 17.8% | 20.9% |
| Résultat net | $10.98B | $8.71B | $5.41B | $4.49B | $5.12B |
| BPA dilué | $2.53 | $1.98 | $1.20 | $9.95 | $11.24 |
| Métrique | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Dette / Capitaux propres | 0.5 | 0.6 | 0.7 | 0.7 | 1.0 |
| Ratio de liquidité | 1.2 | 1.2 | 1.1 | 1.2 | 1.0 |
| Ratio de liquidité réduite | 0.8 | 0.9 | 0.8 | 0.8 | 0.7 |
| Métrique | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Flux de trésorerie libre | $9.46B | $6.92B | $6.93B | $1.62B | $-132M |
Détenteurs institutionnels (13F) 3 778 déclarants · $299.3B total · Au 30 septembre 2026
Institutions qui déclarent détenir cette action dans leur Formulaire SEC 13F trimestriel. Uniquement les positions longues ; un même déclarant peut apparaître deux fois pour des jambes d'options distinctes. Les jambes put/call compensatoires importantes reflètent généralement la tenue de marché ou un inventaire couvert, pas une conviction directionnelle.
| Nouvelles positions | Positions clôturées | Augmenté | Diminué | Variation nette des actions |
|---|---|---|---|---|
| 223 (-245 vs T. préc.) | 372 (+149 vs T. préc.) | 1 531 (-372 vs T. préc.) | 1 408 (+317 vs T. préc.) | -18.2M |
Comparé à Q1 2026. Les dépôts de formulaire 13F de la SEC sont dus dans les 45 jours suivant la fin du trimestre, plus une courte période tampon pour les déposants tardifs — les trimestres encore dans cette fenêtre sont ignorés au profit de la paire la plus récente entièrement déclarée.
| Institution | Valeur | Actions | % de 13F suivies | Type |
|---|---|---|---|---|
| VANGUARD GROUP INC | $36 567 804 619 | 390 014 981 | 12,22% | Actions |
| BlackRock, Inc. | $24 902 220 805 | 348 770 600 | 8,32% | Actions |
| VANGUARD CAPITAL MANAGEMENT LLC | $19 636 923 230 | 275 026 936 | 6,56% | Actions |
| STATE STREET CORP | $12 861 252 155 | 180 129 582 | 4,30% | Actions |
| FMR LLC | $9 705 920 859 | 135 937 268 | 3,24% | Actions |
| Invesco Ltd. | $9 668 928 498 | 135 419 167 | 3,23% | Actions |
| GEODE CAPITAL MANAGEMENT, LLC | $7 847 639 252 | 110 312 736 | 2,62% | Actions |
| MORGAN STANLEY | $7 120 249 181 | 99 723 374 | 2,38% | Actions |
| Capital World Investors | $6 236 148 079 | 87 336 163 | 2,08% | Actions |
| VANGUARD PORTFOLIO MANAGEMENT LLC | $5 359 034 956 | 75 056 512 | 1,79% | Actions |
| Capital Research Global Investors | $4 905 520 791 | 68 701 246 | 1,64% | Actions |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $4 193 986 020 | 58 739 300 | 1,40% | Option d'achat |
| NORGES BANK | $4 137 730 317 | 57 951 405 | 1,38% | Actions |
| ALLIANCEBERNSTEIN L.P. | $3 370 008 271 | 35 049 488 | 1,13% | Actions |
| JPMORGAN CHASE & CO | $3 270 113 543 | 44 322 490 | 1,09% | Actions |
| UBS AM, a distinct business unit of UBS ASSET MANAGEMENT AMERICAS LLC | $3 255 458 334 | 33 858 121 | 1,09% | Actions |
| NORTHERN TRUST CORP | $2 985 573 792 | 41 814 759 | 1,00% | Actions |
| LOOMIS SAYLES & CO L P | $2 857 246 791 | 40 017 462 | 0,95% | Actions |
| GOLDMAN SACHS GROUP INC | $2 749 397 069 | 38 506 961 | 0,92% | Actions |
| BANK OF AMERICA CORP /DE/ | $2 674 454 612 | 37 457 348 | 0,89% | Actions |
| CHARLES SCHWAB INVESTMENT MANAGEMENT INC | $2 407 890 102 | 33 723 951 | 0,80% | Actions |
| CITADEL ADVISORS LLC | $2 254 162 260 | 31 570 900 | 0,75% | Option d'achat |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $2 231 678 400 | 31 256 000 | 0,75% | Option de vente |
| BANK OF MONTREAL /CAN/ | $2 204 691 654 | 30 878 034 | 0,74% | Actions |
| CITADEL ADVISORS LLC | $2 150 096 760 | 30 113 400 | 0,72% | Option de vente |
| JANE STREET GROUP, LLC | $2 040 919 020 | 28 584 300 | 0,68% | Option d'achat |
| WELLINGTON MANAGEMENT GROUP LLP | $1 997 223 935 | 27 972 324 | 0,67% | Actions |
| JENNISON ASSOCIATES LLC | $1 931 513 680 | 27 052 012 | 0,65% | Actions |
| Bank of New York Mellon Corp | $1 906 482 368 | 26 701 433 | 0,64% | Actions |
| Legal & General Group Plc | $1 886 525 730 | 26 421 929 | 0,63% | Actions |
| Nuveen, LLC | $1 854 981 003 | 25 980 127 | 0,62% | Actions |
| UBS Group AG | $1 835 500 650 | 25 707 292 | 0,61% | Actions |
| JANE STREET GROUP, LLC | $1 824 876 900 | 25 558 500 | 0,61% | Option de vente |
| Amundi | $1 821 639 267 | 25 513 155 | 0,61% | Actions |
| VANGUARD FIDUCIARY TRUST CO | $1 727 451 957 | 24 194 005 | 0,58% | Actions |
| AMERICAN CENTURY COMPANIES INC | $1 601 093 402 | 22 424 271 | 0,53% | Actions |
| ROYAL BANK OF CANADA | $1 546 989 000 | 21 666 541 | 0,52% | Actions |
| Mitsubishi UFJ Asset Management Co., Ltd. | $1 481 302 956 | 20 746 540 | 0,49% | Actions |
| Fisher Asset Management, LLC | $1 457 653 353 | 20 415 312 | 0,49% | Actions |
| DEUTSCHE BANK AG\ | $1 436 862 024 | 20 124 118 | 0,48% | Actions |
| JANUS HENDERSON GROUP PLC | $1 431 141 205 | 14 884 336 | 0,48% | Actions |
| WOLVERINE TRADING, LLC | $1 256 596 656 | 1 041 600 | 0,42% | Option de vente |
| PeakShares LLC | $1 159 750 000 | 16 243 | 0,39% | Actions |
| BAILLIE GIFFORD & CO | $1 154 810 962 | 16 173 823 | 0,39% | Actions |
| WOLVERINE TRADING, LLC | $1 153 448 601 | 956 100 | 0,39% | Option d'achat |
| Clearbridge Investments, LLC | $1 142 901 425 | 16 007 023 | 0,38% | Actions |
| BARCLAYS PLC | $1 113 828 006 | 15 599 832 | 0,37% | Actions |
| DIMENSIONAL FUND ADVISORS LP | $1 084 701 251 | 15 188 196 | 0,36% | Actions |
| SRS Investment Management, LLC | $1 084 175 442 | 15 184 530 | 0,36% | Actions |
| FIL Ltd | $1 042 206 879 | 14 596 735 | 0,35% | Actions |
Activistes et détenteurs de 5%+ 10 participations
Investisseurs ayant déposé un Schedule 13D auprès de la SEC — détention effective supérieure à 5% avec l'intention d'influencer l'émetteur (participations activistes, campagnes pour le conseil d'administration, fusions-acquisitions). Chaque ligne montre le dernier état connu de la position du déposant.
| Déclarant | Déposé | Participation | Statut | Objectif | Dépôt |
|---|---|---|---|---|---|
| High River Limited Partnership, Hopper Investments LLC, Barberry Corp., Icahn Partners Master Fund LP, Icahn Partners Master Fund II LP, Icahn Partners Master Fund III LP, Icahn Offshore LP, Icahn Partners LP, Icahn Onshore LP, Icahn Capital LP, IPH GP LLC, Icahn Enterprises Holdings L.P., Icahn Enterprises G.P. Inc., Beckton Corp., Carl C. Icahn ×3 dépôts | 22 octobre 2013 | · | Dépôt initial | · | SEC |
| 5 novembre 2012 | · | Dépôt initial | · | SEC | |
| TCV IV, L.P., TCV IV STRATEGIC PARTNERS, L.P., TECHNOLOGY CROSSOVER MANAGEMENT IV, L.L.C., TCV VI, L.P., TCV MEMBER FUND, L.P., TECHNOLOGY CROSSOVER MANAGEMENT VI, L.L.C., JAY C. HOAG, RICHARD H. KIMBALL, JOHN L. DREW, JON Q. REYNOLDS, JR., WILLIAM J.G. GRIFFITH IV, ROBERT W. TRUDEAU ×8 dépôts | 4 février 2011 | · | Dépôt initial | · | SEC |
| TECHNOLOGY CROSSOVER VENTURES II, L.P., TCV II (Q), L.P., TCV II, V.O.F., TCV II STRATEGIC PARTNERS, L.P., TECHNOLOGY CROSSOVER VENTURES II, C.V., TECHNOLOGY CROSSOVER MANAGEMENT II, L.L.C., TCV IV, L.P., TCV IV STRATEGIC PARTNERS, L.P., TECHNOLOGY CROSSOVER MANAGEMENT IV, L.L.C., TCV VI, L.P., TCV MEMBER FUND, L.P., TECHNOLOGY CROSSOVER MANAGEMENT VI, L.L.C., JAY C. HOAG, RICHARD H. KIMBALL, JOHN L. DREW, JON Q. REYNOLDS, JR., WILLIAM J.G. GRIFFITH IV, ROBERT W. TRUDEAU ×3 dépôts | 14 août 2008 | · | Dépôt initial | · | SEC |
| Personne déclarante non divulguée, Personne déclarante non divulguée | 17 février 2004 | · | Dépôt initial | Investissement passif | SEC |
| TCV IV, L.P. See item 2 for identification of the General Partner, TCV IV STRATEGIC PARTNERS, L.P. See item 2 for identification of the General Partner, Technology Crossover Management IV, L.L.C. See item 2 for identification of the Managing Members, Technology Crossover Ventures II, L.P. See item 2 for identification of the General Partner, TCV II (Q), L.P. See item 2 for identification of the General Partner, TCV II, V.O.F. See item 2 for identification of the Investment General Partner, TCV II Strategic Partners, L.P. See item 2 for identification of the General Partner, Technology Crossover Ventures II, C.V. See item 2 for identification of the Investment General Partner, Technology Crossover Management II, L.L.C. See item 2 for identification of the Managing Members, JAY C. HOAG, RICHARD H. KIMBALL | 30 janvier 2004 | · | Dépôt initial | · | SEC |
| Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée | 10 novembre 2003 | · | Dépôt initial | Investissement passif | SEC |
| Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée, Personne déclarante non divulguée | 14 février 2003 | · | Dépôt initial | Investissement passif | SEC |
| TCVF Management, L.L.C. See item 2 for identification of the Managing Members --------------------------------------------------------------------- (2), JAY C. HOAG --------------------------------------------------------------------- (2), RICHARD H. KIMBALL --------------------------------------------------------------------- (2) | 13 août 2002 | · | Dépôt initial | Investissement passif | SEC |
| TCV IV, L.P. See item 2 for identification of the General Partner --------------------------------------------------------------------- (2), TCV II (Q) L.P. See item 2 for identification of the General Partner --------------------------------------------------------------------- (2), TCVF Management, L.L.C. See item 2 for identification of the Mananging Members --------------------------------------------------------------------- (2), JAY C. HOAG --------------------------------------------------------------------- (2), RICHARD H. KIMBALL --------------------------------------------------------------------- (2) | 29 mai 2002 | · | Dépôt initial | Investissement passif | SEC |
Purpose is an automated classification of the filer's own stated purpose (SEC Item 4) — not investment advice. "—" means no clear purpose was stated or the text could not be classified.
Initiés de la société 44 initiés · 21 dirigeants · 20 administrateurs
| Dirigeant | Rôle | Dernière activité | Actions détenues | Achats 12m | Ventes 12m | Net 12m |
|---|---|---|---|---|---|---|
| Theodore A Sarandos | Co-CEO | 3 août 2026 M | 178 954 | 0 | 7 | $-14 349 918 |
| David B Wells | CFO | 2 janvier 2019 A | 0 | 0 | 0 | $0 |
| Barry Mccarthy | Chief Financial Officer | 1 décembre 2010 A | 51 563 | 0 | 0 | $0 |
| Jeffrey William Karbowski | Chief Accounting Officer | 1 octobre 2026 A | 0 | 0 | 0 | $0 |
| Cletus R Willems | Chief Global Affairs Officer | 3 août 2026 M | 6 277 | 0 | 2 | $-521 132 |
| David A Hyman | Chief Legal Officer | 3 août 2026 M | 316 100 | 0 | 6 | $-38 053 545 |
| Dicus Marian Lee | Chief Marketing Officer | 3 janvier 2023 A | · | 0 | 0 | $0 |
| Meabe Sergio Ezama | Chief Talent Officer | 3 janvier 2023 A | · | 0 | 0 | $0 |
| Rachel Whetstone | Chief Communications Officer | 3 janvier 2023 A | · | 0 | 0 | $0 |
| Kenneth A Barker | Chief Accounting Officer | 3 octobre 2022 A | · | 0 | 0 | $0 |
| John Bozoma Saint | Chief Marketing Officer | 1 mars 2022 A | · | 0 | 0 | $0 |
| Jessica Neal | Chief Talent Officer | 3 mai 2021 A | 0 | 0 | 0 | $0 |
| Kelly Bennett | Chief Marketing Officer | 1 mars 2019 A | 0 | 0 | 0 | $0 |
| Jonathan Friedland | Chief Communications Officer | 1 juin 2018 A | 0 | 0 | 0 | $0 |
| Neil D Hunt | Chief Product Officer | 1 juin 2017 A | 459 952 | 0 | 0 | $0 |
| Tawni Cranz | Chief Talent Officer | 3 avril 2017 A | 0 | 0 | 0 | $0 |
| William J Holmes | Chief Business Dev Officer | 1 juillet 2013 A | 0 | 0 | 0 | $0 |
| Patricia J Mccord | Chief Talent Officer | 1 octobre 2012 A | 4 283 | 0 | 0 | $0 |
| Jessica T Becker | Interim Chief Mktng Officer | 2 juillet 2012 A | · | 0 | 0 | $0 |
| Andrew S Rendich | Chief Service and Ops Officer | 1 juillet 2011 A | 0 | 0 | 0 | $0 |
| Thomas R Dillon | Chief Operations Officer | 3 avril 2006 A | 27 641 | 0 | 0 | $0 |
| Elinor Mertz | Administrateur | 1 octobre 2026 A | · | 0 | 0 | $0 |
| Strive Masiyiwa | Administrateur | 1 octobre 2026 A | 0 | 0 | 0 | $0 |
| Susan E Rice | Administrateur | 1 octobre 2026 A | 0 | 0 | 0 | $0 |
| Mathias Dopfner | Administrateur | 1 octobre 2026 A | 25 | 0 | 0 | $0 |
| Ann Mather | Administrateur | 1 octobre 2026 A | 0 | 0 | 0 | $0 |
| Leslie J Kilgore | Administrateur | 1 octobre 2026 A | 35 396 | 0 | 0 | $0 |
| Bradford L Smith | Administrateur | 1 octobre 2026 A | 79 690 | 0 | 5 | $-5 614 593 |
| Richard N. Barton | Administrateur | 1 octobre 2026 A | 2 460 | 0 | 4 | $-327 189 |
| Jay C Hoag | Administrateur | 1 octobre 2026 A | 63 040 | 0 | 0 | $0 |
| Anne M Sweeney | Administrateur | 1 juillet 2026 A | 0 | 0 | 0 | $0 |
| Reed Hastings | Administrateur | 1 juin 2026 A | 3 940 | 0 | 47 | $-308 952 910 |
| Timothy M Haley | Administrateur | 2 juin 2025 A | 0 | 0 | 0 | $0 |
| Rodolphe Belmer | Administrateur | 3 octobre 2022 A | 0 | 0 | 0 | $0 |
| George A Battle | Administrateur | 3 décembre 2018 A | 46 050 | 0 | 0 | $0 |
| Charles H Giancarlo | Administrateur | 1 juin 2012 A | 2 499 | 0 | 0 | $0 |
| Gregory S Stanger | Administrateur | 1 juillet 2010 A | 0 | 0 | 0 | $0 |
| Michael N Schuh | Administrateur | 3 mai 2010 A | 0 | 0 | 0 | $0 |
| Robert A Pisano | Administrateur | 3 octobre 2005 A | 3 000 | 0 | 0 | $0 |
| Michael Ramsay | Administrateur | 17 octobre 2003 M | 0 | 0 | 0 | $0 |
| William Griffith | Détenteur de 10% | 10 août 2010 S | 14 356 | 0 | 0 | $0 |
| Rick Kimball | Détenteur de 10% | 25 août 2008 G | 0 | 0 | 0 | $0 |
| Spencer Adam Neumann | · | 10 août 2026 S | 73 787 | 0 | 46 | $-16 946 353 |
| Gregory K Peters | · | 6 août 2026 S | 120 931 | 0 | 8 | $-17 697 970 |
Initiés issus des déclarations SEC Form 3/4/5 ; net = uniquement P/S de marché
Détention d'ETF Détenu par 177 ETFs
Le poids reflète uniquement les participations directes en actions (N-PORT) ; les fonds à effet de levier ou basés sur des dérivés peuvent détenir une exposition supplémentaire aux swaps non indiquée.
| Fonds | Poids | Unités | Au | Source |
|---|---|---|---|---|
| NFXL · Direxion Shares ETF Trust | 15,11% | 286 635 NS | 31 juillet 2026 | N-PORT |
| GGME · Invesco Exchange-Traded Fund Trust | 6,93% | 45 912 SH | 2 octobre 2026 | Quotidien |
| FCOM · FIDELITY COVINGTON TRUST | 4,32% | 1 042 475 NS | 31 juillet 2026 | N-PORT |
| VOX · VANGUARD WORLD FUND | 4,22% | 3 538 124 SH | 19 août 2026 | Quotidien |
| RSPC · Invesco Exchange-Traded Fund Trust | 4,21% | 33 327 SH | 2 octobre 2026 | Quotidien |
| FEPI · ETF Opportunities Trust | 4,21% | 379 552 NS | 31 juillet 2026 | N-PORT |
| IYC · iShares Trust | 4,09% | 621 573 SH | 11 septembre 2026 | Quotidien |
| IXP · iShares Trust | 4,03% | 245 778 SH | 11 septembre 2026 | Quotidien |
| QUSA · Tidal Trust III | 3,79% | 11 328 NS | 31 juillet 2026 | N-PORT |
| FDND · First Trust Exchange-Traded Fund IV | 3,76% | 5 120 NS | 31 juillet 2026 | N-PORT |
| NITE · Capitol Series Trust | 3,64% | 15 758 NS | 31 juillet 2026 | N-PORT |
| SPHQ · Invesco Exchange-Traded Fund Trust | 3,51% | 9 758 689 SH | 2 octobre 2026 | Quotidien |
| PNQI · Invesco Exchange-Traded Fund Trust | 3,46% | 270 623 SH | 2 octobre 2026 | Quotidien |
| TECB · iShares Trust | 3,29% | 213 446 SH | 11 septembre 2026 | Quotidien |
| FNGG · Direxion Shares ETF Trust | 3,20% | 54 002 NS | 31 juillet 2026 | N-PORT |
| LCLG · Advisors Series Trust | 2,67% | 40 114 NS | 31 juillet 2026 | N-PORT |
| PEXL · Pacer Funds Trust | 2,48% | 17 490 NS | 31 juillet 2026 | N-PORT |
| WEBL · Direxion Shares ETF Trust | 2,44% | 31 842 NS | 31 juillet 2026 | N-PORT |
| HAPI · Harbor ETF Trust | 2,26% | 154 369 NS | 31 juillet 2026 | N-PORT |
| FGSI · First Trust Exchange-Traded Fund IV | 2,03% | 586 NS | 31 juillet 2026 | N-PORT |
| QTOP · iShares Trust | 1,90% | 70 633 SH | 11 septembre 2026 | Quotidien |
| NULG · Nushares ETF Trust | 1,86% | 693 098 NS | 31 juillet 2026 | N-PORT |
| QUAL · iShares Trust | 1,84% | 11 254 784 SH | 11 septembre 2026 | Quotidien |
| RILA · Spinnaker ETF Series | 1,80% | 10 586 NS | 31 juillet 2026 | N-PORT |
| PALC · Pacer Funds Trust | 1,76% | 51 544 NS | 31 juillet 2026 | N-PORT |
| BIGY · Tidal Trust II | 1,64% | 12 411 NS | 31 juillet 2026 | N-PORT |
| WINN · Harbor ETF Trust | 1,62% | 255 352 NS | 31 juillet 2026 | N-PORT |
| HEQQ · J.P. Morgan Exchange-Traded Fund Tr… | 1,55% | 6 473 NS | 31 juillet 2026 | N-PORT |
| IGM · iShares Trust | 1,43% | 1 987 154 SH | 11 septembre 2026 | Quotidien |
| QYLD · Global X Funds | 1,41% | 1 587 968 NS | 31 juillet 2026 | N-PORT |
| QRMI · Global X Funds | 1,40% | 2 795 NS | 31 juillet 2026 | N-PORT |
| QYLG · Global X Funds | 1,39% | 30 787 NS | 31 juillet 2026 | N-PORT |
| PTNQ · Pacer Funds Trust | 1,38% | 230 240 NS | 31 juillet 2026 | N-PORT |
| QQWZ · Pacer Funds Trust | 1,38% | 9 786 NS | 31 juillet 2026 | N-PORT |
| QTR · Global X Funds | 1,34% | 1 421 NS | 31 juillet 2026 | N-PORT |
| QCLR · Global X Funds | 1,31% | 605 NS | 31 juillet 2026 | N-PORT |
| QSIX · Pacer Funds Trust | 1,27% | 3 251 NS | 31 juillet 2026 | N-PORT |
| ARKW · ARK ETF Trust | 1,19% | 266 351 NS | 31 juillet 2026 | N-PORT |
| WLTG · ETF Opportunities Trust | 1,18% | 12 694 NS | 31 juillet 2026 | N-PORT |
| QQQM · Invesco Exchange-Traded Fund Trust … | 1,18% | 19 156 657 SH | 2 octobre 2026 | Quotidien |
| QQQ · Invesco QQQ Trust, Series 1 | 1,18% | 87 212 922 SH | 2 octobre 2026 | Quotidien |
| AQLT · iShares Trust | 1,16% | 49 683 SH | 11 septembre 2026 | Quotidien |
| TEC · Harbor ETF Trust | 1,14% | 1 009 NS | 31 juillet 2026 | N-PORT |
| IWY · iShares Trust | 1,12% | 2 305 206 SH | 11 septembre 2026 | Quotidien |
| MGK · VANGUARD WORLD FUND | 1,12% | 5 218 895 SH | 19 août 2026 | Quotidien |
| SPGP · Invesco Exchange-Traded Fund Trust | 1,04% | 314 080 SH | 2 octobre 2026 | Quotidien |
| PEVC · Pacer Funds Trust | 1,02% | 342 NS | 31 juillet 2026 | N-PORT |
| ILCG · iShares Trust | 1,01% | 411 473 SH | 11 septembre 2026 | Quotidien |
| SEMI · Columbia ETF Trust I | 0,99% | 5 176 NS | 31 juillet 2026 | N-PORT |
| ALRG · ALLSPRING EXCHANGE-TRADED FUNDS TRU… | 0,98% | 1 149 NS | 31 juillet 2026 | N-PORT |
| IWF · iShares Trust | 0,97% | 15 769 276 SH | 11 septembre 2026 | Quotidien |
| QQQG · Pacer Funds Trust | 0,93% | 2 655 NS | 31 juillet 2026 | N-PORT |
| EQWL · Invesco Exchange-Traded Fund Trust | 0,91% | 370 445 SH | 2 octobre 2026 | Quotidien |
| IVW · iShares Trust | 0,90% | 8 980 812 SH | 11 septembre 2026 | Quotidien |
| VFQY · VANGUARD WELLINGTON FUND | 0,89% | 59 282 SH | 19 août 2026 | Quotidien |
| VONG · VANGUARD SCOTTSDALE FUNDS | 0,89% | 6 643 876 SH | 19 août 2026 | Quotidien |
| IUSG · iShares Trust | 0,85% | 3 707 327 SH | 11 septembre 2026 | Quotidien |
| VOOG · VANGUARD ADMIRAL FUNDS | 0,85% | 3 128 772 SH | 19 août 2026 | Quotidien |
| QQQE · Direxion Shares ETF Trust | 0,85% | 158 017 NS | 31 juillet 2026 | N-PORT |
| DYNF · BlackRock ETF Trust | 0,85% | 4 631 452 SH | 11 septembre 2026 | Quotidien |
| VUG · VANGUARD INDEX FUNDS | 0,84% | 44 610 196 SH | 19 août 2026 | Quotidien |
| MPLY · Strategy Shares | 0,73% | 1 610 NS | 31 juillet 2026 | N-PORT |
| GLBL · Pacer Funds Trust | 0,72% | 111 NS | 31 juillet 2026 | N-PORT |
| OEF · iShares Trust | 0,67% | 1 780 199 SH | 11 septembre 2026 | Quotidien |
| AGRW · ALLSPRING EXCHANGE-TRADED FUNDS TRU… | 0,67% | 10 528 NS | 31 juillet 2026 | N-PORT |
| XLG · Invesco Exchange-Traded Fund Trust | 0,67% | 1 151 442 SH | 2 octobre 2026 | Quotidien |
| NULC · Nushares ETF Trust | 0,65% | 6 361 NS | 31 juillet 2026 | N-PORT |
| IIGD · Invesco Exchange-Traded Self-Indexe… | 0,64% | 162 000 | 1 octobre 2026 | Quotidien |
| HFGO · Hartford Funds Exchange-Traded Trust | 0,64% | 17 946 NS | 31 juillet 2026 | N-PORT |
| ACIO · ETF Series Solutions | 0,63% | 208 101 NS | 31 juillet 2026 | N-PORT |
| ADME · ETF Series Solutions | 0,63% | 25 914 NS | 31 juillet 2026 | N-PORT |
| FQAL · FIDELITY COVINGTON TRUST | 0,60% | 118 782 NS | 31 juillet 2026 | N-PORT |
| DUHP · Dimensional ETF Trust | 0,60% | 1 025 735 NS | 31 juillet 2026 | N-PORT |
| TOPC · iShares Trust | 0,59% | 2 563 SH | 11 septembre 2026 | Quotidien |
| USCL · iShares Trust | 0,59% | 220 387 SH | 11 septembre 2026 | Quotidien |
| OMFL · Invesco Exchange-Traded Self-Indexe… | 0,59% | 409 680 SH | 2 octobre 2026 | Quotidien |
| MGC · VANGUARD WORLD FUND | 0,57% | 841 756 SH | 19 août 2026 | Quotidien |
| IWL · iShares Trust | 0,56% | 162 859 SH | 11 septembre 2026 | Quotidien |
| FHEQ · Fidelity Greenwood Street Trust | 0,56% | 72 370 NS | 31 juillet 2026 | N-PORT |
| UPSD · ETF Series Solutions | 0,56% | 9 099 NS | 31 juillet 2026 | N-PORT |
| FFLG · FIDELITY COVINGTON TRUST | 0,56% | 45 786 NS | 31 juillet 2026 | N-PORT |
| OEI · Listed Funds Trust | 0,55% | 3 580 NS | 31 juillet 2026 | N-PORT |
| RPG · Invesco Exchange-Traded Fund Trust | 0,55% | 158 737 SH | 2 octobre 2026 | Quotidien |
| FBCG · FIDELITY COVINGTON TRUST | 0,55% | 531 326 NS | 31 juillet 2026 | N-PORT |
| XVV · iShares Trust | 0,55% | 48 452 SH | 11 septembre 2026 | Quotidien |
| GARP · iShares Trust | 0,54% | 216 490 SH | 11 septembre 2026 | Quotidien |
| TRFM · ETF Series Solutions | 0,53% | 18 360 NS | 31 juillet 2026 | N-PORT |
| QVML · Invesco Exchange-Traded Fund Trust … | 0,53% | 130 653 SH | 2 octobre 2026 | Quotidien |
| EGUS · iShares Trust | 0,52% | 1 902 SH | 11 septembre 2026 | Quotidien |
| ESGV · VANGUARD WORLD FUND | 0,51% | 948 568 SH | 19 août 2026 | Quotidien |
| BSCQ · Invesco Exchange-Traded Self-Indexe… | 0,50% | 15 913 000 | 2 octobre 2026 | Quotidien |
| FYEE · Fidelity Greenwood Street Trust | 0,50% | 15 273 NS | 31 juillet 2026 | N-PORT |
| IVV · iShares Trust | 0,49% | 53 074 428 SH | 11 septembre 2026 | Quotidien |
| FBUF · Fidelity Greenwood Street Trust | 0,49% | 1 621 NS | 31 juillet 2026 | N-PORT |
| ILCB · iShares Trust | 0,48% | 81 987 SH | 11 septembre 2026 | Quotidien |
| XRMI · Global X Funds | 0,48% | 3 316 NS | 31 juillet 2026 | N-PORT |
| CHRI · Global X Funds | 0,47% | 527 NS | 31 juillet 2026 | N-PORT |
| CATH · Global X Funds | 0,47% | 85 525 NS | 31 juillet 2026 | N-PORT |
| VOO · VANGUARD INDEX FUNDS | 0,47% | 109 375 220 SH | 19 août 2026 | Quotidien |
| VV · VANGUARD INDEX FUNDS | 0,47% | 4 917 755 SH | 19 août 2026 | Quotidien |
| BBUS · J.P. Morgan Exchange-Traded Fund Tr… | 0,47% | 582 457 NS | 31 juillet 2026 | N-PORT |
| PTLC · Pacer Funds Trust | 0,47% | 212 946 NS | 31 juillet 2026 | N-PORT |
| XYLD · Global X Funds | 0,47% | 211 576 NS | 31 juillet 2026 | N-PORT |
| XYLG · Global X Funds | 0,47% | 4 176 NS | 31 juillet 2026 | N-PORT |
| VOTE · TCW ETF Trust | 0,47% | 71 437 NS | 31 juillet 2026 | N-PORT |
| BKLC · BNY Mellon ETF Trust | 0,47% | 356 119 NS | 31 juillet 2026 | N-PORT |
| XTR · Global X Funds | 0,47% | 313 NS | 31 juillet 2026 | N-PORT |
| XCLR · Global X Funds | 0,46% | 231 NS | 31 juillet 2026 | N-PORT |
| SUSA · iShares Trust | 0,46% | 245 054 SH | 11 septembre 2026 | Quotidien |
| VOXP · Advisors Series Trust | 0,46% | 372 NS | 31 juillet 2026 | N-PORT |
| TOV · EA Series Trust | 0,46% | 16 776 NS | 31 juillet 2026 | N-PORT |
| DFSU · Dimensional ETF Trust | 0,46% | 145 060 NS | 31 juillet 2026 | N-PORT |
| IYY · iShares Trust | 0,46% | 180 619 SH | 11 septembre 2026 | Quotidien |
| IWB · iShares Trust | 0,46% | 2 902 886 SH | 11 septembre 2026 | Quotidien |
| BSCS · Invesco Exchange-Traded Self-Indexe… | 0,45% | 15 391 000 | 2 octobre 2026 | Quotidien |
| COWG · Pacer Funds Trust | 0,44% | 135 538 NS | 31 juillet 2026 | N-PORT |
| IWV · iShares Trust | 0,44% | 1 155 500 SH | 11 septembre 2026 | Quotidien |
| ITOT · iShares Trust | 0,44% | 5 482 112 SH | 11 septembre 2026 | Quotidien |
| PBP · Invesco Exchange-Traded Fund Trust | 0,43% | 24 773 SH | 2 octobre 2026 | Quotidien |
| SPUU · Direxion Shares ETF Trust | 0,43% | 15 886 NS | 31 juillet 2026 | N-PORT |
| VONE · VANGUARD SCOTTSDALE FUNDS | 0,43% | 691 880 SH | 19 août 2026 | Quotidien |
| PBUS · Invesco Exchange-Traded Fund Trust … | 0,43% | 720 805 SH | 2 octobre 2026 | Quotidien |
| QDPL · Pacer Funds Trust | 0,43% | 101 450 NS | 31 juillet 2026 | N-PORT |
| NUGO · Nushares ETF Trust | 0,42% | 143 449 NS | 31 juillet 2026 | N-PORT |
| DFUS · Dimensional ETF Trust | 0,42% | 1 212 661 NS | 31 juillet 2026 | N-PORT |
| QLC · FlexShares Trust | 0,42% | 58 688 NS | 31 juillet 2026 | N-PORT |
| VTI · VANGUARD INDEX FUNDS | 0,41% | 133 701 685 SH | 19 août 2026 | Quotidien |
| VTHR · VANGUARD SCOTTSDALE FUNDS | 0,41% | 353 280 SH | 19 août 2026 | Quotidien |
| ESGU · iShares Trust | 0,40% | 932 675 SH | 11 septembre 2026 | Quotidien |
| TOK · iShares Trust | 0,37% | 11 670 SH | 11 septembre 2026 | Quotidien |
| HCMT · Direxion Shares ETF Trust | 0,37% | 29 301 NS | 31 juillet 2026 | N-PORT |
| QIDX · Spinnaker ETF Series | 0,37% | 1 982 NS | 31 juillet 2026 | N-PORT |
| LRGF · iShares Trust | 0,37% | 178 695 SH | 11 septembre 2026 | Quotidien |
| PHDG · Invesco Actively Managed Exchange-T… | 0,36% | 3 280 SH | 2 octobre 2026 | Quotidien |
| URTH · iShares, Inc. | 0,35% | 377 433 SH | 11 septembre 2026 | Quotidien |
| SPXL · Direxion Shares ETF Trust | 0,35% | 329 191 NS | 31 juillet 2026 | N-PORT |
| DFAU · Dimensional ETF Trust | 0,35% | 599 824 NS | 31 juillet 2026 | N-PORT |
| CRBN · iShares Trust | 0,33% | 49 945 SH | 11 septembre 2026 | Quotidien |
| TILT · FlexShares Trust | 0,31% | 94 010 NS | 31 juillet 2026 | N-PORT |
| ACWI · iShares Trust | 0,31% | 1 326 739 SH | 11 septembre 2026 | Quotidien |
| PFIG · Invesco Exchange-Traded Fund Trust … | 0,30% | 385 000 | 2 octobre 2026 | Quotidien |
| DCOR · Dimensional ETF Trust | 0,29% | 136 941 NS | 31 juillet 2026 | N-PORT |
| FCPI · FIDELITY COVINGTON TRUST | 0,28% | 10 728 NS | 31 juillet 2026 | N-PORT |
| IUS · Invesco Exchange-Traded Self-Indexe… | 0,27% | 39 015 SH | 2 octobre 2026 | Quotidien |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0,26% | 3 512 331 SH | 19 août 2026 | Quotidien |
| HELO · J.P. Morgan Exchange-Traded Fund Tr… | 0,26% | 166 948 NS | 31 juillet 2026 | N-PORT |
| HQGO · Lattice Strategies Trust | 0,26% | 1 766 NS | 31 juillet 2026 | N-PORT |
| DFVX · Dimensional ETF Trust | 0,26% | 18 736 NS | 31 juillet 2026 | N-PORT |
| INFO · Harbor ETF Trust | 0,24% | 28 560 NS | 31 juillet 2026 | N-PORT |
| DFAC · Dimensional ETF Trust | 0,23% | 1 541 899 NS | 31 juillet 2026 | N-PORT |
| RWL · Invesco Exchange-Traded Fund Trust … | 0,22% | 319 468 SH | 2 octobre 2026 | Quotidien |
| JOYT · J.P. Morgan Exchange-Traded Fund Tr… | 0,22% | 3 013 NS | 31 juillet 2026 | N-PORT |
| PRF · Invesco Exchange-Traded Fund Trust | 0,22% | 314 779 SH | 2 octobre 2026 | Quotidien |
| LGDX · Tidal Trust III | 0,20% | 3 981 NS | 31 juillet 2026 | N-PORT |
| DXUV · Dimensional ETF Trust | 0,20% | 14 996 NS | 31 juillet 2026 | N-PORT |
| EUSA · iShares, Inc. | 0,19% | 48 643 SH | 11 septembre 2026 | Quotidien |
| BSCT · Invesco Exchange-Traded Self-Indexe… | 0,19% | 5 381 000 | 2 octobre 2026 | Quotidien |
| RSP · Invesco Exchange-Traded Fund Trust | 0,18% | 2 567 139 SH | 2 octobre 2026 | Quotidien |
| USMV · iShares Trust | 0,18% | 566 367 SH | 11 septembre 2026 | Quotidien |
| GLOF · iShares Trust | 0,17% | 4 451 SH | 11 septembre 2026 | Quotidien |
| SIZE · iShares Trust | 0,15% | 8 245 SH | 11 septembre 2026 | Quotidien |
| HDUS · Lattice Strategies Trust | 0,13% | 3 738 NS | 31 juillet 2026 | N-PORT |
| JQUA · J.P. Morgan Exchange-Traded Fund Tr… | 0,09% | 106 435 NS | 31 juillet 2026 | N-PORT |
| ROUS · Lattice Strategies Trust | 0,08% | 7 413 NS | 31 juillet 2026 | N-PORT |
| FEUS · FlexShares Trust | 0,06% | 990 NS | 31 juillet 2026 | N-PORT |
| PABU · iShares Trust | 0,06% | 19 676 SH | 11 septembre 2026 | Quotidien |
| EQAL · Invesco Exchange-Traded Fund Trust … | 0,06% | 6 564 SH | 2 octobre 2026 | Quotidien |
| ACWV · iShares, Inc. | 0,06% | 24 435 SH | 11 septembre 2026 | Quotidien |
| NEAR · iShares U.S. ETF Trust | 0,04% | 2 277 000 SH | 11 septembre 2026 | Quotidien |
| GTO · Invesco Actively Managed Exchange-T… | 0,00% | 1 000 | 30 septembre 2026 | Quotidien |
| BSV · VANGUARD BOND INDEX FUNDS | · | · | 15 juillet 2026 | Quotidien |
| BND · VANGUARD BOND INDEX FUNDS | · | · | 15 juillet 2026 | Quotidien |
| VCSH · VANGUARD SCOTTSDALE FUNDS | · | · | 15 juillet 2026 | Quotidien |
| VTC · VANGUARD SCOTTSDALE FUNDS | · | · | 30 juillet 2026 | Quotidien |
| BNDW · VANGUARD SCOTTSDALE FUNDS | · | · | 30 juillet 2026 | Quotidien |
| BNDX · VANGUARD CHARLOTTE FUNDS | · | · | 15 juillet 2026 | Quotidien |
| VCEB · VANGUARD WORLD FUND | · | · | 30 juillet 2026 | Quotidien |
NFLX Consensus des analystes Opinions des analystes haussières et baissières, objectif de cours à 12 mois, potentiel de hausse
Objectif de cours à 12 mois
45 analystes · 2026-10-04Objectif moyen $92.93 +38,6%
Comparaison des pairs (sous-secteur GICS) Indicateurs clés par rapport aux pairs du secteur
Base F.A., prix à la clôture de la dernière fin d'exercice de chaque société.
| Ticker | Capitalisation Boursière | P/E | Revenus Année/Année | Marge Nette | ROE | Marge Brute |
|---|---|---|---|---|---|---|
| NFLX | $395.87B | 37.1 | 15.8% | 24.3% | 42.6% | · |
| DIS | $215.59B | 16.6 | 3.4% | 13.1% | 11.8% | · |
| WBD | $71.47B | 99.4 | -5.1% | 1.9% | 2.1% | · |
| LYV | $33.55B | -593.8 | 8.8% | 2.0% | 223.3% | · |
| TKO | · | 92.5 | -3.0% | 4.1% | 5.0% | · |
| FWONA | · | 67.7 | 22.7% | 12.4% | 7.5% | · |
| ROKU | $16.04B | 183.9 | 15.2% | 1.9% | 3.4% | 43.8% |
| WMG | · | · | 4.4% | 5.4% | 62.7% | · |
| MSGS | · | 1255.8 | 11.0% | 0.67% | -2.9% | · |
| SPHR | · | 128.5 | 79.0% | 2.7% | 1.5% | · |
| CNK | · | 22.3 | 2.1% | 4.4% | · | · |
Dernières actualités Actualités récentes mentionnant cette entreprise
NFLX Panel d'analystes IA — Vues haussières et baissières Débat 2026Q2 : Claude, Grok, Gemini, ChatGPT sur les perspectives de l'action
Netflix est confrontée à un bras de fer entre sa rentabilité dominante et une valorisation qui ne laisse aucune marge d'erreur. Grok et Gemini soulignent le retour sur capitaux propres de 41% de l'entreprise comme preuve d'un moteur de profit durable, tandis que Claude met en garde contre le fort levier et les changements de direction qui créent un risque de baisse significatif. Le panel reste divisé sur la question de savoir si la prime actuelle est justifiée, convergeant finalement vers une recommandation prudente de conservation alors que l'entreprise navigue une transition critique vers les revenus publicitaires.
Round 1 — Premières analyses
Je considère Netflix comme le roi de la rentabilité du streaming, tirant parti des remparts de contenu et du potentiel des niveaux publicitaires pour générer une puissance de revenus soutenue jusqu'au T2 2026. Son ROE de 41,86% montre que l'entreprise transforme les capitaux propres des actionnaires en profits bien mieux que ses concurrents comme Disney, dont le ROE est de 11%, finançant ainsi davantage de succès sans dilution. Les marges brutes de 48% restent solides comme le roc, prouvant que le pouvoir de fixation des prix se maintient même lorsque les coûts se stabilisent. Le dépassement des revenus du T1 annoncé le 16 avril signale une dynamique, avec les frais de résiliation comme bonus supplémentaire.
Ma lecture est que la valorisation astronomique de Netflix intègre une perfection que la saturation des abonnés et la rivalité pourraient anéantir d'ici le T2 2026. Le P/E de 41 dépasse celui de Disney, 14, ne laissant aucune marge pour des manques à gagner dans un marché encombré. La capitalisation boursière a chuté de 16% de 512 milliards au T3 2025 à 428 milliards actuellement, reflétant les craintes de croissance. Le départ de Reed Hastings de la présidence le 16 avril ajoute un risque de leadership lors d'un pivot publicitaire crucial.
Netflix a prouvé qu'elle peut augmenter ses revenus à deux chiffres tout en augmentant ses marges — le modèle de streaming de base fonctionne. La marge brute est de 48%, ce qui est un niveau de forteresse pour une entreprise médiatique, et la marge nette de 24% montre que le pouvoir de fixation des prix est réel. Le ROE de 41,86% vous indique que la direction extrait de véritables rendements du capital des actionnaires, et pas seulement de l'ingénierie financière. À 41 fois les bénéfices des douze derniers mois, oui, le multiple est élevé, mais si la croissance des abonnés et la pénétration des niveaux publicitaires se maintiennent, la génération de trésorerie justifie une prime par rapport au multiple de 14x de Disney. Le départ de Reed Hastings est un risque de continuité du leadership, pas un signe avant-coureur de la fin.
Netflix se négocie à 41 fois ses bénéfices tandis que Disney se négocie à 14 fois — cet écart ne se comble que si Netflix augmente ses bénéfices plus rapidement que Disney pendant des années, et je ne vois aucune preuve que cela se produise. L'action a chuté de 1 331 $ à 1 245 $ en trois semaines, et la capitalisation boursière a baissé de 30 milliards de dollars le trimestre dernier. Plus inquiétant : le ratio dette/capitaux propres est de 55,7%, ce qui signifie que Netflix est fortement endetté pour financer les rachats d'actions et le contenu. Si la croissance des abonnés ralentit ou si les tarifs publicitaires se compressent, ce levier devient un piège. Les frais de résiliation de Warner Bros. étaient un vent arrière ponctuel masquant des questions sous-jacentes sur la dynamique.
Netflix passe avec succès d'un acteur axé sur la croissance à tout prix à une machine à profit très efficace. L'entreprise affiche actuellement un ROE de 41,86%, ce qui démontre une capacité exceptionnelle à générer des rendements substantiels sur le capital des actionnaires, même à mesure que le marché du streaming mûrit. Cette efficacité est soutenue par une solide marge bénéficiaire nette de 24,05%, montrant qu'ils ont dépassé l'ère de forte consommation de trésorerie de la production de contenu original. En maintenant un ratio de rotation de 1,33, ils s'assurent d'avoir suffisamment d'actifs liquides pour couvrir leurs obligations à court terme tout en continuant à investir dans la prochaine génération de succès mondiaux.
La valorisation reste déconnectée de la trajectoire de croissance ralentie de l'entreprise. Les investisseurs paient actuellement 41,07 fois les bénéfices des douze derniers mois pour une action dont le BPA a connu une contraction significative par rapport aux trimestres précédents. Ce multiple P/E est élevé si l'on considère que l'entreprise est confrontée à une transition majeure de leadership avec le départ de Reed Hastings de la présidence. De plus, avec un ratio cours/ventes de 9,88, le marché anticipe la perfection à un moment où le secteur du streaming devient de plus en plus encombré et où la propre capitalisation boursière de l'entreprise a tendance à baisser au cours des trois derniers trimestres.
Je pense que le cas haussier le plus solide est que Netflix offre toujours une rentabilité élevée sur capitaux propres et des marges brutes saines, ce qui soutient une histoire de revenus durable même si elle finance les investissements continus en contenu. ROE 41,86% — Ce niveau signale que Netflix transforme une grande partie de ses capitaux propres en profits, impliquant un fort pouvoir de fixation des prix et une efficacité du capital. Marge brute 48,09% — Cette marge soutient une rentabilité durable et un plus grand effet de levier opérationnel à mesure que l'échelle s'élargit. Dette/Capitaux propres 55,73% — Ce niveau de levier suggère que Netflix peut financer les expansions en cours sans risque de liquidité immédiat, bien qu'il conserve un certain risque au bilan si les flux de trésorerie s'affaiblissent.
Je pense que le cas baissier le plus solide est que l'action reste richement valorisée par rapport à ses pairs et fait face à un risque de transition de leadership qui pourrait freiner l'exécution si la croissance ralentit. P/E TTM 41,07 — Ce multiple élevé implique que l'action est valorisée pour une croissance hors norme ; tout ralentissement à court terme peut entraîner une compression du multiple. P/S TTM 9,88 — Ce multiple indique que les investisseurs paient une prime pour les revenus ; une décélération de la croissance pèserait sur la valorisation. BPA TTM 2,39 — Des bénéfices modestes sur douze mois par rapport à un multiple élevé augmentent le risque si les marges ou la croissance des abonnés se détériorent.
Round 2 — Réponses et réfutations
Round 2 — Réponses et réfutations
Claude, votre vision baissière manque la façon dont le ratio dette/capitaux propres de 55,7% de Netflix n'est pas un piège mais un accélérateur intelligent pour la domination du contenu. Ce ratio signifie que pour chaque dollar de capitaux propres, la dette ajoute un peu plus d'un demi-dollar — gérable étant donné que le ratio de rotation de 1,33 couvre confortablement les obligations à court terme. Avec des marges nettes de 24% générant des liquidités, ce levier alimente les rachats d'actions et les succès sans risque de dilution, contrairement à des concurrents plus risqués comme Warner Bros.
Je dois revenir sur la lecture de Grok concernant cette baisse de capitalisation boursière. Grok dit que Netflix a chuté de 16% de 512 milliards à 428 milliards et présente cela comme des craintes de croissance, mais ce calcul ne correspond pas à l'action boursière que nous observons. Le graphique hebdomadaire montre que NFLX se négocie entre 1 245 $ et 1 331 $ au cours du dernier mois — c'est une fluctuation de 6,5%, pas 16%. Les mouvements de capitalisation boursière sont du bruit lorsque vous regardez une entreprise de 428 milliards de dollars avec une volatilité hebdomadaire normale. Ce qui compte vraiment, c'est de savoir si le dépassement des revenus du T1 cité par Grok se maintient dans les prévisions, et si ces frais de résiliation de Warner Bros. — que j'ai signalés comme ponctuels — se répètent. Si ce n'est pas le cas, le risque de compression du multiple que j'ai décrit devient rapidement réel.
Claude, votre point sur le ratio dette/capitaux propres comme étant un piège manque la réalité de la structure de capital actuelle de Netflix. Vous avez cité un ratio dette/capitaux propres de 55,7% comme preuve d'un levier dangereux, mais ce niveau est en fait tout à fait gérable pour une entreprise générant un flux de trésorerie aussi constant. Ce ratio nous indique que pour chaque dollar de capitaux propres, l'entreprise supporte environ 56 cents de dette, ce qui est une empreinte conservatrice pour un géant médiatique mature. Je crois que Netflix a réussi à dépasser la phase de croissance alimentée par la dette, rendant vos préoccupations concernant leur bilan légèrement exagérées.
Claude, votre préoccupation concernant le levier est valable, mais le signal clé à mes yeux est la puissance de rentabilité de Netflix. Le ROE de 41,86% signale que Netflix transforme les capitaux propres en profits à un rythme bien supérieur à celui de ses pairs. Cela se traduit par un pouvoir de fixation des prix et une efficacité du capital qui alimentent le moteur de trésorerie. Pourtant, un multiple élevé reste risqué si la croissance ralentit ou si les flux de trésorerie faiblissent, maintenant la dette sous les feux de la rampe.
Round 3 — Réfutations finales
Round 3 — Réfutations finales
Claude, pour développer votre analyse du graphique hebdomadaire, la divergence de volume signale une distribution institutionnelle baissière jusqu'au T2 2026. La cassure post-résultats du 25 avril a été alimentée par 35 millions d'actions, attirant des achats de gros investisseurs. Les baisses récentes comme celle du 11 juillet se négocient avec la moitié de ce volume — un support plus faible signifie que les vendeurs dominent, risquant une compression supplémentaire par-dessus l'étirement de la valorisation que nous avons tous signalé.
Je veux revenir sur quelque chose que Gemini et Grok ont tous deux laissé passer : l'affirmation selon laquelle le ratio dette/capitaux propres de 55,7% de Netflix est "gérable" ou "conservateur" pour une entreprise médiatique. Ce n'est pas exact. Disney a un ratio D/E d'environ 1,2x — près du double du ratio de Netflix — et Disney est un conglomérat à forte intensité de capital avec des parcs à thème et la télévision linéaire. Le ratio D/E de 55,7% de Netflix est en fait dans la fourchette haute pour le streaming. Ce qui importe davantage : la marge nette de 24% de Netflix est réelle, mais elle n'augmente pas. Si la croissance des abonnés stagne et que les tarifs publicitaires subissent des pressions — deux risques réels dans un marché saturé — ce levier devient un fardeau, pas une caractéristique. Grok présente les rachats d'actions comme étant "sans risque de dilution", mais les rachats financés par la dette dans un environnement de croissance ralentie sont exactement la façon dont vous détruisez la valeur pour les actionnaires. Je ne change pas ma recommandation de conservation, mais je suis plus préoccupé par les calculs du bilan que le panel ne l'est.
Claude, je dois contester votre rejet de la transition de leadership comme un simple risque de continuité. Le départ de Reed Hastings de la présidence le 16 avril est un changement structurel majeur pour une entreprise qui a dépendu de sa vision spécifique pendant près de trois décennies. Il ne s'agit pas simplement d'un changement de direction ; c'est le départ de l'architecte principal du modèle de streaming à un moment où l'entreprise doit pivoter vers des niveaux financés par la publicité. Si la nouvelle direction ne parvient pas à naviguer ce changement d'identité, le ratio P/E actuel de 41,07, qui représente la prime que les investisseurs paient pour les bénéfices futurs, s'effondrera probablement.
Je pense que nous devrions élargir le cadre aux dynamiques concurrentielles, pas seulement aux fondamentaux. Claude, votre analyse du levier est importante, mais l'expansion continue du niveau financé par la publicité de Disney et sa stratégie de regroupement avec Hulu créent une pression réelle sur les prix et la demande pour NFLX. Si Disney accélère son déploiement international ou augmente son exposition aux sports en direct, NFLX sera confronté à plus de concurrence pour les mêmes dollars publicitaires et les mêmes abonnés premium. Gemini, Grok, l'attention du marché sur la rentabilité dépendra moins des marges seules et davantage de la manière dont NFLX maintiendra sa part de demande face à ces feuilles de route.
Prévisions de prix
| Modèle | Objectif 3 mois | Objectif 6 mois | Raisonnement |
|---|---|---|---|
| Grok | $1280.00 | $1350.00 | Je pense que Netflix progressera jusqu'au T2 2026 si les ajouts d'abonnés au niveau publicitaire valident les remparts de rentabilité face aux concurrents. Le catalyseur clé est les résultats du T2 le 23 juillet 2026 ou aux alentours, où des prévisions de croissance des revenus de 15%+ grâce aux publicités pourraient déclencher une expansion du multiple. Le grand risque est un manque à gagner d'abonnés inférieur à 5 millions nets, ravivant les craintes de saturation et comprimant le P/E de 41 — qui anticipe déjà une exécution sans faille sans marge pour que des rivaux comme Disney volent des parts de marché. À un P/E prévisionnel de 38, impliqué par ma cible de 1350 sur 6 mois à partir de la clôture actuelle de 1245, cela suppose une livraison constante du BPA sans les secousses de leadership post-Hastings. |
| Claude | $1080.00 | $1020.00 | Netflix est prise entre une rentabilité de forteresse et une valorisation qui ne laisse aucune marge d'erreur dans un marché saturé. Ma thèse : le multiple P/E de 41x se comprime si la croissance des abonnés stagne ou si les tarifs publicitaires s'affaiblissent, deux risques réels d'ici le T3 2026. Le catalyseur concret est les prévisions de résultats du T2 le 18 juillet — si la direction signale une croissance plus lente des ajouts nets ou une stagnation de l'ARPU, le marché réévalue rapidement à la baisse. Le risque qui brise cela : l'adoption du niveau publicitaire s'accélère au-delà du consensus, justifiant le multiple. Sur la valorisation : 41 fois les bénéfices signifie que le marché anticipe une croissance annuelle des bénéfices de 15%+ pendant des années ; la marge nette de Netflix de 24% est solide mais plate, pas en expansion. Le départ de Hastings ajoute un risque d'exécution. Je prévois une faiblesse de 3 mois à 1 080 $ à mesure que les préoccupations concernant le levier refont surface, puis une stabilisation près de 1 020 $ en octobre, le marché réévaluant à 35x les bénéfices — toujours une prime, mais plus honnête. |
| Gemini | $1180.00 | $1250.00 | Ma thèse est que Netflix se négociera latéralement pendant qu'elle absorbe la transition de leadership, pour finalement progresser plus haut uniquement si les revenus des niveaux publicitaires compensent la saturation des abonnés. Le catalyseur principal est le rapport de résultats du T3 2026, qui servira de premier véritable test de la capacité de la direction à augmenter la rentabilité des niveaux publicitaires sans Reed Hastings. Le risque majeur est une contraction significative de la marge nette de 24,05%, ce qui signalerait que la concurrence érode enfin leur pouvoir de fixation des prix. Les investisseurs paient actuellement 41,07 fois les bénéfices des douze derniers mois, ce qui signifie que le marché parie sur une croissance soutenue et à forte marge qui ne laisse aucune marge d'erreur dans les trimestres à venir. |
| Chatgpt | $1150.00 | $1250.00 | Je pense que NFLX peut progresser dans les mois à venir car la rentabilité reste durable. Catalyseur : les résultats du T2 2026 renforcent que la discipline de croissance et de marge est intacte. Risque : un manque à gagner au T2 ou des prévisions faibles pourraient déclencher une compression du multiple. Ce P/E de 41x sur douze mois signifie que Netflix est valorisé pour des bénéfices futurs hors norme, donc tout manque à gagner à court terme pourrait déclencher une compression du multiple. |
Signaux de trading Signaux d'achat/vente récents avec prix d'entrée et ratio risque/récompense
Aucun signal ouvert pour le moment — aucune carte n'est remplie, et c'est honnête.
Mes métriques Votre watchlist personnelle — lignes sélectionnées de Fondamentaux Complets
Choisissez les indicateurs qui vous importent — cliquez sur le + à côté de n'importe quelle ligne dans les Fondamentaux complets ci-dessus.
Votre sélection est enregistrée et vous suit sur tous les tickers.