NFLX Netflix, Inc. - Common Stock
NASDAQ · Media · Wyświetl na SEC EDGAR ↗ zamknij Paź 2, 2026 10-K/10-Q Lip 17, 2026NFLX Migawka akcji Cena, kapitalizacja rynkowa, P/E, EPS, ROE, zadłużenie/kapitał własny, zakres 52-tygodniowy
NFLX Wykres ceny akcji Dzienny OHLCV ze wskaźnikami technicznymi — przesuwaj, powiększaj i dostosowuj widok
Granularność słupków dostosowuje się do wybranego okresu — najedź kursorem na wykres, aby zobaczyć otwarcia/maksima/minima/zamknięcia dla danego słupka.
| Data ex-dywidendy | Podział | Typ |
|---|---|---|
| 17 listopada 2025 | 10-for-1 | Naprzód |
| 15 lipca 2015 | 7-for-1 | Naprzód |
| 12 lutego 2004 | 2-for-1 | Naprzód |
O Netflix, Inc. - Common Stock Przegląd firmy z Wikipedii
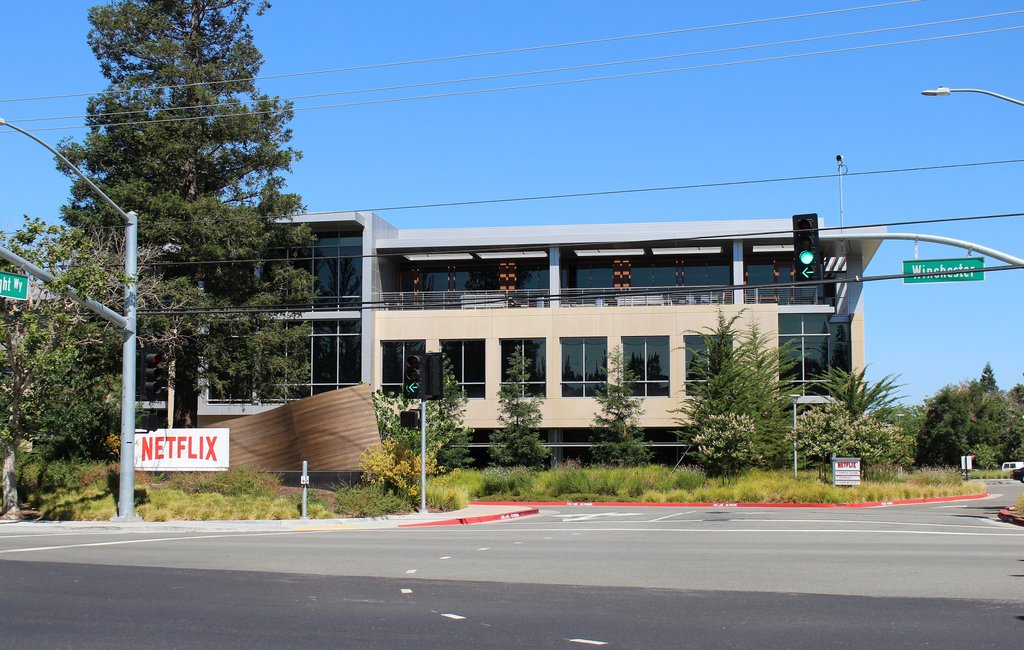
Netflix, Inc. is an American media company founded on August 29, 1997, by Reed Hastings and Marc Randolph in Scotts Valley, California, and currently based in Los Gatos, California, with production offices and stages at the Los Angeles–based Hollywood studios (formerly old Warner Brothers studios) and the Albuquerque Studios (formerly ABQ studios). It owns and operates an eponymous over-the-top subscription video on-demand service, which showcases acquired and original programming as well as third-party content licensed from other production companies and distributors. Netflix is also the first streaming media company to be a member of the Motion Picture Association.
Netflix initially both sold and rented DVDs by mail, but the sales were eliminated within a year to focus on the DVD rental business. In 2007, Netflix introduced streaming media and video on demand. The company expanded to Canada in 2010, followed by Latin America and the Caribbean. In 2011, the service began to acquire and produce original content, beginning with the crime drama Lilyhammer.
The company has been listed on Nasdaq since 2002 and is ranked 117th on the Fortune 500 and 219th on the Forbes Global 2000. It is the largest entertainment/media company by market capitalization as of 2026 estimated at $450 billion. In 2021, Netflix was ranked as the eighth-most trusted brand globally by Morning Consult. During the 2010s, Netflix was the top-performing stock in the S&P 500 stock market index, with a total return of 3,693%.
The company has two CEOs, Greg Peters and Ted Sarandos, who are split between Los Gatos and Los Angeles, respectively. It also operates international offices in Asia, Europe and Latin America including in Canada, France, Brazil, the Netherlands, India, Italy, Japan, Poland, South Korea, and the United Kingdom. The company has production hubs in Los Angeles, Albuquerque, London, Madrid, Vancouver and Toronto.
History
Launch as a mail-based rental business (1997–2006)
Netflix was founded by Marc Randolph and Reed Hastings on August 29, 1997, in Scotts Valley, California. Hastings, a computer scientist and mathematician, was a cofounder of Pure Software, which was acquired by Rational Software that year for $750 million, the then biggest acquisition in Silicon Valley history. Randolph had worked as a marketing director for Pure Software after Pure Atria acquired a company where Randolph worked. He was previously a co-founder of MicroWarehouse, a computer mail-order company as well as vice president of marketing for Borland. Hastings and Randolph came up with the idea for Netflix while carpooling between their homes in Santa Cruz, California, and Pure Atria's headquarters in Sunnyvale. Patty McCord, later head of human resources at Netflix, was also in the carpool group. Randolph admired Amazon and wanted to find a large category of portable items to sell over the Internet using a similar model. Hastings and Randolph considered and rejected selling and renting VHS as too expensive to stock and too delicate to ship. When they heard about DVDs, first introduced in the United States in early 1997, they tested the concept of selling or renting DVDs by mail by mailing a compact disc to Hastings's house in Santa Cruz. When the disc arrived intact, they decided to enter the $16 billion home video sales and rental industry. Hastings is often quoted saying that he decided to start Netflix after being fined $40 at a Blockbuster store for being late to return a copy of Apollo 13, a claim since repudiated by Randolph. Hastings invested $2.5 million into Netflix from the sale of Pure Atria. Netflix launched as the first DVD rental and sales website with 30 employees and 925 titles available—nearly all DVDs published. Randolph and Hastings met with Jeff Bezos, where Amazon offered to acquire Netflix for between $14 and $16 million. Fearing competition from Amazon, Randolph at first thought the offer was fair, but Hastings, who owned 70% of the company, turned it down on the plane ride home.
Initially, Netflix offered a per-rental model for each DVD but introduced a monthly subscription concept in September 1999. The per-rental model was dropped by early 2000, allowing the company to focus on the business model of flat-fee unlimited rentals without due dates, late fees, shipping and handling fees, or per-title rental fees. In September 2000, during the dot-com bubble, while Netflix was suffering losses, Hastings and Randolph offered to sell the company to Blockbuster for $50 million. John Antioco, CEO of Blockbuster, thought the offer was a joke and declined, saying, "The dot-com hysteria is completely overblown." While Netflix experienced fast growth in early 2001, the continued effects of the dot-com bubble collapse and the September 11 attacks caused the company to hold off plans for its initial public offering (IPO) and to lay off one-third of its 120 employees.
DVD players were a popular gift for holiday sales in late 2001, and demand for DVD subscription services were "growing like crazy", according to chief talent officer Patty McCord. The company went public on NASDAQ under the ticker symbol NFLX on May 29, 2002, selling 5.5 million shares of common stock at US$15.00 per share. In 2003, Netflix was issued a patent by the U.S. Patent and Trademark Office to cover its subscription rental service and several extensions. Netflix posted its first profit in 2003, earning $6.5 million on revenues of $272 million; by 2004, profit had increased to $49 million on over $500 million in revenues. In 2005, 35,000 different films were available, and Netflix shipped 1 million DVDs out every day.
In 2004, Blockbuster introduced a DVD rental service, which not only allowed users to check out titles through online sites but allowed for them to return them at brick and-mortar stores. By 2006, Blockbuster's service reached two million users, and while trailing Netflix's subscriber count, was drawing business away from Netflix. Netflix lowered fees in 2007. While it was an urban legend that Netflix ultimately "killed" Blockbuster in the DVD rental market, Blockbuster's debt load and internal disagreements hurt the company.
On April 4, 2006, Netflix filed a patent infringement lawsuit in which it demanded a jury trial in the U.S. District Court for the Northern District of California, alleging that Blockbuster's online DVD rental subscription program violated two patents held by Netflix. The first cause of action alleged Blockbuster's infringement of copying the "dynamic queue" of DVDs available for each customer, Netflix's method of using the ranked preferences in the queue to send DVDs to subscribers, and Netflix's method permitting the queue to be updated and reordered. The second cause of action alleged infringement of the subscription rental service as well as Netflix's methods of communication and delivery. The companies settled their dispute on June 25, 2007; terms were not disclosed.
On October 1, 2006, Netflix announced the Netflix Prize, $1,000,000 to the first developer of a video recommendation algorithm that could beat its existing algorithm Cinematch, at predicting customer ratings by more than 10%. On September 21, 2009, it awarded the $1,000,000 prize to team "BellKor's Pragmatic Chaos". Cinematch, launched in 2000, is a recommendation system that recommended movies to its users, many of which they might not ever had heard of before.
Through its division Red Envelope Entertainment, Netflix licensed and distributed independent films such as Born into Brothels and Sherrybaby. In late 2006, Red Envelope Entertainment also expanded into producing original content with filmmakers such as John Waters. Netflix closed Red Envelope Entertainment in 2008.
Transition to streaming services (2007–2012)
In January 2007, the company launched a streaming media service, introducing video on demand via the Internet. However, at that time it only had 1,000 films available for streaming, compared to 70,000 available on DVD. The company had for some time considered offering movies online, but it was only in the mid-2000s that data speeds and bandwidth costs had improved sufficiently to allow customers to download movies from the net. The original idea was a "Netflix box" that could download movies overnight, and be ready to watch the next day. By 2005, Netflix had acquired movie rights and designed the box and service. But after witnessing how popular streaming services such as YouTube were despite the lack of high-definition content, the concept of using a hardware device was scrapped and replaced with a streaming concept.
In February 2007, Netflix delivered its billionth DVD, a copy of Babel to a customer in Texas. In April 2007, Netflix recruited ReplayTV founder Anthony Wood, to build a "Netflix Player" that would allow streaming content to be played directly on a television rather than a desktop or laptop. Hastings eventually shut down the project to help encourage other hardware manufacturers to include built-in Netflix support, which would be spun off as the digital media player product Roku.
In January 2008, all rental-disc subscribers became entitled to unlimited streaming at no additional cost. This change came in a response to the introduction of Hulu and to Apple's new video-rental services. In August 2008, the Netflix database was corrupted and the company was not able to ship DVDs to customers for 3 days, leading the company to move all its data to the Amazon Web Services cloud. In November 2008, Netflix began offering subscribers rentals on Blu-ray and discontinued its sale of used DVDs. In 2009, Netflix streams overtook DVD shipments.
On January 6, 2010, Netflix agreed with Warner Bros. to delay new release rentals 28 days prior to retail, in an attempt to help studios sell physical copies, and similar deals involving Universal Pictures and 20th Century Fox were reached on April 9. In July 2010, Netflix signed a deal to stream movies of Relativity Media. In August 2010, Netflix reached a five-year deal worth nearly $1 billion to stream films from Paramount, Lionsgate and Metro-Goldwyn-Mayer. The deal increased Netflix's annual spending fees, adding roughly $200 million per year. It spent $117 million in the first six months of 2010 on streaming, up from $31 million in 2009. On September 22, 2010, Netflix launched in Canada, its first international market. In November 2010, Netflix began offering a standalone streaming service separate from DVD rentals.
In 2010, Netflix acquired the rights to Breaking Bad, produced by Sony Pictures Television, after the show's third season, at a point where original broadcaster AMC had expressed the possibility of cancelling the show. Sony pushed Netflix to release Breaking Bad in time for the fourth season, which as a result greatly expanded the show's audience on AMC due to new viewers binging on the Netflix past episodes, and doubling the viewership by the time of the fifth season. Breaking Bad is considered the first such show to have this "Netflix effect".
In January 2011, Netflix announced agreements with several manufacturers to include branded Netflix buttons on the remote controls of devices compatible with the service, such as Blu-ray players. By May 2011, Netflix had become the largest source of Internet streaming traffic in North America, accounting for 30% of traffic during peak hours.
On July 12, 2011, Netflix announced that it would separate its existing subscription plans into two separate plans: one covering the streaming and the other DVD rental services. The cost for streaming would be $7.99 per month, while DVD rental would start at the same price. On September 11, 2011, Netflix expanded to 43 countries in Latin America. On September 18, 2011, Netflix announced its intentions to rebrand and restructure its DVD home media rental service as an independent subsidiary called Qwikster, separating DVD rental and streaming services. On September 26, 2011, Netflix announced a content deal with DreamWorks Animation. On October 10, 2011, Netflix announced that it would retain its DVD service under the name Netflix and that its streaming and DVD-rental plans would remain branded together.
On January 9, 2012, Netflix started its expansion to Europe, launching in the United Kingdom and Ireland. In February 2012, Netflix reached a multi-year agreement with The Weinstein Company. In March 2012, Netflix acquired the domain name DVD.com. By 2016, Netflix rebranded its DVD-by-mail service under the name DVD.com, A Netflix Company. In April 2012, Netflix filed with the Federal Election Commission (FEC) to form a political action committee (PAC) called FLIXPAC. Netflix spokesperson Joris Evers tweeted that the intent was to "engage on issues like net neutrality, bandwidth caps, UBB and VPPA". In June 2012, Netflix signed a deal with Open Road Films.
On August 23, 2012, Netflix and The Weinstein Company signed a multi-year output deal for RADiUS-TWC films. In August 2010, Epix signed a five-year streaming deal with Netflix. For the initial two years of this agreement, first-run and back-catalog content from Epix was exclusive to Netflix. Epix films came to Netflix 90 days after premiering on Epix. These included films from Paramount, Metro-Goldwyn-Mayer and Lionsgate.
On October 18, 2012, Netflix launched in Denmark, Finland, Norway and Sweden. On December 4, 2012, Netflix and Disney announced an exclusive multi-year agreement for first-run United States subscription television rights to Walt Disney Studios' animated and live-action films, with classics such as Dumbo, Alice in Wonderland and Pocahontas available immediately and others available on Netflix beginning in 2016. Direct-to-video releases were made available in 2013.
On January 14, 2013, Netflix signed an agreement with Time Warner's Turner Broadcasting System and Warner Bros. Television to distribute Cartoon Network, Warner Bros. Animation, and Adult Swim content, as well as TNT's Dallas, beginning in March 2013. The rights to these programs were given to Netflix shortly after deals with Viacom to stream Nickelodeon and Nick Jr. Channel programs expired.
For cost reasons, Netflix stated that it would limit its expansion in 2013, adding only one new market—the Netherlands—in September of that year. This expanded its availability to 40 territories.
Development of original programming (2013–2017)
Netflix began efforts to develop original content in 2011; in March, Netflix made a straight-to-series order for the Kevin Spacey-led political drama House of Cards from MRC. Beating out other U.S. cable networks, it marked the first first-run television series to be specifically commissioned by the service. In November 2011, Netflix then ordered Orange is the New Black, a comedy-drama adapted from Piper Kerman's memoir of the same name, and a new season of the cancelled Fox sitcom Arrested Development. Netflix also acquired U.S. rights to the Norwegian drama Lilyhammer; following its television premiere on Norway's NRK1 on January 25, 2012, the entirety of its first season was released by Netflix on February 8—a notable departure from the broadcast television model of premiering episodes on a weekly basis.
House of Cards was released by Netflix on February 1, 2013, marketed as the first "Netflix Original" production. Later that month, Netflix announced an agreement with DreamWorks Animation to commission children's television series based on its properties, beginning with Turbo: F.A.S.T., a spin-off of its film Turbo. Orange is the New Black would premiere in July 2013; Netflix stated that Orange is the New Black had been its most-watched original series so far, with all of them having "an audience comparable with successful shows on cable and broadcast TV."
On March 13, 2013, Netflix added a Facebook sharing feature, letting United States subscribers access "Watched by your friends" and "Friends' Favorites" by agreeing. This was not legal until the Video Privacy Protection Act was modified in early 2013. On August 1, 2013, Netflix reintroduced the "Profiles" feature that permits accounts to accommodate up to five user profiles.
In November 2013, Marvel Television and ABC Studios announced Netflix had ordered a slate of four television series based on the Marvel Comics characters Daredevil, Jessica Jones, Iron Fist and Luke Cage. Each of the four series received an initial order of 13 episodes, and Netflix also ordered a Defenders miniseries that would tie them together. Daredevil and Jessica Jones premiered in 2015. The Luke Cage series premiered on September 30, 2016, followed by Iron Fist on March 17, 2017, and The Defenders on August 18, 2017. Marvel owner Disney later entered into other content agreements with Netflix, including acquiring its animated Star Wars series Star Wars: The Clone Wars, and a new sixth season.
In February 2014, Netflix began to enter into agreements with U.S. internet service providers, beginning with Comcast (whose customers had repeatedly complained of frequent buffering when streaming Netflix), to provide the service a direct connection to their networks. In April 2014, Netflix signed Arrested Development creator Mitchell Hurwitz and his production firm The Hurwitz Company to a multi-year deal to create original projects for the service. In May 2014, Netflix acquired streaming rights to films produced by Sony Pictures Animation. It also quietly began to introduce an updated logo, with a flatter appearance and updated typography.
In September 2014, Netflix expanded into six new European markets, including Austria, Belgium, France, Germany, Luxembourg, and Switzerland. On September 10, 2014, Netflix participated in Internet Slowdown Day by deliberately slowing down its speed in support of net neutrality regulations in the United States. In October 2014, Netflix announced a four-film deal with Adam Sandler and his Happy Madison Productions.
In April 2015, following the launch of Daredevil, Netflix director of content operations Tracy Wright announced that Netflix had added support for audio description (a narration track with aural descriptions of key visual elements for the blind or visually impaired), and had begun to work with its partners to add descriptions to its other original series over time. The following year, as part of a settlement with the American Council of the Blind, Netflix agreed to provide descriptions for its original series within 30 days of their premiere, and add screen reader support and the ability to browse content by availability of descriptions.
In March 2015, Netflix expanded to Australia and New Zealand. In September 2015, Netflix launched in Japan, its first country in Asia. In October 2015, Netflix launched in Italy, Portugal, and Spain.
In January 2016, at the Consumer Electronics Show, Netflix announced a major international expansion of its service into 130 additional countries. It then had become available worldwide except China, Syria, North Korea, Kosovo and Crimea. In May 2016, Netflix created a tool called Fast.com to determine the speed of an Internet connection. It received praise for being "simple" and "easy to use", and does not include online advertising, unlike competitors. On November 30, 2016, Netflix launched an offline playback feature, allowing users of the Netflix mobile apps on Android or iOS to cache content on their devices in standard or high quality for viewing offline, without an Internet connection.
In 2016, Netflix released an estimated 126 original series or films, more than any other network or cable channel. In April 2016, Hastings stated that the company planned to expand its in-house, Los Angeles-based Netflix Studios to grow its output; Hastings ruled out any potential acquisitions of existing studios, stating that "It's been 15 years we've been public and 20 years existing, and we've done no [mergers and acquisitions]. So I think that probably speaks for itself."
In February 2017, Netflix signed a music publishing deal with BMG Rights Management, whereby BMG will oversee rights outside of the United States for music associated with Netflix original content. Netflix continues to handle these tasks in-house in the United States. On April 25, 2017, Netflix signed a licensing deal with IQiyi, a Chinese video streaming platform owned by Baidu, to allow selected Netflix original content to be distributed in China on the platform.
On August 7, 2017, Netflix acquired Millarworld, the creator-owned publishing company of comic book writer Mark Millar. The purchase marked the first corporate acquisition to have been made by Netflix. On August 14, 2017, Netflix entered into an exclusive development deal with Shonda Rhimes and her production company Shondaland.
In September 2017, Netflix announced it would offer its low-broadband mobile technology to airlines to provide better in-flight Wi-Fi so that passengers can watch movies on Netflix while on planes.
In September 2017, Minister of Heritage Mélanie Joly announced that Netflix had agreed to make a CA$500 million (US$400 million) investment over the next five years in producing content in Canada. The company denied that the deal was intended to result in a tax break. Netflix realized this goal by December 2018.
In October 2017, Netflix iterated a goal of having half of its library consist of original content by 2019, announcing a plan to invest $8 billion on original content in 2018. There will be a particular focus on films and anime through this investment, with a plan to produce 80 original films and 30 anime series. In October 2017, Netflix introduced the "Skip Intro" feature which allows customers to skip the intros to shows on its platform through a variety of techniques including manual reviewing, audio tagging, and machine learning.
In November 2017, Netflix signed an exclusive multi-year deal with Orange Is the New Black creator Jenji Kohan. In November 2017, Netflix withdrew from co-hosting a party at the 75th Golden Globe Awards with The Weinstein Company due to the Harvey Weinstein sexual abuse cases.
Expansion into international productions (2017–2020)
In November 2017, Netflix announced that it would be making its first original Colombian series, to be executive produced by Ciro Guerra. In December 2017, Netflix signed Stranger Things director-producer Shawn Levy and his production company 21 Laps Entertainment to what sources say is a four-year deal. In 2017, Netflix invested in distributing exclusive stand-up comedy specials from Dave Chappelle, Louis C.K., Chris Rock, Jim Gaffigan, Bill Burr and Jerry Seinfeld.
In February 2018, Netflix acquired the rights to The Cloverfield Paradox from Paramount Pictures for $50 million and launched on its service on February 4, 2018, shortly after airing its first trailer during Super Bowl LII. Analysts believed that Netflix's purchase of the film helped to make the film instantly profitable for Paramount compared to a more traditional theatrical release, while Netflix benefited from the surprise reveal. Other films acquired by Netflix include international distribution for Paramount's Annihilation and Universal's News of the World and worldwide distribution of Universal's Extinction, Warner Bros.' Mowgli: Legend of the Jungle, Paramount's The Lovebirds and 20th Century Studios' The Woman in the Window. In March, the service ordered Formula 1: Drive to Survive, a racing docuseries following teams in the Formula One world championship.
In March 2018, Sky UK announced an agreement with Netflix to integrate Netflix's subscription VOD offering into its pay-TV service. Customers with its high-end Sky Q set-top box and service will be able to see Netflix titles alongside their regular Sky channels. In October 2022, Netflix revealed that its annual revenue from the UK subscribers in 2021 was £1.4bn.
In April 2018, Netflix pulled out of the Cannes Film Festival, in response to new rules requiring competition films to have been released in French theaters. The Cannes premiere of Okja in 2017 was controversial, and led to discussions over the appropriateness of films with simultaneous digital releases being screened at an event showcasing theatrical film; audience members also booed the Netflix production logo at the screening. Netflix's attempts to negotiate to allow a limited release in France were curtailed by organizers, as well as French cultural exception law—where theatrically screened films are legally forbidden from being made available via video-on-demand services until at least 36 months after their release. Besides traditional Hollywood markets as well as from partners like the BBC, Sarandos said the company also looking to expand investments in non-traditional foreign markets due to the growth of viewers outside of North America. At the time, this included programs such as Dark from Germany, Ingobernable from Mexico and 3% from Brazil.
On May 22, 2018, former president, Barack Obama, and his wife, Michelle Obama, signed a deal to produce docu-series, documentaries and features for Netflix under the Obamas' newly formed production company, Higher Ground Productions.
In June 2018, Netflix announced a partnership with Telltale Games to port its adventure games to the service in a streaming video format, allowing simple controls through a television remote. The first game, Minecraft: Story Mode, was released in November 2018. In July 2018, Netflix earned the most Emmy nominations of any network for the first time with 112 nods. On August 27, 2018, the company signed a five-year exclusive overall deal with international best–selling author Harlan Coben. On the same day, the company inked an overall deal with Gravity Falls creator Alex Hirsch. In October 2018, Netflix paid under $30 million to acquire Albuquerque Studios (ABQ Studios), a $91 million film and TV production facility with eight sound stages in Albuquerque, New Mexico, for its first U.S. production hub, pledging to spend over $1 billion over the next decade to create one of the largest film studios in North America. In November 2018, Paramount Pictures signed a multi-picture film deal with Netflix, making Paramount the first major film studio to sign a deal with Netflix. A sequel to AwesomenessTV's To All the Boys I've Loved Before was released on Netflix under the title To All the Boys: P.S. I Still Love You as part of the agreement. In December 2018, the company announced a partnership with ESPN Films on a television documentary chronicling Michael Jordan and the 1997–98 Chicago Bulls season titled The Last Dance. It was released internationally on Netflix and became available for streaming in the United States three months after a broadcast airing on ESPN.
In January 2019, Sex Education made its debut as a Netflix original series with much critical acclaim. On January 22, 2019, Netflix sought and was approved for membership into the Motion Picture Association of America (MPAA), as the first streaming service to become a member of the association. In February 2019, The Haunting creator Mike Flanagan joined frequent collaborator Trevor Macy as a partner in Intrepid Pictures and the duo signed an exclusive overall deal with Netflix to produce television content. On May 9, 2019, Netflix contracted with Dark Horse Entertainment to make television series and films based on comics from Dark Horse Comics. In July 2019, Netflix announced that it would be opening a hub at Shepperton Studios as part of a deal with Pinewood Group. In early-August 2019, Netflix negotiated an exclusive multi-year film and television deal with Game of Thrones creators and showrunners David Benioff and D.B. Weiss. The first Netflix production created by Benioff and Weiss was planned as an adaptation of Liu Cixin's science fiction novel The Three-Body Problem, part of the Remembrance of Earth's Past trilogy. On September 30, 2019, in addition to renewing Stranger Things for a fourth season, Netflix signed The Duffer Brothers to an overall deal covering future film and television projects for the service.
On November 13, 2019, Netflix and Nickelodeon entered into a multi-year agreement to produce several original animated feature films and television series based on Nickelodeon's library of characters. This agreement expanded on their existing relationship, in which new specials based on the past Nickelodeon series Invader Zim and Rocko's Modern Life (Invader Zim: Enter the Florpus and Rocko's Modern Life: Static Cling respectively) were released by Netflix. Other new projects planned under the team-up include a music project featuring Squidward Tentacles from the animated television series SpongeBob SquarePants, and films based on The Loud House and Rise of the Teenage Mutant Ninja Turtles. The agreement with Disney ended in 2019 due to the launch of Disney+, with its Marvel productions moving exclusively to the service in 2022.
In November 2019, Netflix announced that it had signed a long-term lease to save the Paris Theatre, the last single-screen movie theater in Manhattan. The company oversaw several renovations at the theater, including new seats and a concession stand.
In January 2020, Netflix announced a new four-film deal with Adam Sandler worth up to $275 million. On February 25, 2020, Netflix formed partnerships with six Japanese creators to produce an original Japanese anime project. This partnership includes manga creator group CLAMP, mangaka Shin Kibayashi, mangaka Yasuo Ohtagaki, novelist and film director Otsuichi, novelist Tow Ubukata, and manga creator Mari Yamazaki. On March 4, 2020, ViacomCBS announced that it will be producing two spin-off films based on SpongeBob SquarePants for Netflix. On April 7, 2020, Peter Chernin's Chernin Entertainment made a multi-year first-look deal with Netflix to make films. On May 29, 2020, Netflix announced the acquisition of Grauman's Egyptian Theatre from the American Cinematheque to use as a special events venue. In July 2020, Netflix appointed Sarandos as co-CEO. In July 2020, Netflix invested in Black Mirror creators Charlie Brooker and Annabel Jones' new production outfit Broke And Bones.
Expansion into gaming, end of DVDs, etc. (2021–2025)
In March 2021, Netflix earned the most Academy Award nominations of any studio, with 36. Netflix won seven Academy Awards, which was the most by any studio. Later that year, Netflix also won more Emmys than any other network or studio with 44 wins, tying the record for most Emmys won in a single year set by CBS in 1974. On April 8, 2021, Sony Pictures Entertainment announced an agreement for Netflix to hold the U.S. pay television window rights to its releases beginning in 2022, replacing Starz and expanding upon an existing agreement with Sony Pictures Animation. The agreement also includes a first-look deal for any future direct-to-streaming films being produced by Sony Pictures, with Netflix required to commit to a minimum number of them. On April 27, 2021, Netflix announced that it was opening its first Canadian headquarters in Toronto. The company also announced that it would open an office in Sweden as well as Rome and Istanbul to increase its original content in those regions.
In early-June, Netflix hosted a first-ever week-long virtual event called "Geeked Week", where it shared exclusive news, new trailers, cast appearances and more about upcoming genre titles like The Witcher, The Cuphead Show!, and The Sandman.
In July 2021, Netflix hired Mike Verdu, a former executive from Electronic Arts and Facebook, as vice president of game development, along with plans to add video games by 2022. Netflix announced plans to release mobile games which would be included in subscribers' plans to the service. Trial offerings were first launched for Netflix users in Poland in August 2021, offering premium mobile games based on Stranger Things including Stranger Things 3: The Game, for free to subscribers through the Netflix mobile app.
Also in September, the company announced The Queen's Ball: A Bridgerton Experience, launching in 2022 in Los Angeles, Chicago, Montreal, and Washington, D.C.
On September 20, 2021, Netflix signed a long-term lease with Aviva Investors to operate and expand the Longcross Studios in Surrey, UK. On September 21, 2021, Netflix announced that it would acquire the Roald Dahl Story Company, which manages the rights to Roald Dahl's stories and characters, for an undisclosed price and would operate it as an independent company. The company acquired Night School Studio, an independent video game developer, on September 28, 2021. Netflix officially launched mobile games on November 2, 2021, for Android users around the world. Through the app, subscribers had free access to five games, including two previously made Stranger Things titles. Netflix intends to add more games to this service over time. On November 9, the collection launched for iOS. Some games in the collection require an active internet connection to play, while others will be available offline. Netflix Kids' accounts will not have games available.
On October 13, 2021, Netflix announced the launch of the Netflix Book Club, where readers will hear about new books, films, and series adaptations and have exclusive access to each book's adaptation process. Netflix will partner with Starbucks to bring the book club to life via a social series called But Have You Read the Book?. Uzo Aduba will serve as the inaugural host of the series and announce monthly book selections set to be adapted by the streamer. Aduba will also speak with the cast, creators, and authors about the book adaptation process over a cup of coffee at Starbucks. Through October 2021, Netflix commonly reported viewership for its programming based on the number of viewers or households that watched a show in a given period (such as the first 28 days from its premiere) for at least two minutes. On the announcement of its quarterly earnings in October 2021, the company stated that it would switch its viewership metrics to measuring the number of hours that a show was watched, including rewatches, which the company said was closer to the measurements used in linear broadcast television, and thus "our members and the industry can better measure success in the streaming world." On November 16, 2021, Netflix announced the launch of "Top10 on Netflix.com", a new website with weekly global and country lists of the most popular titles on their service based on their new viewership metrics.
On November 22, 2021, Netflix announced that it would acquire Scanline VFX, the visual effects and animation company behind Cowboy Bebop and Stranger Things. On the same day, Roberto Patino signed a deal with Netflix and established his own production banner, Analog Inc., in partnership with the company. Patino's first project under the deal is a series adaptation of Image Comics' Nocterra. On December 6, 2021, Netflix and Stage 32 announced that they have teamed up the workshops at the Creating Content for the Global Marketplace program. On December 7, 2021, Netflix partnered with IllumiNative, a woman-led non-profit organization, for the Indigenous Producers Training Program.
On December 9, 2021, Netflix announced the launch of "Tudum", an official companion website that offers news, exclusive interviews, and behind-the-scenes videos for its original television shows and films. On December 13, 2021, Netflix signed a multi-year overall deal with Kalinda Vazquez. On December 16, 2021, Netflix signed a multi-year creative partnership with Spike Lee and his production company 40 Acres and a Mule Filmworks to develop film and television projects. In December 2021, former Netflix engineer Sung Mo Jun was sentenced to 2 years in prison for an insider trading scheme where he leaked subscriber numbers in advance of official releases.
In compliance with the EU Audiovisual Media Services Directive and its implementation in France, Netflix reached commitments with French broadcasting authorities and film guilds, as required by law, to invest a specific amount of its annual revenue into original French films and series. These films must be theatrically released and would not be allowed to be carried on Netflix until 15 months after their release.
The company announced plans to acquire Next Games in March 2022 for €65 million as part of Netflix's expansions into gaming. Next Games had developed the mobile title Stranger Things: Puzzle Tales as well as two The Walking Dead mobile games. Later in the month, Netflix also acquired the Texas-based mobile game developer, Boss Fight Entertainment, for an undisclosed sum.
Following the 2022 Russian invasion of Ukraine, Netflix suspended its operations and future projects in Russia. It also announced that it would not comply with a proposed directive by Roskomnadzor requiring all internet streaming services with more than 100,000 subscribers to integrate the major free-to-air channels (which are primarily state-owned). A month later, ex-Russian subscribers filed a class action lawsuit against Netflix.
At the end of Q1 2022, Netflix announced a decline in subscribers, with almost 200,000 fewer viewers than at the end of the previous year. Netflix stated that 100 million households globally were sharing passwords to their account with others, and that Canada and the United States accounted for 30 million of them. Following these announcements, Netflix's stock price fell by 35 percent. By June 2022, Netflix had laid off 450 full-time and contract employees as part of the company's plan to trim costs amid lower than expected subscriber growth. The layoffs represented approximately 2 percent of the workforce and spread across the company globally.
On April 28, 2022, the company launched its inaugural Netflix Is a Joke comedy festival, featuring more than 250 shows over 12 nights at 30-plus locations across Los Angeles, including the first-ever stand-up show at Dodger Stadium.
On July 19, 2022, Netflix announced plans to acquire Australian animation studio Animal Logic.
On September 5, 2022, Netflix opened an office in Warsaw, Poland responsible for the service's operations in 28 markets in Central and Eastern Europe.
On October 4, 2022, Netflix have signed a creative partnership with Andrea Berloff and John Gatins.
On October 11, 2022, Netflix signed up to the Broadcasters' Audience Research Board for external measurement of viewership in the UK.
On October 12, 2022, Netflix signed to build a production complex at Fort Monmouth in Eatontown, New Jersey.
On October 18, 2022, Netflix began exploring a cloud gaming offering and opened a new gaming studio in Southern California.
On January 10, 2023, Netflix announced plans to open an engineering hub in its Warsaw office. The hub is to provide Netflix's creative partners with software solutions in the production of films and series.
On April 18, 2023, Netflix announced that it would discontinue their DVD-by-mail service on September 29.
Netflix reworked its viewership metrics again in June 2023. Viewership of shows were measured during the first 91 days of availability, instead of the first 28 days, and now are based on the total viewership hours divided by the total hours of the show itself. This provided more equal considerations for shorter shows and movies compared to longer ones.
In August 2023, the company announced Netflix Stories, a collection of interactive narrative games from Netflix series and films such as Love is Blind, Money Heist and Virgin River.
Netflix discontinued its DVD mailing service as planned on September 29, 2023, in favor of its streaming business. Users of the service were able to keep the DVDs that they had received. Over its lifetime the service had sent out over 5 billion shipments.
In October 2023, Eunice Kim was promoted to Chief Product Officer and Elizabeth Stone was promoted to Chief Technology Officer. That same month, Netflix and Skydance Media entered a multi-year pact to develop and produce animated films, ending Skydance's partnership with Apple. First one under the deal was Spellbound, which premiered in 2024. Netflix would also take over distribution of preexisting Skydance Animation titles, including Ray Gunn and Swapped.
In April 2024, Netflix announced that starting in 2025, it would stop regularly reporting subscriber numbers.
In November 2024, Netflix offices in Paris and Amsterdam have been raided by the French and Dutch authorities as part of an investigation into tax fraud. The company is also under investigation for tax filings for 2019, 2020 and 2021.
The service began venturing into live sports broadcasting with the Jake Paul vs. Mike Tyson boxing match in November 2024, followed by a pair of National Football League games on Christmas Day. In January 2025, Netflix began a global broadcasting agreement with professional wrestling company WWE, under which its weekly series WWE Raw moved to Netflix worldwide, as well as rights outside of the United States to its library content, main roster live events, and all three of its main weekly programs.
In March 2026, Netflix announced its acquisition of Ben Affleck's artificial intelligence startup InterPositive, which was developing a generative AI model for use in filmmaking, trained initially on specially-filmed footage and designed to "understand visual logic and editorial consistency, while preserving cinematic rules under real-world production challenges". Affleck, Matt Damon, and Gerry Cardinale's studio Artists Equity also recently agreed to a first-look deal with Netflix.
Attempted acquisition of Warner Bros. (2025–2026)
On October 31, 2025, Netflix, Inc. was reported to be actively exploring a bid for the studios and streaming assets of Warner Bros. Discovery. According to the report, Netflix retained investment bank Moelis & Co. to evaluate a potential offer and had been granted access to Warner Bros. Discovery's financial data room as part of its preparatory due-diligence. Netflix stressed that it remains "predominantly focused on growing organically" and is not interested in owning legacy cable networks such as CNN, TBS and TNT.
Netflix had previously considered buying other companies such as 20th Century Fox (now 20th Century Studios), Paramount, The Walt Disney Company, and even Electronic Arts. But the price and the fear of a possible shareholder reaction prevented that.
On December 4, 2025, Netflix won the bidding war for Warner Bros. Discovery, to be followed by exclusive talks to finalize a deal. On December 5, Netflix announced a proposed agreement to acquire Warner Bros. Discovery's "Streaming and Studios" businesses for $72 billion, with a total asset value of $82.7 billion. As part of the deal, Netflix would acquire the Warner Bros. division, including its film, television and video game studios, HBO/HBO Max and their respective libraries, DC Entertainment/DC Studios and WBD's distribution, publishing and licensing divisions. The acquisition would have excluded the company's "Global Linear Networks" division (aside from Turner Classic Movies, which is aligned with the Warner Bros. film studio), which would have been divested as the separate company Discovery Global.
Paramount Skydance entered a hostile bid for the entirety of WBD at $30 per share, in an all-cash offer higher than Netflix's $27.75 per share offer for just the studios division; Paramount Skydance assessed its offer as having fewer regulatory hurdles than the Netflix offer. WBD rejected the offer due to concerns over its credibility, believing that it was inferior to Netflix's offer. On January 20, 2026, Netflix amended its own offer to an all-cash offer; WBD shareholders were expected to vote on the deal by April. On February 26, 2026, WBD agreed to a competing bid by Paramount Skydance at $31 per-share, valuing the company at approximately $111 billion. Netflix subsequently backed out, with its co-CEOs issuing a statement that its offer was "no longer financially attractive." Netflix received a $2.8 billion breakup fee from Paramount Skydance, and later announced that it would add $25 billion to its share buyback program.
Corporate affairs
Historical financials and membership growth
Board of directors
As of November 2024, the company's board consisted of the following directors:
Rich Barton (co-founder of Zillow)
Mathias Döpfner (CEO of Axel Springer SE)
Timothy M. Haley (co-founder of Redpoint Ventures)
Jay Hoag (chairman of Netflix, founding partner at TCV)
Leslie Kilgore (former Chief Marketing Officer of Netlix)
Strive Masiyiwa (chairman and founder of Econet)
Ann Mather (former Executive Vice President and Chief Financial Officer of Pixar)
Greg Peters (co-CEO of Netflix)
Susan Rice (former US National Security Advisor and ambassador to the United Nations)
Ted Sarandos (co-CEO of Netflix)
Brad Smith (vice chairman of Microsoft)
Anne Sweeney (former President of the Disney–ABC Television Group)
Corporate culture
Netflix grants all employees extremely broad discretion with respect to business decisions, expenses, and vacation—but in return expects consistently high performance, as enforced by what is known as the "keeper test". All supervisors are expected to constantly ask themselves if they would fight to keep an employee. If the answer is no, then the employee is dismissed. A slide from an internal presentation on Netflix's corporate culture summed up the test as: "Adequate performance gets a generous severance package." Such packages reportedly range from four months' salary in the United States to as much as six months in the Netherlands.
The company offers unlimited vacation time for salaried workers and allows employees to take any amount of their paychecks in stock options.
About the culture that results from applying such a demanding test, Hastings has said that "You gotta earn your job every year at Netflix," and, "There's no question it's a tough place ... There's no question it's not for everyone." Hastings has drawn an analogy to athletics: professional athletes lack long-term job security because an injury could end their career in any particular game, but they learn to put aside their fear of that constant risk and focus on working with great colleagues in the current moment.
Environmental impact
According to a study conducted by the International Energy Agency, streaming a 30-minute show on Netflix in 2019 released around 0.018 kg CO2.
In March 2021, Netflix announced that it would work to reach net zero greenhouse gas emissions by the end of 2022, while investing in programs to preserve or restore ecosystems. The company stated that it would cut emissions from its operations and electricity use by 45 percent by 2030. Due to the COVID-19 pandemic and lack of content production, Netflix had a 14 percent drop in emissions in 2020.
Źródło: Wikipedia (Angielski), CC BY-SA 4.0 · Zobacz w Wikipedii ↗
Wyniki 10-letnie Trendy przychodów, zysku netto, marż i EPS
Wycena Wskaźniki P/E, P/S, P/B, EV/EBITDA — czy akcje są drogie, czy tanie?
| Wskaźnik | Trend 5-letni | NFLX | średnia z 5 lat | Mediana porównawcza | Werdykt |
|---|---|---|---|---|---|
| P/E (TTM) | -20.4średnia z 5 lat ≈195.2 | ≈195.2 | · | · | |
| P/S (TTM) | 5.8średnia z 5 lat ≈7.6 | ≈7.6 | 1.9 | Zawyżona wycena | |
| P/B (MRQ) | 9.3średnia z 5 lat ≈12.7 | ≈12.7 | 7.3 | Zawyżona wycena | |
| EV / EBITDA (TTM) | 19.3średnia z 5 lat ≈32.4 | ≈32.4 | · | · | |
| Cena / FCF (TTM) | 25.0średnia z 5 lat ≈-363.6 | ≈-363.6 | · | · | |
| Cena / Przepływy pieniężne (TTM) | 23.3średnia z 5 lat ≈173.2 | ≈173.2 | 24.0 | Zawyżona wycena | |
| EV / Przychody (TTM) | 5.9średnia z 5 lat ≈7.8 | ≈7.8 | · | · | |
| EV / FCF (TTM) | 25.5średnia z 5 lat ≈-376.3 | ≈-376.3 | · | · | |
| Cena / Wartość księgowa materialna (MRQ) | -75.8średnia z 5 lat ≈11.1 | ≈11.1 | · | · |
Mediana porównawcza jest obliczana na znormalizowanej podstawie dla każdej metryki i może nie zawsze odpowiadać podstawie TTM/MRQ pokazanej dla tej akcji.
Rentowność Marże brutto, operacyjne i netto; ROE, ROA, ROIC
| Wskaźnik | Trend 5-letni | NFLX | średnia z 5 lat | Mediana porównawcza | Werdykt |
|---|---|---|---|---|---|
| Marża Operacyjna (TTM) | 29.7%średnia z 5 lat ≈23.1% | ≈23.1% | 9.9% | Najwyższa półka | |
| Marża EBITDA (TTM) | 30.4%średnia z 5 lat ≈24.0% | ≈24.0% | 10.3% | Najwyższa półka | |
| Marża przed opodatkowaniem (TTM) | 34.1%średnia z 5 lat ≈21.7% | ≈21.7% | 10.3% | Najwyższa półka | |
| Marża Zysku Netto (TTM) | 28.2%średnia z 5 lat ≈18.8% | ≈18.8% | 7.3% | Najwyższa półka | |
| ROA (TTM) | 24.5%średnia z 5 lat ≈14.0% | ≈14.0% | 2.2% | Najwyższa półka | |
| ROE (TTM) | 49.5%średnia z 5 lat ≈31.8% | ≈31.8% | 6.2% | Najwyższa półka | |
| ROIC | 28.0%średnia z 5 lat ≈19.8% | ≈19.8% | 6.7% | Najwyższa półka |
Zdrowie finansowe Dług, płynność, wypłacalność — siła bilansu
| Wskaźnik | Trend 5-letni | NFLX | średnia z 5 lat | Mediana porównawcza | Werdykt |
|---|---|---|---|---|---|
| Dług / Kapitał Własny (MRQ) | 0.5średnia z 5 lat ≈0.7 | ≈0.7 | 0.4 | Wysokie zadłużenie | |
| Wskaźnik bieżący (MRQ) | 1.1średnia z 5 lat ≈1.1 | ≈1.1 | 1.0 | Zgodnie z | |
| Quick Ratio (Wskaźnik Szybkości) | 0.8średnia z 5 lat ≈0.8 | ≈0.8 | 0.7 | Zgodnie z | |
| Dług długoterminowy / Kapitał własny (MRQ) | 0.4średnia z 5 lat ≈0.7 | ≈0.7 | 0.4 | Zgodnie z |
Rozwój Wzrost przychodów, EPS i zysku netto: r/r, CAGR 3-letni, CAGR 5-letni
| Wskaźnik | Trend 5-letni | NFLX | średnia z 5 lat | Mediana porównawcza | Werdykt |
|---|---|---|---|---|---|
| Revenue YoY (Przychody R/R) | 15.8%średnia z 5 lat ≈12.7% | ≈12.7% | · | · | |
| Revenue CAGR 3Y (Przychody CAGR 3L) | 12.6%średnia z 5 lat ≈10.9% | ≈10.9% | · | · | |
| Revenue CAGR 5Y (Przychody CAGR 5L) | 12.6% | · | · | · | |
| EPS YoY | 27.8%średnia z 5 lat ≈15.6% | ≈15.6% | · | · | |
| Net Income YoY (Zysk Netto R/R) | 26.1%średnia z 5 lat ≈36.1% | ≈36.1% | · | · | |
| EPS CAGR 3Y (CAGR z EPS 3 lata) | -36.6%średnia z 5 lat ≈-40.8% | ≈-40.8% | · | · | |
| EPS CAGR 5Y (CAGR z EPS 5 lat) | -16.1% | · | · | · | |
| Net Income CAGR 3Y (CAGR z zysku netto 3 lata) | 34.7%średnia z 5 lat ≈26.4% | ≈26.4% | · | · | |
| Net Income CAGR 5Y (CAGR z zysku netto 5 lat) | 31.8% | · | · | · |
Efektywność kapitałowa Rotacja aktywów, rotacja zapasów, rotacja należności
| Wskaźnik | Trend 5-letni | NFLX | średnia z 5 lat | Mediana porównawcza | Werdykt |
|---|---|---|---|---|---|
| Asset Turnover (Rotacja aktywów) | 0.8średnia z 5 lat ≈0.7 | ≈0.7 | 0.6 | Najwyższa półka | |
| Revenue / Employee (Przychody / pracownika) | ≈$2.8M | · | · | · |
wartość · ≈ średnia z 5 lat · mediana branżowa · werdykt względem mediany
Historia zysków EPS faktyczny vs szacowany, zaskoczenie %, wskaźnik trafień, data następnych wyników
| Okres | Raport | EPS Actual | EPS Szacowany | Niespodzianka |
|---|---|---|---|---|
| 30 czerwca 2026 | Lip 16, 2026 | $0.80 | $0.80 | -0.52% |
| 31 marca 2026 | $0.70 | $0.78 | -10.2% | |
| 31 grudnia 2025 | $0.56 | $0.56 | -0.50% | |
| 30 września 2025 | $0.59 | $0.71 | -17.4% | |
| 30 czerwca 2025 | $0.72 | $0.72 | -0.40% | |
| 31 marca 2025 | $0.66 | $0.58 | 13.4% |
Pełne podstawowe wskaźniki Wszystkie wskaźniki roczne — rachunek zysków i strat, bilans, przepływy pieniężne
Rachunek zysków i strat
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $45.18B | $39.00B | $33.72B | $31.62B | $29.70B | $25.00B | $20.16B | $15.79B | $11.69B | $8.83B | $6.78B | $5.50B | |
| Cost of Revenue | $23.28B | $21.04B | $19.72B | $19.17B | $17.33B | $15.28B | $12.44B | $9.97B | $8.03B | $6.26B | $4.59B | $3.75B | |
| R&D Expense | $3.39B | $2.93B | $2.68B | $2.71B | $2.27B | $1.83B | $1.67B | $1.22B | $981M | $768M | $570M | $398M | |
| SG&A Expense | $1.89B | $1.70B | $1.72B | $1.57B | $1.35B | $1.08B | $914M | $630M | $431M | $316M | $407M | $270M | |
| Operating Income | $13.33B | $10.42B | $6.95B | $5.63B | $6.19B | $4.59B | $2.60B | $1.61B | $839M | $380M | $306M | $403M | |
| Interest Expense | · | · | $700M | $706M | $766M | $767M | $626M | $420M | $238M | $150M | $133M | $50M | |
| Interest Income | · | $294M | $281M | $60M | · | · | · | · | · | · | · | · | |
| Other Non-op | $172M | $267M | $-49M | $337M | $411M | $-618M | $84M | $42M | $-115M | $31M | $-31M | $-3M | |
| Pretax Income | $12.72B | $9.97B | $6.21B | $5.26B | $5.84B | $3.20B | $2.06B | $1.23B | $485M | $261M | $142M | $349M | |
| Income Tax | $1.74B | $1.25B | $797M | $772M | $724M | $438M | $195M | $15M | $-74M | $74M | $19M | $83M | |
| Net Income | $10.98B | $8.71B | $5.41B | $4.49B | $5.12B | $2.76B | $1.87B | $1.21B | $559M | $187M | $123M | $267M | |
| EPS (Basic) | $2.58 | $2.03 | $1.22 | $10.10 | $11.55 | $6.26 | $4.26 | $2.78 | $1.29 | $0.44 | $0.29 | $0.63 | |
| EPS (Diluted) | $2.53 | $1.98 | $1.20 | $9.95 | $11.24 | $6.08 | $4.13 | $2.68 | $1.25 | $0.43 | $0.28 | $0.62 | |
| Shares (Basic) | 4,249,512,000 | 4,295,191,000 | 4,415,712,000 | 444,698,000 | 443,155,000 | 440,922,000 | 437,799,000 | 435,374,000 | 431,885,000 | 428,822,000 | 425,889,000 | 420,544,000 | |
| Shares (Diluted) | 4,343,863,000 | 4,392,608,000 | 4,494,966,000 | 451,290,000 | 455,372,000 | 454,208,000 | 451,765,000 | 451,244,000 | 446,814,000 | 438,652,000 | 436,456,000 | 431,894,000 | |
| EBITDA | $13.66B | $10.75B | $7.31B | $5.97B | $6.40B | $4.70B | $2.71B | · | $911M | $437M | $368M | $457M |
Bilans
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $9.03B | $7.80B | $7.12B | $5.15B | $6.03B | $8.21B | $5.02B | $3.79B | $2.82B | $1.47B | $1.81B | $1.11B | |
| Short-term Investments | $29M | $1.78B | $21M | $911M | $0 | · | · | · | $0 | $266M | $501M | $495M | |
| Prepaid Expense | $498M | $432M | $409M | $393M | $324M | $203M | $181M | $179M | · | · | · | · | |
| Other Current Assets | $3.96B | $3.52B | $2.78B | $3.21B | $2.04B | $1.56B | $1.16B | $748M | $536M | $260M | $215M | $152M | |
| Current Assets | $13.02B | $13.10B | $9.92B | $9.27B | $8.07B | $9.76B | $6.18B | $9.69B | $7.67B | $5.72B | $5.43B | $3.93B | |
| PP&E (Net) | $2.00B | $1.59B | $1.49B | $1.40B | $1.32B | $960M | $565M | $418M | $319M | $250M | $173M | $150M | |
| PP&E (Gross) | $3.10B | $2.51B | $2.35B | $2.15B | $1.94B | $1.45B | $981M | $787M | $641M | $545M | $471M | $415M | |
| Accum. Depreciation | $1.10B | $918M | $855M | $754M | $616M | $495M | $416M | $369M | $322M | $294M | $297M | $265M | |
| Intangibles | $32.78B | $32.45B | · | · | · | · | · | · | · | · | · | · | |
| Other Non-current Assets | $7.79B | $6.48B | $5.66B | $5.19B | $4.27B | $3.17B | $2.73B | $911M | $652M | $341M | $285M | $192M | |
| Total Assets | $55.60B | $53.63B | $48.73B | $48.59B | $44.58B | $39.28B | $33.98B | $25.97B | $19.01B | $13.59B | $10.20B | $7.04B | |
| Accounts Payable | $901M | $900M | $747M | $672M | $837M | $656M | $674M | $563M | $360M | $313M | $253M | $202M | |
| Accrued Liabilities | $3.22B | $2.16B | $1.80B | $1.51B | $1.45B | $1.10B | $843M | $482M | $315M | $198M | $140M | $70M | |
| Short-term Debt | $999M | $1.78B | $400M | $0 | $700M | $500M | $0 | · | · | · | · | · | |
| Current Liabilities | $10.98B | $10.76B | $8.86B | $7.93B | $8.49B | $7.81B | $6.86B | $6.49B | $5.47B | $4.59B | $3.53B | $2.66B | |
| Capital Leases | $2.05B | $1.98B | $2.05B | $2.22B | $2.41B | $1.95B | $1.42B | · | · | · | · | · | |
| Other Non-current Liabilities | $2.96B | $2.55B | $2.56B | $2.45B | $2.46B | $1.98B | $1.44B | $129M | $135M | $61M | $52M | $60M | |
| Total Liabilities | $28.98B | $28.89B | $28.14B | $27.82B | $28.74B | $28.22B | $26.39B | $20.74B | $15.43B | $10.91B | $7.98B | $5.18B | |
| Long-term Debt | · | · | · | · | · | $21.86B | $20.72B | $14.87B | $9.05B | · | · | · | |
| Total Debt | $14.46B | $15.58B | $14.54B | $14.35B | $15.39B | $16.31B | $14.76B | · | $6.50B | $3.36B | $2.37B | $900M | |
| Common Stock | $7.29B | $6.25B | $5.15B | $4.64B | $4.02B | $3.45B | $2.79B | $2.32B | $1.87B | $1.60B | $1.32B | $1.04B | |
| Retained Earnings | $42.28B | $31.30B | $22.59B | $17.18B | $12.69B | $7.57B | $4.81B | $2.94B | $1.73B | $1.13B | $942M | $819M | |
| Treasury Stock | $22.37B | $13.17B | $6.92B | $824M | $824M | $0 | · | · | · | · | · | · | |
| AOCI | $-580M | $362M | $-224M | $-217M | $-40M | $44M | $-24M | $-20M | $-21M | $-49M | $-43M | $-4M | |
| Stockholders' Equity | $26.62B | $24.74B | $20.59B | $20.78B | $15.85B | $11.07B | $7.58B | $5.24B | $3.58B | $2.68B | $2.22B | $1.86B | |
| Liabilities + Equity | $55.60B | $53.63B | $48.73B | $48.59B | $44.58B | $39.28B | $33.98B | $25.97B | $19.01B | $13.59B | $10.20B | $7.04B | |
| Shares Outstanding | 4,222,162,150 | 4,277,571,000 | 432,759,584 | 445,346,776 | 443,963,107 | 442,895,261 | 438,806,649 | 436,598,597 | 433,392,686 | 430,054,212 | 427,940,440 | 422,910,887 |
Przepływy pieniężne
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $333M | $329M | $357M | $337M | $208M | $116M | $104M | $83M | $72M | $58M | $62M | $54M | |
| Stock-based Comp | $368M | $273M | $339M | $575M | $403M | $415M | $405M | $321M | $182M | $174M | $125M | $115M | |
| Deferred Tax | $-449M | $-591M | $-543M | $-135M | $200M | $70M | $-95M | $-86M | $-209M | $-47M | $-59M | $-30M | |
| Other Non-cash | $-1.08B | $-1.36B | $1.71B | $-3.24B | $-5.53B | $-935M | $-5.17B | · | $-2.39B | $-1.85B | $-1.00B | $-390M | |
| Operating Cash Flow | $10.15B | $7.36B | $7.27B | $2.03B | $393M | $2.43B | $-2.89B | $-2.68B | $-1.79B | $-1.47B | $-749M | $16M | |
| CapEx | $688M | $440M | $349M | $408M | $525M | $498M | $253M | $174M | $173M | $108M | $91M | $70M | |
| Investing Cash Flow | $1.04B | $-2.18B | $542M | $-2.08B | $-1.34B | $-505M | $-387M | $-339M | $34M | $50M | $-179M | $-43M | |
| Debt Issued | · | · | · | · | · | · | · | · | $3.02B | $1.00B | $1.50B | $400M | |
| Net Debt Issued | $-1.83B | $-400M | $0 | $-700M | $-500M | · | · | · | $3.02B | $1.00B | $1.50B | $400M | |
| Stock Issued | · | · | · | · | $174M | $235M | $72M | $125M | $88M | $37M | $78M | $61M | |
| Stock Repurchased | $9.13B | $6.26B | $6.05B | $0 | $600M | $0 | $0 | · | · | · | · | · | |
| Net Stock Activity | $-9.13B | $-6.26B | $-6.05B | $0 | $-426M | $235M | $72M | · | $88M | $37M | $78M | $61M | |
| Financing Cash Flow | $-10.35B | $-4.07B | $-5.95B | $-664M | $-1.15B | $1.24B | $4.51B | $4.05B | $3.08B | $1.09B | $1.64B | $542M | |
| Net Change in Cash | $1.23B | $689M | $1.95B | $-885M | $-2.18B | $3.20B | $1.23B | $989M | $1.36B | $-342M | $696M | $509M | |
| Taxes Paid | $2.22B | $1.64B | $1.16B | · | · | · | · | · | · | · | · | · | |
| Free Cash Flow | $9.46B | $6.92B | $6.93B | $1.62B | $-132M | $1.93B | $-3.14B | · | $-1.96B | $-1.58B | $-841M | $-53M | |
| Levered FCF | · | · | $6.32B | $1.02B | $-803M | $1.27B | $-3.71B | · | $-2.23B | $-1.69B | $-955M | $-92M |
Rentowność
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | 29.5% | 26.7% | 20.6% | 17.8% | 20.9% | 18.3% | 12.9% | · | 7.2% | 4.3% | 4.5% | 7.3% | |
| Net Margin | 24.3% | 22.3% | 16.0% | 14.2% | 17.2% | 11.1% | 9.3% | · | 4.8% | 2.1% | 1.8% | 4.9% | |
| Pretax Margin | 28.2% | 25.6% | 18.4% | 16.7% | 19.7% | 12.8% | 10.2% | · | 4.2% | 2.9% | 2.1% | 6.3% | |
| EBITDA Margin | 30.2% | 27.6% | 21.7% | 18.9% | 21.6% | 18.8% | 13.4% | · | 7.8% | 5.0% | 5.4% | 8.3% | |
| ROA | 20.1% | 17.0% | 11.1% | 9.6% | 12.2% | 7.5% | 6.2% | · | 3.4% | 1.6% | 1.4% | 4.3% | |
| ROE | 42.6% | 36.7% | 25.3% | 21.8% | 32.8% | 25.8% | 25.9% | · | 17.8% | 7.6% | 6.0% | 16.7% | |
| ROIC | 28.0% | 22.6% | 17.2% | 13.7% | 17.4% | 14.5% | 10.5% | · | 9.6% | 4.5% | 5.8% | 11.2% |
Płynność i wypłacalność
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.2 | 1.2 | 1.1 | 1.2 | 1.0 | 1.3 | 0.9 | · | 1.4 | 1.2 | 1.5 | 1.5 | |
| Quick Ratio | 0.8 | 0.9 | 0.8 | 0.8 | 0.7 | 1.1 | 0.7 | · | 0.5 | 0.4 | 0.7 | 0.6 | |
| Debt / Equity | 0.5 | 0.6 | 0.7 | 0.7 | 1.0 | 1.5 | 1.9 | · | 1.8 | 1.3 | 1.1 | 0.5 | |
| LT Debt / Equity | 0.5 | 0.6 | 0.7 | 0.7 | 0.9 | 1.4 | 1.9 | · | 1.8 | 1.3 | 1.1 | 0.5 | |
| Interest Coverage | · | · | 9.9 | 8.0 | 8.1 | 6.0 | 4.2 | · | 3.5 | 2.5 | 2.3 | 8.0 |
Efektywność
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.8 | 0.8 | 0.7 | 0.7 | 0.7 | 0.7 | 0.7 | · | 0.7 | 0.7 | 0.8 | 0.9 |
Na akcję
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $6.30 | $57.84 | $47.57 | $46.65 | $35.70 | $24.98 | $17.28 | · | $8.26 | $6.23 | $5.20 | $30.75 | |
| Revenue / Share | $10.40 | $88.79 | $75.02 | $70.06 | $65.22 | $55.03 | $44.62 | · | $26.17 | $20.13 | $15.53 | $89.22 | |
| Cash Flow / Share | $2.34 | $16.76 | $16.18 | $4.49 | $0.86 | $5.34 | $-6.39 | · | $-4.00 | $-3.36 | $-1.72 | $0.27 | |
| Cash / Share | $2.14 | $18.25 | $16.45 | $11.56 | $13.58 | $18.53 | $11.44 | · | $6.51 | $3.41 | $4.23 | $18.43 | |
| EPS (TTM) | $2.53 | $1.98 | $1.20 | $9.95 | $11.24 | $6.08 | $4.13 | $2.68 | $1.25 | $0.43 | $0.28 | $0.62 |
Stopy Wzrostu
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue YoY | 15.8% | 15.7% | 6.7% | 6.5% | 18.8% | · | · | · | · | · | · | · | |
| Revenue CAGR 3Y | 12.6% | 9.5% | 10.5% | · | · | · | · | · | · | · | · | · | |
| Revenue CAGR 5Y | 12.6% | · | · | · | · | · | · | · | · | · | · | · | |
| EPS YoY | 27.8% | 65.0% | -87.9% | -11.5% | 84.9% | · | · | · | · | · | · | · | |
| EPS CAGR 3Y | -36.6% | -43.9% | -41.8% | · | · | · | · | · | · | · | · | · | |
| EPS CAGR 5Y | -16.1% | · | · | · | · | · | · | · | · | · | · | · | |
| Net Income YoY | 26.1% | 61.1% | 20.4% | -12.2% | 85.3% | · | · | · | · | · | · | · | |
| Net Income CAGR 3Y | 34.7% | 19.4% | 25.1% | · | · | · | · | · | · | · | · | · | |
| Net Income CAGR 5Y | 31.8% | · | · | · | · | · | · | · | · | · | · | · |
Wycena (TTM)
| Wskaźnik | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $45.18B | $39.00B | $33.72B | $31.62B | $29.70B | $25.00B | $20.16B | $15.79B | $11.69B | $8.83B | $6.78B | $5.50B | |
| Net Income TTM | $10.98B | $8.71B | $5.41B | $4.49B | $5.12B | $2.76B | $1.87B | $1.21B | $559M | $187M | $123M | $267M | |
| Market Cap | $395.87B | $381.27B | $210.70B | $131.32B | $267.46B | $239.49B | $141.98B | · | $83.19B | $53.24B | $48.95B | $2.95B | |
| Enterprise Value | $401.27B | $387.27B | $218.11B | $139.62B | $276.83B | $247.59B | $151.73B | · | $86.87B | $54.87B | $49.01B | $2.24B | |
| P/E | 37.1 | 450.2 | 405.7 | 29.6 | 53.6 | 88.9 | 78.3 | 99.9 | 153.6 | 287.9 | 408.5 | 78.7 | |
| P/S | 8.8 | 9.8 | 6.2 | 4.2 | 9.0 | 9.6 | 7.0 | · | 7.1 | 6.0 | 7.2 | 0.5 | |
| P/B | 14.9 | 15.4 | 10.2 | 6.3 | 16.9 | 21.6 | 18.7 | · | 23.2 | 19.9 | 22.0 | 1.6 | |
| P / Tangible Book | · | · | 10.2 | 6.3 | 16.9 | 21.6 | · | · | · | · | · | · | |
| P / Cash Flow | 39.0 | 51.8 | 29.0 | 64.8 | 681.2 | 98.7 | -49.2 | · | -46.6 | -36.1 | -65.3 | 178.9 | |
| P / FCF | 41.8 | 55.1 | 30.4 | 81.1 | -2026.6 | 124.1 | -45.2 | · | -42.5 | -33.7 | -58.2 | -55.4 | |
| EV / EBITDA | 29.4 | 36.0 | 29.8 | 23.4 | 43.2 | 52.7 | 56.0 | · | 95.4 | 125.5 | 133.1 | 4.9 | |
| EV / FCF | 42.4 | 55.9 | 31.5 | 86.3 | -2097.6 | 128.3 | -48.3 | · | -44.3 | -34.7 | -58.3 | -42.1 | |
| EV / Revenue | 8.9 | 9.9 | 6.5 | 4.4 | 9.3 | 9.9 | 7.5 | · | 7.4 | 6.2 | 7.2 | 0.4 | |
| Earnings Yield | 2.7% | 0.22% | 0.25% | 3.4% | 1.9% | 1.1% | 1.3% | 1.0% | 0.65% | 0.35% | 0.24% | 1.3% |
Rachunek zysków i strat
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $12.56B | $12.25B | $12.05B | $11.51B | $11.08B | $10.54B | $10.25B | $9.82B | $9.56B | $9.37B | $8.83B | $8.54B | $8.19B | $8.16B | $7.85B | $7.93B | |
| Cost of Revenue | $6.04B | $5.89B | $6.52B | $6.16B | $5.33B | $5.26B | $5.77B | $5.12B | $5.17B | $4.98B | $5.31B | $4.93B | $4.67B | $4.80B | $5.40B | $4.79B | |
| R&D Expense | $1.01B | $960M | $890M | $854M | $825M | $823M | $777M | $735M | $711M | $702M | $673M | $657M | $658M | $687M | $674M | $663M | |
| SG&A Expense | $499M | $603M | $568M | $458M | $441M | $421M | $454M | $417M | $427M | $404M | $439M | $479M | $401M | $401M | $392M | $373M | |
| Operating Income | $4.19B | $3.96B | $2.96B | $3.25B | $3.77B | $3.35B | $2.27B | $2.91B | $2.60B | $2.63B | $1.50B | $1.92B | $1.83B | $1.71B | $550M | $1.53B | |
| Interest Expense | · | · | · | · | · | · | · | $185M | $168M | $173M | · | $176M | $175M | $174M | · | $173M | |
| Other Non-op | $52M | $2.85B | $45M | $36M | $40M | $51M | $54M | $-22M | $79M | $155M | $-173M | $168M | $27M | $-71M | $-340M | $261M | |
| Pretax Income | $4.07B | $6.55B | $2.77B | $3.11B | $3.63B | $3.21B | $2.13B | $2.70B | $2.51B | $2.61B | $1.15B | $1.91B | $1.68B | $1.47B | $39M | $1.62B | |
| Income Tax | $667M | $1.26B | $349M | $562M | $506M | $323M | $266M | $339M | $367M | $282M | $210M | $232M | $192M | $164M | $-16M | $224M | |
| Net Income | $3.40B | $5.28B | $2.42B | $2.55B | $3.13B | $2.89B | $1.87B | $2.36B | $2.15B | $2.33B | $938M | $1.68B | $1.49B | $1.31B | $55M | $1.40B | |
| EPS (Basic) | $0.81 | $1.25 | $-11.45 | $6.00 | $0.74 | $0.68 | $-13.88 | $5.52 | $4.99 | $5.40 | $-8.86 | $3.80 | $3.35 | $2.93 | $0.12 | $3.14 | |
| EPS (Diluted) | $0.80 | $1.23 | $-11.19 | $5.87 | $0.72 | $0.66 | $-13.58 | $5.40 | $4.88 | $5.28 | $-8.70 | $3.73 | $3.29 | $2.88 | $0.12 | $3.10 | |
| Shares (Basic) | 4,189,303,000 | 4,222,787,000 | · | 424,455,000 | 4,252,112,000 | 4,272,695,000 | · | 428,239,000 | 430,065,000 | 432,090,000 | · | 441,537,000 | 443,881,000 | 445,244,000 | · | 444,878,000 | |
| Shares (Diluted) | 4,261,300,000 | 4,298,437,000 | · | 434,039,000 | 4,348,825,000 | 4,369,623,000 | · | 437,898,000 | 439,739,000 | 441,654,000 | · | 450,011,000 | 451,572,000 | 452,417,000 | · | 450,344,000 | |
| EBITDA | $4.29B | $4.06B | · | $3.34B | $3.85B | $3.43B | · | $2.99B | $2.68B | $2.72B | · | $2.01B | $1.92B | $1.80B | · | $1.62B |
Bilans
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $9.10B | $12.26B | $9.03B | $9.29B | $8.18B | $7.20B | $7.80B | $7.46B | $6.62B | $7.02B | · | $7.35B | $7.66B | $6.71B | · | $6.11B | |
| Short-term Investments | $29M | $29M | $29M | $37M | $213M | $1.17B | $1.78B | $1.77B | $31M | $21M | · | $514M | $914M | $1.11B | · | · | |
| Prepaid Expense | $585M | $602M | $498M | $468M | $451M | $484M | $432M | $436M | $446M | $454M | · | $482M | $482M | $486M | · | $392M | |
| Other Current Assets | $4.73B | $4.78B | $3.96B | $3.64B | $3.60B | $3.33B | $3.52B | $2.91B | $2.96B | $2.88B | · | $2.91B | $2.93B | $2.66B | · | $2.70B | |
| Current Assets | $13.85B | $17.07B | $13.02B | $12.96B | $11.99B | $11.70B | $13.10B | $12.13B | $9.62B | $9.92B | · | $10.78B | $11.51B | $10.48B | · | $8.82B | |
| PP&E (Net) | $2.40B | $2.15B | $2.00B | $1.84B | $1.74B | $1.64B | $1.59B | $1.57B | $1.51B | $1.50B | · | $1.50B | $1.47B | $1.41B | · | $1.37B | |
| PP&E (Gross) | $3.62B | $3.30B | $3.10B | $2.88B | $2.78B | $2.62B | $2.51B | $2.49B | $2.43B | $2.39B | · | $2.40B | $2.34B | $2.22B | · | $2.08B | |
| Accum. Depreciation | $1.22B | $1.16B | $1.10B | $1.05B | $1.04B | $976M | $918M | $922M | $915M | $885M | · | $903M | $871M | $808M | · | $710M | |
| Intangibles | $33.84B | $33.38B | $32.78B | $32.64B | $32.09B | $32.04B | $32.45B | · | · | · | · | · | · | · | · | · | |
| Other Non-current Assets | $8.36B | $8.42B | $7.79B | $7.49B | $7.27B | $6.70B | $6.48B | $6.41B | $6.05B | $5.74B | · | $5.47B | $5.32B | $5.25B | · | $4.60B | |
| Total Assets | $58.45B | $61.02B | $55.60B | $54.93B | $53.10B | $52.09B | $53.63B | $52.28B | $49.10B | $48.83B | · | $49.50B | $50.82B | $49.49B | · | $47.56B | |
| Accounts Payable | $815M | $895M | $901M | $793M | $633M | $614M | $900M | $642M | $599M | $607M | · | $534M | $615M | $592M | · | $560M | |
| Accrued Liabilities | $3.17B | $4.44B | $3.22B | $3.11B | $2.49B | $2.36B | $2.16B | $2.24B | $1.88B | $1.98B | · | $1.84B | $1.91B | $1.72B | · | $1.80B | |
| Short-term Debt | $2.48B | $999M | $999M | $0 | $0 | $1.01B | $1.78B | $1.82B | $1.80B | $799M | · | $400M | $399M | $399M | · | $0 | |
| Current Liabilities | $12.13B | $12.13B | $10.98B | $9.73B | $8.94B | $9.72B | $10.76B | $10.71B | $10.14B | $9.29B | · | $8.34B | $8.68B | $8.32B | · | $7.77B | |
| Capital Leases | $1.90B | $1.95B | $2.05B | $2.16B | $2.03B | $1.97B | $1.98B | $2.09B | $2.13B | $2.10B | · | $2.09B | $2.15B | $2.16B | · | $2.21B | |
| Other Non-current Liabilities | $2.71B | $2.77B | $2.96B | $3.19B | $3.15B | $2.63B | $2.55B | $2.77B | $2.64B | $2.59B | · | $2.49B | $2.39B | $2.40B | · | $2.42B | |
| Total Liabilities | $28.30B | $29.89B | $28.98B | $28.98B | $28.15B | $28.06B | $28.89B | $29.56B | $26.99B | $27.46B | · | $27.39B | $27.99B | $27.66B | · | $27.03B | |
| Total Debt | $14.31B | $14.36B | · | $14.46B | $14.45B | $15.02B | · | $15.98B | $13.98B | $14.02B | · | $14.30B | $14.47B | $14.44B | · | $13.89B | |
| Common Stock | $7.67B | $7.48B | $7.29B | $7.08B | $6.93B | $6.68B | $6.25B | $5.89B | $5.68B | $5.49B | · | $5.01B | $4.87B | $4.76B | · | $4.47B | |
| Retained Earnings | $50.97B | $47.56B | $42.28B | $39.86B | $37.32B | $34.19B | $31.30B | $29.43B | $27.07B | $24.92B | · | $21.65B | $19.97B | $18.49B | · | $17.13B | |
| Treasury Stock | $28.39B | $23.68B | $22.37B | $20.27B | $18.39B | $16.75B | $13.17B | $12.25B | $10.55B | $8.93B | · | $4.40B | $1.88B | $1.23B | · | $824M | |
| AOCI | $-97M | $-235M | $-580M | $-719M | $-905M | $-86M | $362M | $-345M | $-89M | $-112M | · | $-156M | $-139M | $-192M | · | $-248M | |
| Stockholders' Equity | $30.15B | $31.13B | $26.62B | $25.95B | $24.95B | $24.03B | $24.74B | $22.72B | $22.11B | $21.37B | $20.59B | $22.11B | $22.83B | $21.83B | $20.78B | $20.53B | |
| Liabilities + Equity | $58.45B | $61.02B | $55.60B | $54.93B | $53.10B | $52.09B | $53.63B | $52.28B | $49.10B | $48.83B | · | $49.50B | $50.82B | $49.49B | · | $47.56B | |
| Shares Outstanding | 4,163,939,676 | 4,212,794,271 | 4,222,162,150 | 423,732,334 | 424,926,346 | 425,683,210 | 4,277,571,000 | 427,458,114 | 429,164,615 | 430,964,991 | · | 437,679,669 | 443,146,751 | 444,536,878 | 445,346,776 | 445,020,494 |
Przepływy pieniężne
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $101M | $99M | $86M | $87M | $80M | $80M | $80M | $81M | $81M | $87M | $87M | $91M | $89M | $90M | $93M | $85M | |
| Stock-based Comp | $131M | $140M | $135M | $81M | $81M | $72M | $62M | $66M | $69M | $76M | $83M | $80M | $78M | $99M | $154M | $152M | |
| Deferred Tax | · | · | · | · | · | · | · | · | · | · | · | · | · | · | $108M | $-58M | |
| Other Non-cash | $-1.89B | $-232M | · | $110M | $-863M | $-253M | · | $-189M | $-1.01B | $-283M | · | $145M | $-215M | $684M | · | $-1.02B | |
| Operating Cash Flow | $1.74B | $5.29B | $2.11B | $2.83B | $2.42B | $2.79B | $1.54B | $2.32B | $1.29B | $2.21B | $1.66B | $1.99B | $1.44B | $2.18B | $444M | $557M | |
| CapEx | $219M | $196M | $239M | $165M | $156M | $128M | $159M | $127M | $78M | $76M | $82M | $104M | $101M | $62M | $112M | $85M | |
| Investing Cash Flow | $-219M | $-782M | $-257M | $44M | $769M | $486M | $-159M | $-1.87B | $-78M | $-76M | $412M | $296M | $98M | $-264M | $-1.59B | $-85M | |
| Net Debt Issued | $0 | $0 | · | $0 | $-1.03B | $-800M | · | $0 | $0 | $-400M | · | $0 | $0 | $0 | · | $0 | |
| Stock Repurchased | $4.71B | $1.27B | $2.08B | $1.86B | $1.65B | $3.54B | $964M | $1.70B | $1.60B | $2.00B | $2.50B | $2.50B | $645M | $400M | $0 | $0 | |
| Net Stock Activity | $-4.71B | $-1.27B | · | $-1.86B | $-1.65B | $-3.54B | · | $-1.70B | $-1.60B | $-2.00B | · | $-2.50B | $-645M | $-400M | · | $0 | |
| Financing Cash Flow | $-4.67B | $-1.23B | $-2.08B | $-1.74B | $-2.50B | $-4.03B | $-679M | $227M | $-1.49B | $-2.13B | $-2.45B | $-2.48B | $-649M | $-374M | $7M | $4M | |
| Net Change in Cash | $-3.16B | $3.23B | $-252M | $1.11B | $977M | $-603M | $348M | $832M | $-400M | $-92M | $-238M | $-309M | $928M | $1.57B | $-970M | $296M | |
| Free Cash Flow | $1.53B | $5.09B | · | $2.66B | $2.27B | $2.66B | · | $2.19B | $1.21B | $2.14B | · | $1.89B | $1.34B | $2.12B | · | $472M | |
| Levered FCF | · | · | · | · | · | · | · | $2.03B | $1.07B | $1.98B | · | $1.73B | $1.18B | $1.96B | · | $323M |
Rentowność
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | 33.4% | 32.3% | · | 28.2% | 34.1% | 31.8% | · | 29.6% | 27.2% | 28.1% | · | 22.4% | 22.3% | 21.0% | · | 19.3% | |
| Net Margin | 27.1% | 43.1% | · | 22.1% | 28.2% | 27.4% | · | 24.1% | 22.5% | 24.9% | · | 19.6% | 18.2% | 16.0% | · | 17.6% | |
| Pretax Margin | 32.4% | 53.4% | · | 27.0% | 32.8% | 30.5% | · | 27.5% | 26.3% | 27.9% | · | 22.4% | 20.5% | 18.0% | · | 20.5% | |
| EBITDA Margin | 34.2% | 33.1% | · | 29.0% | 34.8% | 32.5% | · | 30.4% | 28.1% | 29.0% | · | 23.5% | 23.4% | 22.1% | · | 20.4% | |
| ROA | 6.1% | 9.3% | · | 4.8% | 6.1% | 5.7% | · | 4.6% | 4.3% | 4.7% | · | 3.5% | 3.1% | 2.8% | · | 3.1% | |
| ROE | 12.3% | 19.2% | · | 10.5% | 13.3% | 12.7% | · | 10.5% | 9.6% | 10.8% | · | 7.9% | 7.1% | 6.6% | · | 7.8% | |
| ROIC | 7.9% | 7.0% | · | 6.6% | 8.2% | 7.7% | · | 6.6% | 6.2% | 6.6% | · | 4.6% | 4.3% | 4.2% | · | 3.8% |
Płynność i wypłacalność
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.1 | 1.4 | · | 1.3 | 1.3 | 1.2 | · | 1.1 | 0.9 | 1.1 | · | 1.3 | 1.3 | 1.3 | · | 1.1 | |
| Quick Ratio | 0.8 | 1.0 | · | 1.0 | 0.9 | 0.9 | · | 0.9 | 0.7 | 0.8 | · | 0.9 | 1.0 | 0.9 | · | 0.8 | |
| Debt / Equity | 0.5 | 0.5 | · | 0.6 | 0.6 | 0.6 | · | 0.7 | 0.6 | 0.7 | · | 0.6 | 0.6 | 0.7 | · | 0.7 | |
| LT Debt / Equity | 0.4 | 0.4 | · | 0.6 | 0.6 | 0.6 | · | 0.6 | 0.6 | 0.6 | · | 0.6 | 0.6 | 0.6 | · | 0.7 | |
| Interest Coverage | · | · | · | · | · | · | · | 15.7 | 15.5 | 15.2 | · | 10.9 | 10.5 | 9.8 | · | 8.9 |
Efektywność
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 |
Na akcję
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $7.24 | $7.39 | · | $61.25 | $58.72 | $56.45 | · | $53.15 | $51.52 | $49.58 | · | $50.51 | $51.52 | $49.10 | · | $46.13 | |
| Revenue / Share | $2.95 | $2.85 | · | $26.52 | $25.48 | $24.13 | · | $22.44 | $21.74 | $21.22 | · | $18.98 | $18.13 | $18.04 | · | $17.60 | |
| Cash Flow / Share | $0.41 | $1.23 | · | $6.51 | $5.57 | $6.38 | · | $5.30 | $2.94 | $5.01 | · | $4.43 | $3.19 | $4.82 | · | $1.24 | |
| Cash / Share | $2.19 | $2.91 | · | $21.92 | $19.24 | $16.91 | · | $17.45 | $15.44 | $16.30 | · | $16.80 | $17.29 | $15.10 | · | $13.74 | |
| EPS (TTM) | $-3.29 | $-3.37 | · | $-6.33 | $-6.80 | $-2.64 | · | $6.86 | $5.19 | $3.60 | · | $10.02 | $9.39 | $9.30 | · | $11.16 |
Wycena (TTM)
| Wskaźnik | Trend | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $48.37B | $46.89B | · | $43.38B | $41.69B | $40.17B | · | $37.59B | $36.30B | $34.93B | · | $32.74B | $32.13B | $31.91B | · | $31.47B | |
| Net Income TTM | $13.65B | $13.37B | · | $10.43B | $10.25B | $9.27B | · | $7.78B | $7.09B | $6.44B | · | $4.53B | $4.25B | $4.20B | · | $5.04B | |
| Market Cap | $297.31B | $405.06B | · | $508.02B | $569.03B | $396.96B | · | $303.18B | $289.63B | $261.74B | · | $165.27B | $195.20B | $153.58B | · | $104.78B | |
| Enterprise Value | $302.49B | $407.13B | · | $513.16B | $575.09B | $403.61B | · | $309.94B | $296.96B | $268.71B | · | $171.70B | $201.09B | $160.19B | · | $112.55B | |
| P/E | -21.7 | -28.5 | · | -189.4 | -196.9 | -353.2 | · | 103.4 | 130.0 | 168.7 | · | 37.7 | 46.9 | 37.1 | · | 21.1 | |
| P/S | 6.1 | 8.6 | · | 11.7 | 13.6 | 9.9 | · | 8.1 | 8.0 | 7.5 | · | 5.0 | 6.1 | 4.8 | · | 3.3 | |
| P/B | 9.9 | 13.0 | · | 19.6 | 22.8 | 16.5 | · | 13.3 | 13.1 | 12.3 | · | 7.5 | 8.5 | 7.0 | · | 5.1 | |
| P / Tangible Book | · | · | · | · | · | · | · | 13.3 | 13.1 | 12.3 | · | 7.5 | 8.5 | 7.0 | · | 5.1 | |
| P / Cash Flow | 170.5 | 76.6 | · | 179.8 | 234.8 | 142.3 | · | 130.6 | 224.4 | 118.3 | · | 83.0 | 135.5 | 70.5 | · | 188.2 | |
| EV / Revenue | 6.3 | 8.7 | · | 11.8 | 13.8 | 10.0 | · | 8.2 | 8.2 | 7.7 | · | 5.2 | 6.3 | 5.0 | · | 3.6 | |
| Earnings Yield | -4.6% | -3.5% | · | -0.53% | -0.51% | -0.28% | · | 0.97% | 0.77% | 0.59% | · | 2.6% | 2.1% | 2.7% | · | 4.7% |
Najnowszy okres po lewej · wartości null pokazane jako ·
Sprawozdania finansowe Rachunek zysków i strat, bilans, przepływy pieniężne — roczne, ostatnie 5 lat
| Wskaźnik | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Przychody | $45.18B | $39.00B | $33.72B | $31.62B | $29.70B |
| Marża Operacyjna % | 29.5% | 26.7% | 20.6% | 17.8% | 20.9% |
| Zysk netto | $10.98B | $8.71B | $5.41B | $4.49B | $5.12B |
| Rozwodniony EPS | $2.53 | $1.98 | $1.20 | $9.95 | $11.24 |
| Wskaźnik | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Dług / Kapitał Własny | 0.5 | 0.6 | 0.7 | 0.7 | 1.0 |
| Wskaźnik bieżący | 1.2 | 1.2 | 1.1 | 1.2 | 1.0 |
| Wskaźnik Szybkości | 0.8 | 0.9 | 0.8 | 0.8 | 0.7 |
| Wskaźnik | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Wolny przepływ pieniężny | $9.46B | $6.92B | $6.93B | $1.62B | $-132M |
Właściciele instytucjonalni (13F) 3 778 emitentów · $299.3B łącznie · Na dzień 30 września 2026
Instytucje, które zgłaszają posiadanie tych akcji w swoich kwartalnych zgłoszeniach SEC Form 13F. Tylko pozycje długie; pojedynczy zgłaszający może pojawić się dwukrotnie dla oddzielnych transz opcji. Duże przeciwstawne pozycje put/call zazwyczaj odzwierciedlają działalność market-makingową lub zabezpieczone zapasy, a nie przekonanie kierunkowe.
| Nowe pozycje | Zamknięte pozycje | Zwiększone | Zmniejszony | Zmiana liczby akcji netto |
|---|---|---|---|---|
| 223 (-245 vs poprzedni kw.) | 372 (+149 vs poprzedni kw.) | 1 531 (-372 vs poprzedni kw.) | 1 408 (+317 vs poprzedni kw.) | -18.2M |
Porównano z Q1 2026. Zgłoszenia SEC Form 13F są wymagane w ciągu 45 dni od końca kwartału plus krótki bufor dla spóźnionych zgłoszeń — kwartały mieszczące się jeszcze w tym terminie są pomijane na rzecz ostatniej w pełni zgłoszonej pary.
| Instytucja | Wartość | Akcje | % z śledzonych 13F | Typ |
|---|---|---|---|---|
| VANGUARD GROUP INC | $36 567 804 619 | 390 014 981 | 12,22% | Akcje |
| BlackRock, Inc. | $24 902 220 805 | 348 770 600 | 8,32% | Akcje |
| VANGUARD CAPITAL MANAGEMENT LLC | $19 636 923 230 | 275 026 936 | 6,56% | Akcje |
| STATE STREET CORP | $12 861 252 155 | 180 129 582 | 4,30% | Akcje |
| FMR LLC | $9 705 920 859 | 135 937 268 | 3,24% | Akcje |
| Invesco Ltd. | $9 668 928 498 | 135 419 167 | 3,23% | Akcje |
| GEODE CAPITAL MANAGEMENT, LLC | $7 847 639 252 | 110 312 736 | 2,62% | Akcje |
| MORGAN STANLEY | $7 120 249 181 | 99 723 374 | 2,38% | Akcje |
| Capital World Investors | $6 236 148 079 | 87 336 163 | 2,08% | Akcje |
| VANGUARD PORTFOLIO MANAGEMENT LLC | $5 359 034 956 | 75 056 512 | 1,79% | Akcje |
| Capital Research Global Investors | $4 905 520 791 | 68 701 246 | 1,64% | Akcje |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $4 193 986 020 | 58 739 300 | 1,40% | Opcja kupna |
| NORGES BANK | $4 137 730 317 | 57 951 405 | 1,38% | Akcje |
| ALLIANCEBERNSTEIN L.P. | $3 370 008 271 | 35 049 488 | 1,13% | Akcje |
| JPMORGAN CHASE & CO | $3 270 113 543 | 44 322 490 | 1,09% | Akcje |
| UBS AM, a distinct business unit of UBS ASSET MANAGEMENT AMERICAS LLC | $3 255 458 334 | 33 858 121 | 1,09% | Akcje |
| NORTHERN TRUST CORP | $2 985 573 792 | 41 814 759 | 1,00% | Akcje |
| LOOMIS SAYLES & CO L P | $2 857 246 791 | 40 017 462 | 0,95% | Akcje |
| GOLDMAN SACHS GROUP INC | $2 749 397 069 | 38 506 961 | 0,92% | Akcje |
| BANK OF AMERICA CORP /DE/ | $2 674 454 612 | 37 457 348 | 0,89% | Akcje |
| CHARLES SCHWAB INVESTMENT MANAGEMENT INC | $2 407 890 102 | 33 723 951 | 0,80% | Akcje |
| CITADEL ADVISORS LLC | $2 254 162 260 | 31 570 900 | 0,75% | Opcja kupna |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $2 231 678 400 | 31 256 000 | 0,75% | Opcja sprzedaży |
| BANK OF MONTREAL /CAN/ | $2 204 691 654 | 30 878 034 | 0,74% | Akcje |
| CITADEL ADVISORS LLC | $2 150 096 760 | 30 113 400 | 0,72% | Opcja sprzedaży |
| JANE STREET GROUP, LLC | $2 040 919 020 | 28 584 300 | 0,68% | Opcja kupna |
| WELLINGTON MANAGEMENT GROUP LLP | $1 997 223 935 | 27 972 324 | 0,67% | Akcje |
| JENNISON ASSOCIATES LLC | $1 931 513 680 | 27 052 012 | 0,65% | Akcje |
| Bank of New York Mellon Corp | $1 906 482 368 | 26 701 433 | 0,64% | Akcje |
| Legal & General Group Plc | $1 886 525 730 | 26 421 929 | 0,63% | Akcje |
| Nuveen, LLC | $1 854 981 003 | 25 980 127 | 0,62% | Akcje |
| UBS Group AG | $1 835 500 650 | 25 707 292 | 0,61% | Akcje |
| JANE STREET GROUP, LLC | $1 824 876 900 | 25 558 500 | 0,61% | Opcja sprzedaży |
| Amundi | $1 821 639 267 | 25 513 155 | 0,61% | Akcje |
| VANGUARD FIDUCIARY TRUST CO | $1 727 451 957 | 24 194 005 | 0,58% | Akcje |
| AMERICAN CENTURY COMPANIES INC | $1 601 093 402 | 22 424 271 | 0,53% | Akcje |
| ROYAL BANK OF CANADA | $1 546 989 000 | 21 666 541 | 0,52% | Akcje |
| Mitsubishi UFJ Asset Management Co., Ltd. | $1 481 302 956 | 20 746 540 | 0,49% | Akcje |
| Fisher Asset Management, LLC | $1 457 653 353 | 20 415 312 | 0,49% | Akcje |
| DEUTSCHE BANK AG\ | $1 436 862 024 | 20 124 118 | 0,48% | Akcje |
| JANUS HENDERSON GROUP PLC | $1 431 141 205 | 14 884 336 | 0,48% | Akcje |
| WOLVERINE TRADING, LLC | $1 256 596 656 | 1 041 600 | 0,42% | Opcja sprzedaży |
| PeakShares LLC | $1 159 750 000 | 16 243 | 0,39% | Akcje |
| BAILLIE GIFFORD & CO | $1 154 810 962 | 16 173 823 | 0,39% | Akcje |
| WOLVERINE TRADING, LLC | $1 153 448 601 | 956 100 | 0,39% | Opcja kupna |
| Clearbridge Investments, LLC | $1 142 901 425 | 16 007 023 | 0,38% | Akcje |
| BARCLAYS PLC | $1 113 828 006 | 15 599 832 | 0,37% | Akcje |
| DIMENSIONAL FUND ADVISORS LP | $1 084 701 251 | 15 188 196 | 0,36% | Akcje |
| SRS Investment Management, LLC | $1 084 175 442 | 15 184 530 | 0,36% | Akcje |
| FIL Ltd | $1 042 206 879 | 14 596 735 | 0,35% | Akcje |
Aktywiści i właściciele 5%+ 10 akcji
Inwestorzy, którzy złożyli SEC Schedule 13D — posiadanie beneficjentów powyżej 5% z zamiarem wpływania na emitenta (udziały aktywistów, kampanie zarządu, M&A). Każdy wiersz pokazuje najnowszy znany stan pozycji tego zgłaszającego.
| Zgłaszający | Złożono | Udział | Status | Cel | Zgłoszenie |
|---|---|---|---|---|---|
| High River Limited Partnership, Hopper Investments LLC, Barberry Corp., Icahn Partners Master Fund LP, Icahn Partners Master Fund II LP, Icahn Partners Master Fund III LP, Icahn Offshore LP, Icahn Partners LP, Icahn Onshore LP, Icahn Capital LP, IPH GP LLC, Icahn Enterprises Holdings L.P., Icahn Enterprises G.P. Inc., Beckton Corp., Carl C. Icahn ×3 zgłoszenia | 22 października 2013 | · | Pierwotne zgłoszenie | · | SEC |
| 5 listopada 2012 | · | Pierwotne zgłoszenie | · | SEC | |
| TCV IV, L.P., TCV IV STRATEGIC PARTNERS, L.P., TECHNOLOGY CROSSOVER MANAGEMENT IV, L.L.C., TCV VI, L.P., TCV MEMBER FUND, L.P., TECHNOLOGY CROSSOVER MANAGEMENT VI, L.L.C., JAY C. HOAG, RICHARD H. KIMBALL, JOHN L. DREW, JON Q. REYNOLDS, JR., WILLIAM J.G. GRIFFITH IV, ROBERT W. TRUDEAU ×8 zgłoszenia | 4 lutego 2011 | · | Pierwotne zgłoszenie | · | SEC |
| TECHNOLOGY CROSSOVER VENTURES II, L.P., TCV II (Q), L.P., TCV II, V.O.F., TCV II STRATEGIC PARTNERS, L.P., TECHNOLOGY CROSSOVER VENTURES II, C.V., TECHNOLOGY CROSSOVER MANAGEMENT II, L.L.C., TCV IV, L.P., TCV IV STRATEGIC PARTNERS, L.P., TECHNOLOGY CROSSOVER MANAGEMENT IV, L.L.C., TCV VI, L.P., TCV MEMBER FUND, L.P., TECHNOLOGY CROSSOVER MANAGEMENT VI, L.L.C., JAY C. HOAG, RICHARD H. KIMBALL, JOHN L. DREW, JON Q. REYNOLDS, JR., WILLIAM J.G. GRIFFITH IV, ROBERT W. TRUDEAU ×3 zgłoszenia | 14 sierpnia 2008 | · | Pierwotne zgłoszenie | · | SEC |
| Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca | 17 lutego 2004 | · | Pierwotne zgłoszenie | Inwestycja pasywna | SEC |
| TCV IV, L.P. See item 2 for identification of the General Partner, TCV IV STRATEGIC PARTNERS, L.P. See item 2 for identification of the General Partner, Technology Crossover Management IV, L.L.C. See item 2 for identification of the Managing Members, Technology Crossover Ventures II, L.P. See item 2 for identification of the General Partner, TCV II (Q), L.P. See item 2 for identification of the General Partner, TCV II, V.O.F. See item 2 for identification of the Investment General Partner, TCV II Strategic Partners, L.P. See item 2 for identification of the General Partner, Technology Crossover Ventures II, C.V. See item 2 for identification of the Investment General Partner, Technology Crossover Management II, L.L.C. See item 2 for identification of the Managing Members, JAY C. HOAG, RICHARD H. KIMBALL | 30 stycznia 2004 | · | Pierwotne zgłoszenie | · | SEC |
| Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca | 10 listopada 2003 | · | Pierwotne zgłoszenie | Inwestycja pasywna | SEC |
| Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca, Niezgłoszona osoba raportująca | 14 lutego 2003 | · | Pierwotne zgłoszenie | Inwestycja pasywna | SEC |
| TCVF Management, L.L.C. See item 2 for identification of the Managing Members --------------------------------------------------------------------- (2), JAY C. HOAG --------------------------------------------------------------------- (2), RICHARD H. KIMBALL --------------------------------------------------------------------- (2) | 13 sierpnia 2002 | · | Pierwotne zgłoszenie | Inwestycja pasywna | SEC |
| TCV IV, L.P. See item 2 for identification of the General Partner --------------------------------------------------------------------- (2), TCV II (Q) L.P. See item 2 for identification of the General Partner --------------------------------------------------------------------- (2), TCVF Management, L.L.C. See item 2 for identification of the Mananging Members --------------------------------------------------------------------- (2), JAY C. HOAG --------------------------------------------------------------------- (2), RICHARD H. KIMBALL --------------------------------------------------------------------- (2) | 29 maja 2002 | · | Pierwotne zgłoszenie | Inwestycja pasywna | SEC |
Purpose is an automated classification of the filer's own stated purpose (SEC Item 4) — not investment advice. "—" means no clear purpose was stated or the text could not be classified.
Insiderzy spółki 44 insiderów · 21 dyrektorzy generalni · 20 dyrektorzy
| Insider | Rola | Ostatnia aktywność | Posiadane akcje | Kupna 12m | Sprzedaże 12m | Netto 12m |
|---|---|---|---|---|---|---|
| Theodore A Sarandos | Co-CEO | 3 sierpnia 2026 M | 178 954 | 0 | 7 | $-14 349 918 |
| David B Wells | CFO | 2 stycznia 2019 A | 0 | 0 | 0 | $0 |
| Barry Mccarthy | Chief Financial Officer | 1 grudnia 2010 A | 51 563 | 0 | 0 | $0 |
| Jeffrey William Karbowski | Chief Accounting Officer | 1 października 2026 A | 0 | 0 | 0 | $0 |
| Cletus R Willems | Chief Global Affairs Officer | 3 sierpnia 2026 M | 6 277 | 0 | 2 | $-521 132 |
| David A Hyman | Chief Legal Officer | 3 sierpnia 2026 M | 316 100 | 0 | 6 | $-38 053 545 |
| Dicus Marian Lee | Chief Marketing Officer | 3 stycznia 2023 A | · | 0 | 0 | $0 |
| Meabe Sergio Ezama | Chief Talent Officer | 3 stycznia 2023 A | · | 0 | 0 | $0 |
| Rachel Whetstone | Chief Communications Officer | 3 stycznia 2023 A | · | 0 | 0 | $0 |
| Kenneth A Barker | Chief Accounting Officer | 3 października 2022 A | · | 0 | 0 | $0 |
| John Bozoma Saint | Chief Marketing Officer | 1 marca 2022 A | · | 0 | 0 | $0 |
| Jessica Neal | Chief Talent Officer | 3 maja 2021 A | 0 | 0 | 0 | $0 |
| Kelly Bennett | Chief Marketing Officer | 1 marca 2019 A | 0 | 0 | 0 | $0 |
| Jonathan Friedland | Chief Communications Officer | 1 czerwca 2018 A | 0 | 0 | 0 | $0 |
| Neil D Hunt | Chief Product Officer | 1 czerwca 2017 A | 459 952 | 0 | 0 | $0 |
| Tawni Cranz | Chief Talent Officer | 3 kwietnia 2017 A | 0 | 0 | 0 | $0 |
| William J Holmes | Chief Business Dev Officer | 1 lipca 2013 A | 0 | 0 | 0 | $0 |
| Patricia J Mccord | Chief Talent Officer | 1 października 2012 A | 4 283 | 0 | 0 | $0 |
| Jessica T Becker | Interim Chief Mktng Officer | 2 lipca 2012 A | · | 0 | 0 | $0 |
| Andrew S Rendich | Chief Service and Ops Officer | 1 lipca 2011 A | 0 | 0 | 0 | $0 |
| Thomas R Dillon | Chief Operations Officer | 3 kwietnia 2006 A | 27 641 | 0 | 0 | $0 |
| Elinor Mertz | Dyrektor | 1 października 2026 A | · | 0 | 0 | $0 |
| Strive Masiyiwa | Dyrektor | 1 października 2026 A | 0 | 0 | 0 | $0 |
| Susan E Rice | Dyrektor | 1 października 2026 A | 0 | 0 | 0 | $0 |
| Mathias Dopfner | Dyrektor | 1 października 2026 A | 25 | 0 | 0 | $0 |
| Ann Mather | Dyrektor | 1 października 2026 A | 0 | 0 | 0 | $0 |
| Leslie J Kilgore | Dyrektor | 1 października 2026 A | 35 396 | 0 | 0 | $0 |
| Bradford L Smith | Dyrektor | 1 października 2026 A | 79 690 | 0 | 5 | $-5 614 593 |
| Richard N. Barton | Dyrektor | 1 października 2026 A | 2 460 | 0 | 4 | $-327 189 |
| Jay C Hoag | Dyrektor | 1 października 2026 A | 63 040 | 0 | 0 | $0 |
| Anne M Sweeney | Dyrektor | 1 lipca 2026 A | 0 | 0 | 0 | $0 |
| Reed Hastings | Dyrektor | 1 czerwca 2026 A | 3 940 | 0 | 47 | $-308 952 910 |
| Timothy M Haley | Dyrektor | 2 czerwca 2025 A | 0 | 0 | 0 | $0 |
| Rodolphe Belmer | Dyrektor | 3 października 2022 A | 0 | 0 | 0 | $0 |
| George A Battle | Dyrektor | 3 grudnia 2018 A | 46 050 | 0 | 0 | $0 |
| Charles H Giancarlo | Dyrektor | 1 czerwca 2012 A | 2 499 | 0 | 0 | $0 |
| Gregory S Stanger | Dyrektor | 1 lipca 2010 A | 0 | 0 | 0 | $0 |
| Michael N Schuh | Dyrektor | 3 maja 2010 A | 0 | 0 | 0 | $0 |
| Robert A Pisano | Dyrektor | 3 października 2005 A | 3 000 | 0 | 0 | $0 |
| Michael Ramsay | Dyrektor | 17 października 2003 M | 0 | 0 | 0 | $0 |
| William Griffith | Posiadacz 10% | 10 sierpnia 2010 S | 14 356 | 0 | 0 | $0 |
| Rick Kimball | Posiadacz 10% | 25 sierpnia 2008 G | 0 | 0 | 0 | $0 |
| Spencer Adam Neumann | · | 10 sierpnia 2026 S | 73 787 | 0 | 46 | $-16 946 353 |
| Gregory K Peters | · | 6 sierpnia 2026 S | 120 931 | 0 | 8 | $-17 697 970 |
Insiderzy z zgłoszeń SEC Form 3/4/5; netto = tylko otwarty rynek P/S
Posiadanie ETF-ów Posiadane przez 177 funduszy ETF
Waga odzwierciedla wyłącznie bezpośrednie udziały kapitałowe (N-PORT); fundusze oparte na dźwigni lub instrumentach pochodnych mogą posiadać dodatkowe ekspozycje na swapy, które nie są pokazane.
| Fundusz | Waga | Jednostki | Na dzień | Źródło |
|---|---|---|---|---|
| NFXL · Direxion Shares ETF Trust | 15,11% | 286 635 NS | 31 lipca 2026 | N-PORT |
| GGME · Invesco Exchange-Traded Fund Trust | 7,13% | 45 912 SH | 1 października 2026 | Dziennie |
| FCOM · FIDELITY COVINGTON TRUST | 4,32% | 1 042 475 NS | 31 lipca 2026 | N-PORT |
| RSPC · Invesco Exchange-Traded Fund Trust | 4,27% | 33 327 SH | 1 października 2026 | Dziennie |
| VOX · VANGUARD WORLD FUND | 4,22% | 3 538 124 SH | 19 sierpnia 2026 | Dziennie |
| FEPI · ETF Opportunities Trust | 4,21% | 379 552 NS | 31 lipca 2026 | N-PORT |
| IYC · iShares Trust | 4,09% | 621 573 SH | 11 września 2026 | Dziennie |
| IXP · iShares Trust | 4,03% | 245 778 SH | 11 września 2026 | Dziennie |
| QUSA · Tidal Trust III | 3,79% | 11 328 NS | 31 lipca 2026 | N-PORT |
| FDND · First Trust Exchange-Traded Fund IV | 3,76% | 5 120 NS | 31 lipca 2026 | N-PORT |
| NITE · Capitol Series Trust | 3,64% | 15 758 NS | 31 lipca 2026 | N-PORT |
| SPHQ · Invesco Exchange-Traded Fund Trust | 3,64% | 9 754 729 SH | 1 października 2026 | Dziennie |
| PNQI · Invesco Exchange-Traded Fund Trust | 3,54% | 270 623 SH | 1 października 2026 | Dziennie |
| TECB · iShares Trust | 3,29% | 213 446 SH | 11 września 2026 | Dziennie |
| FNGG · Direxion Shares ETF Trust | 3,20% | 54 002 NS | 31 lipca 2026 | N-PORT |
| LCLG · Advisors Series Trust | 2,67% | 40 114 NS | 31 lipca 2026 | N-PORT |
| PEXL · Pacer Funds Trust | 2,48% | 17 490 NS | 31 lipca 2026 | N-PORT |
| WEBL · Direxion Shares ETF Trust | 2,44% | 31 842 NS | 31 lipca 2026 | N-PORT |
| HAPI · Harbor ETF Trust | 2,26% | 154 369 NS | 31 lipca 2026 | N-PORT |
| FGSI · First Trust Exchange-Traded Fund IV | 2,03% | 586 NS | 31 lipca 2026 | N-PORT |
| QTOP · iShares Trust | 1,90% | 70 633 SH | 11 września 2026 | Dziennie |
| NULG · Nushares ETF Trust | 1,86% | 693 098 NS | 31 lipca 2026 | N-PORT |
| QUAL · iShares Trust | 1,84% | 11 254 784 SH | 11 września 2026 | Dziennie |
| RILA · Spinnaker ETF Series | 1,80% | 10 586 NS | 31 lipca 2026 | N-PORT |
| PALC · Pacer Funds Trust | 1,76% | 51 544 NS | 31 lipca 2026 | N-PORT |
| BIGY · Tidal Trust II | 1,64% | 12 411 NS | 31 lipca 2026 | N-PORT |
| WINN · Harbor ETF Trust | 1,62% | 255 352 NS | 31 lipca 2026 | N-PORT |
| HEQQ · J.P. Morgan Exchange-Traded Fund Tr… | 1,55% | 6 473 NS | 31 lipca 2026 | N-PORT |
| IGM · iShares Trust | 1,43% | 1 987 154 SH | 11 września 2026 | Dziennie |
| QYLD · Global X Funds | 1,41% | 1 587 968 NS | 31 lipca 2026 | N-PORT |
| QRMI · Global X Funds | 1,40% | 2 795 NS | 31 lipca 2026 | N-PORT |
| QYLG · Global X Funds | 1,39% | 30 787 NS | 31 lipca 2026 | N-PORT |
| PTNQ · Pacer Funds Trust | 1,38% | 230 240 NS | 31 lipca 2026 | N-PORT |
| QQWZ · Pacer Funds Trust | 1,38% | 9 786 NS | 31 lipca 2026 | N-PORT |
| QTR · Global X Funds | 1,34% | 1 421 NS | 31 lipca 2026 | N-PORT |
| QCLR · Global X Funds | 1,31% | 605 NS | 31 lipca 2026 | N-PORT |
| QSIX · Pacer Funds Trust | 1,27% | 3 251 NS | 31 lipca 2026 | N-PORT |
| QQQM · Invesco Exchange-Traded Fund Trust … | 1,21% | 19 143 382 SH | 1 października 2026 | Dziennie |
| QQQ · Invesco QQQ Trust, Series 1 | 1,21% | 86 974 420 SH | 1 października 2026 | Dziennie |
| ARKW · ARK ETF Trust | 1,19% | 266 351 NS | 31 lipca 2026 | N-PORT |
| WLTG · ETF Opportunities Trust | 1,18% | 12 694 NS | 31 lipca 2026 | N-PORT |
| AQLT · iShares Trust | 1,16% | 49 683 SH | 11 września 2026 | Dziennie |
| TEC · Harbor ETF Trust | 1,14% | 1 009 NS | 31 lipca 2026 | N-PORT |
| IWY · iShares Trust | 1,12% | 2 305 206 SH | 11 września 2026 | Dziennie |
| MGK · VANGUARD WORLD FUND | 1,12% | 5 218 895 SH | 19 sierpnia 2026 | Dziennie |
| SPGP · Invesco Exchange-Traded Fund Trust | 1,07% | 314 263 SH | 1 października 2026 | Dziennie |
| PEVC · Pacer Funds Trust | 1,02% | 342 NS | 31 lipca 2026 | N-PORT |
| ILCG · iShares Trust | 1,01% | 411 473 SH | 11 września 2026 | Dziennie |
| SEMI · Columbia ETF Trust I | 0,99% | 5 176 NS | 31 lipca 2026 | N-PORT |
| ALRG · ALLSPRING EXCHANGE-TRADED FUNDS TRU… | 0,98% | 1 149 NS | 31 lipca 2026 | N-PORT |
| IWF · iShares Trust | 0,97% | 15 769 276 SH | 11 września 2026 | Dziennie |
| QQQG · Pacer Funds Trust | 0,93% | 2 655 NS | 31 lipca 2026 | N-PORT |
| EQWL · Invesco Exchange-Traded Fund Trust | 0,93% | 370 445 SH | 1 października 2026 | Dziennie |
| IVW · iShares Trust | 0,90% | 8 980 812 SH | 11 września 2026 | Dziennie |
| VFQY · VANGUARD WELLINGTON FUND | 0,89% | 59 282 SH | 19 sierpnia 2026 | Dziennie |
| VONG · VANGUARD SCOTTSDALE FUNDS | 0,89% | 6 643 876 SH | 19 sierpnia 2026 | Dziennie |
| IUSG · iShares Trust | 0,85% | 3 707 327 SH | 11 września 2026 | Dziennie |
| VOOG · VANGUARD ADMIRAL FUNDS | 0,85% | 3 128 772 SH | 19 sierpnia 2026 | Dziennie |
| QQQE · Direxion Shares ETF Trust | 0,85% | 158 017 NS | 31 lipca 2026 | N-PORT |
| DYNF · BlackRock ETF Trust | 0,85% | 4 631 452 SH | 11 września 2026 | Dziennie |
| VUG · VANGUARD INDEX FUNDS | 0,84% | 44 610 196 SH | 19 sierpnia 2026 | Dziennie |
| MPLY · Strategy Shares | 0,73% | 1 610 NS | 31 lipca 2026 | N-PORT |
| GLBL · Pacer Funds Trust | 0,72% | 111 NS | 31 lipca 2026 | N-PORT |
| XLG · Invesco Exchange-Traded Fund Trust | 0,69% | 1 151 316 SH | 1 października 2026 | Dziennie |
| OEF · iShares Trust | 0,67% | 1 780 199 SH | 11 września 2026 | Dziennie |
| AGRW · ALLSPRING EXCHANGE-TRADED FUNDS TRU… | 0,67% | 10 528 NS | 31 lipca 2026 | N-PORT |
| NULC · Nushares ETF Trust | 0,65% | 6 361 NS | 31 lipca 2026 | N-PORT |
| IIGD · Invesco Exchange-Traded Self-Indexe… | 0,64% | 162 000 | 1 października 2026 | Dziennie |
| HFGO · Hartford Funds Exchange-Traded Trust | 0,64% | 17 946 NS | 31 lipca 2026 | N-PORT |
| ACIO · ETF Series Solutions | 0,63% | 208 101 NS | 31 lipca 2026 | N-PORT |
| ADME · ETF Series Solutions | 0,63% | 25 914 NS | 31 lipca 2026 | N-PORT |
| OMFL · Invesco Exchange-Traded Self-Indexe… | 0,61% | 411 144 SH | 1 października 2026 | Dziennie |
| FQAL · FIDELITY COVINGTON TRUST | 0,60% | 118 782 NS | 31 lipca 2026 | N-PORT |
| DUHP · Dimensional ETF Trust | 0,60% | 1 025 735 NS | 31 lipca 2026 | N-PORT |
| TOPC · iShares Trust | 0,59% | 2 563 SH | 11 września 2026 | Dziennie |
| USCL · iShares Trust | 0,59% | 220 387 SH | 11 września 2026 | Dziennie |
| RPG · Invesco Exchange-Traded Fund Trust | 0,57% | 158 689 SH | 1 października 2026 | Dziennie |
| MGC · VANGUARD WORLD FUND | 0,57% | 841 756 SH | 19 sierpnia 2026 | Dziennie |
| IWL · iShares Trust | 0,56% | 162 859 SH | 11 września 2026 | Dziennie |
| FHEQ · Fidelity Greenwood Street Trust | 0,56% | 72 370 NS | 31 lipca 2026 | N-PORT |
| UPSD · ETF Series Solutions | 0,56% | 9 099 NS | 31 lipca 2026 | N-PORT |
| FFLG · FIDELITY COVINGTON TRUST | 0,56% | 45 786 NS | 31 lipca 2026 | N-PORT |
| OEI · Listed Funds Trust | 0,55% | 3 580 NS | 31 lipca 2026 | N-PORT |
| FBCG · FIDELITY COVINGTON TRUST | 0,55% | 531 326 NS | 31 lipca 2026 | N-PORT |
| XVV · iShares Trust | 0,55% | 48 452 SH | 11 września 2026 | Dziennie |
| QVML · Invesco Exchange-Traded Fund Trust … | 0,55% | 130 122 SH | 1 października 2026 | Dziennie |
| GARP · iShares Trust | 0,54% | 216 490 SH | 11 września 2026 | Dziennie |
| TRFM · ETF Series Solutions | 0,53% | 18 360 NS | 31 lipca 2026 | N-PORT |
| EGUS · iShares Trust | 0,52% | 1 902 SH | 11 września 2026 | Dziennie |
| ESGV · VANGUARD WORLD FUND | 0,51% | 948 568 SH | 19 sierpnia 2026 | Dziennie |
| FYEE · Fidelity Greenwood Street Trust | 0,50% | 15 273 NS | 31 lipca 2026 | N-PORT |
| BSCQ · Invesco Exchange-Traded Self-Indexe… | 0,50% | 15 913 000 | 30 września 2026 | Dziennie |
| IVV · iShares Trust | 0,49% | 53 074 428 SH | 11 września 2026 | Dziennie |
| FBUF · Fidelity Greenwood Street Trust | 0,49% | 1 621 NS | 31 lipca 2026 | N-PORT |
| ILCB · iShares Trust | 0,48% | 81 987 SH | 11 września 2026 | Dziennie |
| XRMI · Global X Funds | 0,48% | 3 316 NS | 31 lipca 2026 | N-PORT |
| CHRI · Global X Funds | 0,47% | 527 NS | 31 lipca 2026 | N-PORT |
| CATH · Global X Funds | 0,47% | 85 525 NS | 31 lipca 2026 | N-PORT |
| VOO · VANGUARD INDEX FUNDS | 0,47% | 109 375 220 SH | 19 sierpnia 2026 | Dziennie |
| VV · VANGUARD INDEX FUNDS | 0,47% | 4 917 755 SH | 19 sierpnia 2026 | Dziennie |
| BBUS · J.P. Morgan Exchange-Traded Fund Tr… | 0,47% | 582 457 NS | 31 lipca 2026 | N-PORT |
| PTLC · Pacer Funds Trust | 0,47% | 212 946 NS | 31 lipca 2026 | N-PORT |
| XYLD · Global X Funds | 0,47% | 211 576 NS | 31 lipca 2026 | N-PORT |
| XYLG · Global X Funds | 0,47% | 4 176 NS | 31 lipca 2026 | N-PORT |
| VOTE · TCW ETF Trust | 0,47% | 71 437 NS | 31 lipca 2026 | N-PORT |
| BKLC · BNY Mellon ETF Trust | 0,47% | 356 119 NS | 31 lipca 2026 | N-PORT |
| XTR · Global X Funds | 0,47% | 313 NS | 31 lipca 2026 | N-PORT |
| XCLR · Global X Funds | 0,46% | 231 NS | 31 lipca 2026 | N-PORT |
| SUSA · iShares Trust | 0,46% | 245 054 SH | 11 września 2026 | Dziennie |
| VOXP · Advisors Series Trust | 0,46% | 372 NS | 31 lipca 2026 | N-PORT |
| TOV · EA Series Trust | 0,46% | 16 776 NS | 31 lipca 2026 | N-PORT |
| DFSU · Dimensional ETF Trust | 0,46% | 145 060 NS | 31 lipca 2026 | N-PORT |
| IYY · iShares Trust | 0,46% | 180 619 SH | 11 września 2026 | Dziennie |
| IWB · iShares Trust | 0,46% | 2 902 886 SH | 11 września 2026 | Dziennie |
| BSCS · Invesco Exchange-Traded Self-Indexe… | 0,45% | 15 391 000 | 1 października 2026 | Dziennie |
| PBP · Invesco Exchange-Traded Fund Trust | 0,45% | 24 773 SH | 1 października 2026 | Dziennie |
| COWG · Pacer Funds Trust | 0,44% | 135 538 NS | 31 lipca 2026 | N-PORT |
| PBUS · Invesco Exchange-Traded Fund Trust … | 0,44% | 718 506 SH | 1 października 2026 | Dziennie |
| IWV · iShares Trust | 0,44% | 1 155 500 SH | 11 września 2026 | Dziennie |
| ITOT · iShares Trust | 0,44% | 5 482 112 SH | 11 września 2026 | Dziennie |
| SPUU · Direxion Shares ETF Trust | 0,43% | 15 886 NS | 31 lipca 2026 | N-PORT |
| VONE · VANGUARD SCOTTSDALE FUNDS | 0,43% | 691 880 SH | 19 sierpnia 2026 | Dziennie |
| QDPL · Pacer Funds Trust | 0,43% | 101 450 NS | 31 lipca 2026 | N-PORT |
| NUGO · Nushares ETF Trust | 0,42% | 143 449 NS | 31 lipca 2026 | N-PORT |
| DFUS · Dimensional ETF Trust | 0,42% | 1 212 661 NS | 31 lipca 2026 | N-PORT |
| QLC · FlexShares Trust | 0,42% | 58 688 NS | 31 lipca 2026 | N-PORT |
| VTI · VANGUARD INDEX FUNDS | 0,41% | 133 701 685 SH | 19 sierpnia 2026 | Dziennie |
| VTHR · VANGUARD SCOTTSDALE FUNDS | 0,41% | 353 280 SH | 19 sierpnia 2026 | Dziennie |
| ESGU · iShares Trust | 0,40% | 932 675 SH | 11 września 2026 | Dziennie |
| TOK · iShares Trust | 0,37% | 11 670 SH | 11 września 2026 | Dziennie |
| HCMT · Direxion Shares ETF Trust | 0,37% | 29 301 NS | 31 lipca 2026 | N-PORT |
| QIDX · Spinnaker ETF Series | 0,37% | 1 982 NS | 31 lipca 2026 | N-PORT |
| PHDG · Invesco Actively Managed Exchange-T… | 0,37% | 3 280 SH | 1 października 2026 | Dziennie |
| LRGF · iShares Trust | 0,37% | 178 695 SH | 11 września 2026 | Dziennie |
| URTH · iShares, Inc. | 0,35% | 377 433 SH | 11 września 2026 | Dziennie |
| SPXL · Direxion Shares ETF Trust | 0,35% | 329 191 NS | 31 lipca 2026 | N-PORT |
| DFAU · Dimensional ETF Trust | 0,35% | 599 824 NS | 31 lipca 2026 | N-PORT |
| CRBN · iShares Trust | 0,33% | 49 945 SH | 11 września 2026 | Dziennie |
| TILT · FlexShares Trust | 0,31% | 94 010 NS | 31 lipca 2026 | N-PORT |
| ACWI · iShares Trust | 0,31% | 1 326 739 SH | 11 września 2026 | Dziennie |
| PFIG · Invesco Exchange-Traded Fund Trust … | 0,30% | 385 000 | 1 października 2026 | Dziennie |
| DCOR · Dimensional ETF Trust | 0,29% | 136 941 NS | 31 lipca 2026 | N-PORT |
| FCPI · FIDELITY COVINGTON TRUST | 0,28% | 10 728 NS | 31 lipca 2026 | N-PORT |
| IUS · Invesco Exchange-Traded Self-Indexe… | 0,28% | 38 946 SH | 1 października 2026 | Dziennie |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0,26% | 3 512 331 SH | 19 sierpnia 2026 | Dziennie |
| HELO · J.P. Morgan Exchange-Traded Fund Tr… | 0,26% | 166 948 NS | 31 lipca 2026 | N-PORT |
| HQGO · Lattice Strategies Trust | 0,26% | 1 766 NS | 31 lipca 2026 | N-PORT |
| DFVX · Dimensional ETF Trust | 0,26% | 18 736 NS | 31 lipca 2026 | N-PORT |
| INFO · Harbor ETF Trust | 0,24% | 28 560 NS | 31 lipca 2026 | N-PORT |
| DFAC · Dimensional ETF Trust | 0,23% | 1 541 899 NS | 31 lipca 2026 | N-PORT |
| RWL · Invesco Exchange-Traded Fund Trust … | 0,23% | 319 786 SH | 1 października 2026 | Dziennie |
| PRF · Invesco Exchange-Traded Fund Trust | 0,22% | 314 779 SH | 1 października 2026 | Dziennie |
| JOYT · J.P. Morgan Exchange-Traded Fund Tr… | 0,22% | 3 013 NS | 31 lipca 2026 | N-PORT |
| LGDX · Tidal Trust III | 0,20% | 3 981 NS | 31 lipca 2026 | N-PORT |
| DXUV · Dimensional ETF Trust | 0,20% | 14 996 NS | 31 lipca 2026 | N-PORT |
| EUSA · iShares, Inc. | 0,19% | 48 643 SH | 11 września 2026 | Dziennie |
| BSCT · Invesco Exchange-Traded Self-Indexe… | 0,19% | 5 381 000 | 1 października 2026 | Dziennie |
| RSP · Invesco Exchange-Traded Fund Trust | 0,19% | 2 572 851 SH | 1 października 2026 | Dziennie |
| USMV · iShares Trust | 0,18% | 566 367 SH | 11 września 2026 | Dziennie |
| GLOF · iShares Trust | 0,17% | 4 451 SH | 11 września 2026 | Dziennie |
| SIZE · iShares Trust | 0,15% | 8 245 SH | 11 września 2026 | Dziennie |
| HDUS · Lattice Strategies Trust | 0,13% | 3 738 NS | 31 lipca 2026 | N-PORT |
| JQUA · J.P. Morgan Exchange-Traded Fund Tr… | 0,09% | 106 435 NS | 31 lipca 2026 | N-PORT |
| ROUS · Lattice Strategies Trust | 0,08% | 7 413 NS | 31 lipca 2026 | N-PORT |
| FEUS · FlexShares Trust | 0,06% | 990 NS | 31 lipca 2026 | N-PORT |
| PABU · iShares Trust | 0,06% | 19 676 SH | 11 września 2026 | Dziennie |
| EQAL · Invesco Exchange-Traded Fund Trust … | 0,06% | 6 552 SH | 1 października 2026 | Dziennie |
| ACWV · iShares, Inc. | 0,06% | 24 435 SH | 11 września 2026 | Dziennie |
| NEAR · iShares U.S. ETF Trust | 0,04% | 2 277 000 SH | 11 września 2026 | Dziennie |
| GTO · Invesco Actively Managed Exchange-T… | 0,00% | 1 000 | 30 września 2026 | Dziennie |
| BSV · VANGUARD BOND INDEX FUNDS | · | · | 15 lipca 2026 | Dziennie |
| BND · VANGUARD BOND INDEX FUNDS | · | · | 15 lipca 2026 | Dziennie |
| VCSH · VANGUARD SCOTTSDALE FUNDS | · | · | 15 lipca 2026 | Dziennie |
| VTC · VANGUARD SCOTTSDALE FUNDS | · | · | 30 lipca 2026 | Dziennie |
| BNDW · VANGUARD SCOTTSDALE FUNDS | · | · | 30 lipca 2026 | Dziennie |
| BNDX · VANGUARD CHARLOTTE FUNDS | · | · | 15 lipca 2026 | Dziennie |
| VCEB · VANGUARD WORLD FUND | · | · | 30 lipca 2026 | Dziennie |
NFLX Konsensus analityków Bycze i niedźwiedzie opinie analityków, 12-miesięczny cel cenowy, potencjał wzrostu
12-miesięczny cel cenowy
45 analityków · 2026-09-20Średnia cel $93.37 +39,2%
Porównanie z porównywalnymi firmami (podbranża GICS) Kluczowe metryki w porównaniu do konkurentów z sektora
Podstawa R/R, ceny według zamknięcia z ostatniego końca roku obrotowego każdej spółki.
| Ticker | Kapitalizacja Rynkowa | P/E | Przychody r/r | Marża Netto | ROE | Marża brutto |
|---|---|---|---|---|---|---|
| NFLX | $395.87B | 37.1 | 15.8% | 24.3% | 42.6% | · |
| DIS | $215.59B | 16.6 | 3.4% | 13.1% | 11.8% | · |
| WBD | $71.47B | 99.4 | -5.1% | 1.9% | 2.1% | · |
| LYV | $33.55B | -593.8 | 8.8% | 2.0% | 223.3% | · |
| TKO | · | 92.5 | -3.0% | 4.1% | 5.0% | · |
| FWONA | · | 67.7 | 22.7% | 12.4% | 7.5% | · |
| ROKU | $16.04B | 183.9 | 15.2% | 1.9% | 3.4% | 43.8% |
| WMG | · | · | 4.4% | 5.4% | 62.7% | · |
| MSGS | · | 1255.8 | 11.0% | 0.67% | -2.9% | · |
| SPHR | · | 128.5 | 79.0% | 2.7% | 1.5% | · |
| CNK | · | 22.3 | 2.1% | 4.4% | · | · |
Najnowsze wiadomości Najnowsze nagłówki wspominające o tej firmie
NFLX Panel Analityków AI — Widoki Bycze i Niedźwiedzie Debata 2026Q2: Claude, Grok, Gemini, ChatGPT na temat perspektyw akcji
Netflix stoi w obliczu walki między swoją dominującą rentownością a wyceną, która nie pozostawia miejsca na błędy. Grok i Gemini podkreślają 41% zwrotu z kapitału własnego firmy jako dowód trwałego silnika zysków, podczas gdy Claude ostrzega, że wysokie zadłużenie i zmiany przywództwa stwarzają znaczące ryzyko spadku. Panel pozostaje podzielony co do tego, czy obecna premia cenowa jest uzasadniona, ostatecznie dochodząc do ostrożnego utrzymania pozycji, gdy firma przechodzi przez krytyczny etap przejścia na przychody z reklam.
Runda 1 — Pierwsze opinie
Widzę Netflixa jako króla rentowności streamingu, wykorzystującego bariery w postaci treści i potencjał reklamowy do napędzania trwałej siły zarobkowej do Q2 2026. Jego ROE na poziomie 41,86% pokazuje, że firma znacznie lepiej zamienia kapitał własny akcjonariuszy w zyski niż konkurenci, tacy jak Disney z 11%, finansując więcej hitów bez rozwodnienia. Marże brutto na poziomie 48% pozostają bardzo solidne, udowadniając, że siła cenowa utrzymuje się nawet przy stabilizacji kosztów. Przekroczenie przychodów w Q1 w wiadomościach z 16 kwietnia sygnalizuje dynamikę, z opłatami za anulowanie jako dodatkowym bonusem.
Moim zdaniem wyceny Netflixa, które są astronomiczne, zakładają perfekcję, która może zostać zniszczona przez nasycenie subskrybentów i rywalizację do Q2 2026. Wskaźnik P/E na poziomie 41 przewyższa 14 Disneya, nie pozostawiając miejsca na niedotrzymanie wyników w zatłoczonym rynku. Kapitalizacja rynkowa spadła o 16% z 512 miliardów w Q3 2025 do obecnych 428 miliardów, odzwierciedlając obawy o wzrost. Rezygnacja Reeda Hastingsa ze stanowiska prezesa 16 kwietnia dodaje ryzyko przywództwa w kluczowym momencie zwrotu w kierunku reklamy.
Netflix udowodnił, że potrafi zwiększać przychody o dwucyfrowy procent, jednocześnie zwiększając marże — podstawowy model streamingu działa. Marża brutto wynosi 48%, co jest poziomem fortecy dla firmy medialnej, a marża netto na poziomie 24% pokazuje, że siła cenowa jest realna. Wskaźnik ROE na poziomie 41,86% mówi, że zarząd wydobywa rzeczywiste zwroty z kapitału akcjonariuszy, a nie tylko inżynierię finansową. Przy 41-krotności zysków z ostatnich dwunastu miesięcy, tak, mnożnik jest wysoki, ale jeśli wzrost liczby subskrybentów i penetracja reklamowa utrzymają się, generowanie gotówki uzasadnia premię w stosunku do 14-krotności Disneya. Rezygnacja Reeda Hastingsa to ryzyko ciągłości przywództwa, a nie wyrok śmierci.
Netflix notowany jest po 41-krotności zysków, podczas gdy Disney po 14-krotności — ta różnica zmniejszy się tylko wtedy, gdy Netflix będzie przez lata szybciej zwiększał zyski niż Disney, a ja nie widzę na to żadnych dowodów. Akcje spadły z 1331 USD do 1245 USD w ciągu trzech tygodni, a kapitalizacja rynkowa spadła o 30 miliardów dolarów w zeszłym kwartale. Bardziej niepokojące: wskaźnik długu do kapitału własnego wynosi 55,7%, co oznacza, że Netflix jest maksymalnie zadłużony, aby finansować wykupy akcji i treści. Jeśli wzrost liczby subskrybentów spowolni lub stawki reklamowe spadną, to zadłużenie stanie się pułapką. Opłata za anulowanie umowy z Warner Bros. była jednorazowym czynnikiem wspierającym, maskującym podstawowe pytania dotyczące dynamiki.
Netflix z powodzeniem przechodzi od gracza "wzrost za wszelką cenę" do wysoce wydajnej maszyny do generowania zysków. Firma generuje obecnie ROE na poziomie 41,86%, co świadczy o wyjątkowej zdolności do generowania znaczących zwrotów z kapitału akcjonariuszy, nawet w miarę dojrzewania rynku streamingu. Ta wydajność jest wspierana przez solidną marżę zysku netto na poziomie 24,05%, co pokazuje, że firma przeszła przez erę intensywnego spalania gotówki na produkcję oryginalnych treści. Utrzymując bieżący wskaźnik na poziomie 1,33, zapewnia wystarczającą ilość płynnych aktywów na pokrycie krótkoterminowych zobowiązań, jednocześnie inwestując w następną generację globalnych hitów.
Wycena pozostaje oderwana od spowalniającej trajektorii wzrostu firmy. Inwestorzy płacą obecnie 41,07-krotność zysków z ostatnich dwunastu miesięcy za akcje, których EPS odnotował znaczący spadek w porównaniu z poprzednimi kwartałami. Ten wskaźnik P/E jest wysoki, biorąc pod uwagę, że firma stoi w obliczu znaczącej transformacji przywództwa w związku z rezygnacją Reeda Hastingsa ze stanowiska prezesa. Ponadto, przy wskaźniku ceny do sprzedaży na poziomie 9,88, rynek wycenia perfekcję w czasie, gdy sektor streamingu staje się coraz bardziej zatłoczony, a kapitalizacja rynkowa firmy spadała w ciągu ostatnich trzech kwartałów.
Myślę, że najsilniejszy argument byka jest taki, że Netflix nadal generuje wysoką rentowność kapitału własnego i zdrowe marże brutto, co wspiera trwałą historię zysków, nawet gdy finansuje bieżące inwestycje w treści. ROE 41,86% — ten poziom sygnalizuje, że Netflix zamienia dużą część kapitału własnego w zysk, co oznacza silną siłę cenową i efektywność kapitałową. Marża brutto 48,09% — ta marża wspiera trwałą rentowność i większą dźwignię operacyjną w miarę wzrostu skali. Dług/Kapitał własny 55,73% — ten poziom zadłużenia sugeruje, że Netflix może finansować bieżące ekspansje bez natychmiastowego ryzyka płynności, chociaż utrzymuje pewne ryzyko bilansowe, jeśli przepływy pieniężne osłabną.
Myślę, że najsilniejszy argument niedźwiedzi jest taki, że akcje pozostają wysoko wycenione w porównaniu z konkurentami i stoją w obliczu ryzyka transformacji przywództwa, które może ograniczyć realizację, jeśli wzrost spowolni. P/E TTM 41,07 — ten wysoki mnożnik sugeruje, że akcje są wycenione na ponadprzeciętny wzrost; jakiekolwiek krótkoterminowe spowolnienie może spowodować kompresję mnożnika. P/S TTM 9,88 — ten mnożnik wskazuje, że inwestorzy płacą premię za przychody; spowolnienie wzrostu wywarłoby presję na wycenę. EPS TTM 2,39 — umiarkowane zyski z ostatnich dwunastu miesięcy w stosunku do wysokiego mnożnika zwiększają ryzyko, jeśli marże lub wzrost liczby subskrybentów ulegną pogorszeniu.
Runda 2 — Odpowiedzi i Niewypowiedziane
Runda 2 — Odpowiedzi i Niewypowiedziane
Claude, twoje niedźwiedzie spojrzenie pomija, jak 55,7% wskaźnika długu do kapitału własnego Netflixa nie jest pułapką, ale sprytnym akceleratorem dominacji w zakresie treści. Ten wskaźnik oznacza, że na każdego dolara kapitału własnego, dług dodaje nieco ponad pół dolara — zarządzalne, biorąc pod uwagę, że bieżący wskaźnik 1,33 komfortowo pokrywa krótkoterminowe zobowiązania. Przy 24% marżach netto generujących gotówkę, to zadłużenie napędza wykupy akcji i hity bez ryzyka rozwodnienia, w przeciwieństwie do bardziej ryzykownych konkurentów, takich jak Warner Bros.
Muszę odnieść się do interpretacji Groka dotyczącej spadku kapitalizacji rynkowej. Grok mówi, że Netflix spadł o 16% z 512 miliardów do 428 miliardów i przedstawia to jako obawy o wzrost, ale te obliczenia nie pasują do obserwowanych przez nas ruchów cen akcji. Wykres tygodniowy pokazuje, że NFLX w ciągu ostatniego miesiąca notowany był między 1245 USD a 1331 USD — to wahanie o 6,5%, a nie 16%. Ruchy kapitalizacji rynkowej to szum, gdy patrzymy na firmę wartą 428 miliardów dolarów z normalną zmiennością tygodniową. Ważne jest to, czy przekroczenie przychodów w Q1, o którym wspomniał Grok, utrzyma się w prognozach, i czy opłata za anulowanie umowy z Warner Bros. — którą oznaczyłem jako jednorazową — zostanie powtórzona. Jeśli nie, ryzyko kompresji mnożnika, które opisałem, szybko stanie się realne.
Claude, twój punkt dotyczący wskaźnika długu do kapitału własnego jako pułapki pomija rzeczywistość obecnej struktury kapitałowej Netflixa. Powołałeś się na wskaźnik długu do kapitału własnego na poziomie 55,7% jako dowód niebezpiecznego zadłużenia, ale ten poziom jest faktycznie bardzo zarządzalny dla firmy generującej tak spójny przepływ pieniężny. Ten wskaźnik mówi nam, że na każdego dolara kapitału własnego firma posiada około 56 centów długu, co jest konserwatywnym odciskiem dla dojrzałego giganta medialnego. Wierzę, że Netflix z powodzeniem przeszedł przez fazę wzrostu finansowanego długiem, co sprawia, że twoje obawy dotyczące ich bilansu są nieco przesadzone.
Claude, twoje obawy dotyczące zadłużenia są uzasadnione, ale kluczowym sygnałem w moich oczach jest siła rentowności Netflixa. ROE na poziomie 41,86% sygnalizuje, że Netflix zamienia kapitał własny w zyski w tempie znacznie wyższym niż konkurenci. Przekłada się to na siłę cenową i efektywność kapitałową napędzającą silnik gotówkowy. Jednak wysoki mnożnik pozostaje ryzykowny, jeśli wzrost spowolni lub przepływy pieniężne osłabną, utrzymując zadłużenie w centrum uwagi.
Runda 3 — Ostateczne Odpowiedzi
Runda 3 — Ostateczne Odpowiedzi
Claude, rozszerzając twoją analizę wykresu tygodniowego, dywergencja wolumenu sygnalizuje dystrybucję instytucjonalną, która jest niedźwiedzia do Q2 2026. Wybicie po wynikach z 25 kwietnia nastąpiło przy wolumenie 35 milionów akcji, przyciągając zakupy dużych pieniędzy. Ostatnie spadki, takie jak spadek z 11 lipca, odbywają się przy połowie tego wolumenu — cieńsze wsparcie oznacza dominację sprzedających, co grozi dalszą kompresją nałożoną na rozciągnięcie wyceny, które wszyscy zaznaczyliśmy.
Chcę odnieść się do czegoś, co Gemini i Grok pominęli: twierdzenia, że 55,7% wskaźnika długu do kapitału własnego Netflixa jest "zarządzalne" lub "konserwatywne" dla firmy medialnej. To nie jest dokładne. Disney ma wskaźnik D/E wynoszący około 1,2x — prawie dwukrotnie więcej niż Netflix — a Disney jest konglomeratem kapitałochłonnym z parkami rozrywki i telewizją liniową. 55,7% D/E Netflixa jest faktycznie na wysokim poziomie dla streamingu. Co ważniejsze: marża netto Netflixa na poziomie 24% jest realna, ale nie rośnie. Jeśli wzrost liczby subskrybentów ustabilizuje się, a stawki reklamowe napotkają presję — oba są realnymi ryzykami na nasyconym rynku — to zadłużenie stanie się kamieniem młyńskim, a nie atutem. Grok przedstawia wykupy akcji jako "bez ryzyka rozwodnienia", ale wykupy finansowane długiem w środowisku spowalniającego wzrostu to dokładnie sposób na zniszczenie wartości dla akcjonariuszy. Nie zmieniam mojej rekomendacji "utrzymuj", ale jestem bardziej zaniepokojony matematyką bilansową niż reszta panelu.
Claude, muszę zakwestionować twoje odrzucenie transformacji przywództwa jako zwykłego ryzyka ciągłości. Rezygnacja Reeda Hastingsa ze stanowiska prezesa 16 kwietnia to ogromna zmiana strukturalna dla firmy, która polegała na jego specyficznej wizji przez prawie trzy dekady. To nie jest tylko zmiana zarządu; to odejście głównego architekta modelu streamingu w czasie, gdy firma musi przestawić się na modele oparte na reklamach. Jeśli nowe kierownictwo nie poradzi sobie z tą zmianą tożsamości, obecny wskaźnik P/E na poziomie 41,07, który reprezentuje premię, jaką inwestorzy płacą za przyszłe zyski, prawdopodobnie się załamie.
Myślę, że powinniśmy poszerzyć perspektywę na dynamikę konkurencji, a nie tylko na fundamenty. Claude, twoje spojrzenie na zadłużenie jest ważne, ale ciągła ekspansja warstwy reklamowej Disneya i strategia pakietowania z Hulu tworzą realną presję cenową i popytową na NFLX. Jeśli Disney przyspieszy międzynarodowe wdrożenie lub zwiększy ekspozycję na sport na żywo, NFLX będzie napotykać większą konkurencję o te same dolary z reklam i subskrybentów premium. Gemini, Grok, skupienie rynku na rentowności będzie zależeć mniej od samych marż, a bardziej od tego, jak NFLX utrzyma udział w popycie w obliczu tych planów.
Prognozy cenowe
| Model | Cel 3M | Cel 6M | Uzasadnienie |
|---|---|---|---|
| Grok | $1280.00 | $1350.00 | Myślę, że Netflix będzie rósł do Q2 2026, jeśli dodanie subskrybentów z warstwy reklamowej potwierdzi bariery rentowności wobec konkurentów. Kluczowym katalizatorem są wyniki za Q2, które pojawią się 23 lipca 2026 r. lub około tej daty, gdzie prognozy dotyczące wzrostu przychodów z reklam o 15%+ mogą spowodować ekspansję mnożnika. Wielkim ryzykiem jest niedotrzymanie wzrostu liczby subskrybentów poniżej 5 milionów netto, co ponownie wzbudzi obawy o nasycenie i spowoduje kompresję wskaźnika P/E na poziomie 41 — który już wycenia bezbłędną realizację bez marginesu dla rywali takich jak Disney, aby odebrać udział. Przy prognozowanym P/E na poziomie 38, wynikającym z mojej 6-miesięcznej prognozy 1350 z dzisiejszego zamknięcia na poziomie 1245, zakłada to stałe dostarczanie EPS bez wstrząsów przywództwa po odejściu Hastingsa. |
| Claude | $1080.00 | $1020.00 | Netflix jest uwięziony między rentownością fortecy a wyceną, która nie pozostawia miejsca na błędy na nasyconym rynku. Moja teza: mnożnik P/E na poziomie 41 ulegnie kompresji, jeśli wzrost liczby subskrybentów zatrzyma się lub stawki reklamowe osłabną, oba są realnymi ryzykami do Q3 2026. Konkretnym katalizatorem są prognozy wyników za Q2 z 18 lipca — jeśli zarząd zasygnalizuje wolniejszy wzrost liczby nowych subskrybentów lub stagnację ARPU, rynek szybko dokona korekty w dół. Ryzyko, które to przełamuje: adopcja warstwy reklamowej przyspieszy powyżej konsensusu, uzasadniając mnożnik. W kwestii wyceny: 41-krotność zysków oznacza, że rynek wycenia 15%+ rocznego wzrostu zysków przez lata; marża netto Netflixa na poziomie 24% jest solidna, ale płaska, nie rośnie. Rezygnacja Hastingsa zwiększa ryzyko realizacji. Prognozuję 3-miesięczne osłabienie do 1080 USD, gdy powrócą obawy o zadłużenie, a następnie stabilizację w okolicach 1020 USD do października, gdy rynek dokona korekty do 35-krotności zysków — nadal premii, ale bardziej uczciwej. |
| Gemini | $1180.00 | $1250.00 | Moja teza jest taka, że Netflix będzie notowany w bok, absorbując transformację przywództwa, a dopiero potem wzrośnie, jeśli przychody z warstwy reklamowej zrekompensują nasycenie subskrybentów. Głównym katalizatorem będzie raport o wynikach za Q3 2026, który będzie pierwszym prawdziwym testem zdolności zarządu do skalowania rentowności warstwy reklamowej bez Reeda Hastingsa. Głównym ryzykiem jest znaczący spadek marży netto na poziomie 24,05%, co sygnalizowałoby, że konkurencja w końcu eroduje ich siłę cenową. Inwestorzy płacą obecnie 41,07-krotność zysków z ostatnich dwunastu miesięcy, co oznacza, że rynek stawia na trwały, wysokomarżowy wzrost, który nie pozostawia miejsca na błędy w nadchodzących kwartałach. |
| Chatgpt | $1150.00 | $1250.00 | Myślę, że NFLX może wzrosnąć w nadchodzących miesiącach, ponieważ rentowność pozostaje trwała. Katalizator: publikacja wyników za Q2 2026 wzmocni przekonanie, że dyscyplina wzrostu i marż jest nienaruszona. Ryzyko: niedotrzymanie wyników za Q2 lub słabe prognozy mogą spowodować kompresję mnożnika. Ten 41-krotny wskaźnik P/E z ostatnich dwunastu miesięcy oznacza, że Netflix jest wyceniony na ponadprzeciętne przyszłe zyski, więc jakiekolwiek krótkoterminowe niedotrzymanie może spowodować kompresję mnożnika. |
Sygnały transakcyjne Ostatnie sygnały kupna/sprzedaży z ceną wejścia i wskaźnikiem ryzyka/zysku
Obecnie brak otwartego sygnału — żadna karta nie jest wypełniona, i to jest uczciwe.
Moje wskaźniki Twoja osobista lista obserwowanych — wybrane wiersze z Pełnych Fundamentów
Wybierz wskaźniki, które są dla Ciebie ważne — kliknij + obok dowolnego wiersza w sekcji Pełne dane fundamentalne powyżej.
Twój wybór został zapisany i będzie Ci towarzyszył we wszystkich tickerach.