RY Royal Bank Of Canada Common Stock
NYSE · Banking · ดูใน SEC EDGAR ↗ ปิด ต.ค. 2, 2026 10-K/10-Q ธ.ค. 3, 2025RY ภาพรวมหุ้น ราคา, มูลค่าหลักทรัพย์ตามราคาตลาด, P/E, EPS, ROE, อัตราส่วนหนี้สินต่อทุน, ช่วงราคา 52 สัปดาห์
RY กราฟราคาหุ้น OHLCV รายวันพร้อมตัวชี้วัดทางเทคนิค — แพน ซูม และปรับแต่งมุมมองของคุณ
ความละเอียดของแท่งเทียนจะปรับตามช่วงเวลาที่เลือก — เลื่อนเมาส์เหนือแผนภูมิเพื่อดูราคาเปิด/สูงสุด/ต่ำสุด/ปิดของแท่งเทียน
| วันที่ไม่ได้รับสิทธิปันผล | การแตกหุ้น | ประเภท |
|---|---|---|
| 7 เมษายน 2006 | 2-for-1 | ไปข้างหน้า |
| 6 ตุลาคม 2000 | 2-for-1 | ไปข้างหน้า |
เกี่ยวกับ Royal Bank Of Canada Common Stock ภาพรวมบริษัทจาก Wikipedia
The Royal Bank of Canada (RBC; French: Banque Royale du Canada) is a Canadian multinational financial services company and the largest bank in Canada by market capitalization. The bank serves over 19 million clients and has more than 101,000 employees worldwide. Founded in 1864 in Halifax, Nova Scotia, it maintains its corporate headquarters in Toronto and its head office in Montreal. RBC's institution number is 003. In November 2017, RBC was added to the Financial Stability Board's list of global systemically important banks.
In Canada, the bank's personal and commercial banking operations are branded as RBC Royal Bank in English and RBC Banque Royale in French and serves approximately 11 million clients through its network of 1,263 branches. RBC Bank is a US banking subsidiary which formerly operated 439 branches across six states in the Southeastern United States, but now only offers cross-border banking services to Canadian travellers and expats. RBC's other Los Angeles-based US subsidiary City National Bank operates 79 branches across 11 US states. RBC also has 127 branches across seventeen countries in the Caribbean, which serve more than 16 million clients. RBC Capital Markets is RBC's worldwide investment and corporate banking subsidiary, while the investment brokerage firm is known as RBC Dominion Securities. Investment banking services are also provided through RBC Bank and the focus is on middle market clients. The company expanded further in 2024 when RBC acquired HSBC's Canadian operations.
In 2011, RBC was the largest Canadian company by revenue and market capitalization. In 2023, the company was ranked 38th in the Forbes Global 2000. The company has operations in Canada and 28 other countries, and had CA$1.574 trillion of assets under management in 2025.
History
In 1864, the Merchants Bank of Halifax was founded in Halifax, Nova Scotia, as a commercial bank that financed the fishing and timber industries and the European and Caribbean import/export businesses. By 1869 the Merchants' Bank was officially incorporated and received its federal charter in the same year. During the 1870s and 1880s, the bank expanded into the other Maritime Provinces. When both the Newfoundland Commercial Bank and Union Bank of Newfoundland collapsed on December 10, 1894, the Merchants Bank expanded to Newfoundland on January 31, 1895.
As the bank grew, executives changed its name to reflect its growth and western expansion. In 1901, the Merchants Bank of Halifax changed its name to the Royal Bank of Canada (RBC). As Canada’s financial activity became increasingly concentrated in Montreal, RBC moved its head office from Halifax to Montreal in 1907. In 1910, RBC merged with the Union Bank of Halifax. In the same year it built a bank branch in Winnipeg, Manitoba, designed by Carrère and Hastings, in beaux-arts classicism proclaiming the financial dominance of Winnipeg in the prairies. To improve its position in Ontario, RBC merged with Traders Bank of Canada in 1912 and in 1917 RBC merged with Quebec Bank, which was founded in 1818 and chartered in 1822 in Quebec City.
RBC's presence in Manitoba and Saskatchewan was strengthened through a 1918 merger with Northern Crown Bank, the product of the 1908 merger of Northern Bank (established in 1905 in Winnipeg) and Crown Bank of Canada (1904), based in Ontario. RBC's presence in the Canadian Prairie was further expanded by the 1925 merger with the Union Bank of Canada, which had begun in Quebec City in 1865 as the Union Bank of Lower Canada, but changed its name in 1886. The Union Bank of Canada had moved its headquarters to Winnipeg in 1912, and had built a strong presence in the Prairies and opened the first bank in the Northwest Territories at Fort Smith in 1921.
In 1935, RBC merged with Crown Savings and Loan Co. merged with Industrial Mortgage & Trust Co.
RoyWest Banking Corporation was formed in Nassau, Bahamas in 1965, to undertake medium-term lending and trustee business in the British West Indies. Majority owned by seven firms, including RBC and Westminster Bank, sole ownership transferred to National Westminster Bank in 1987.
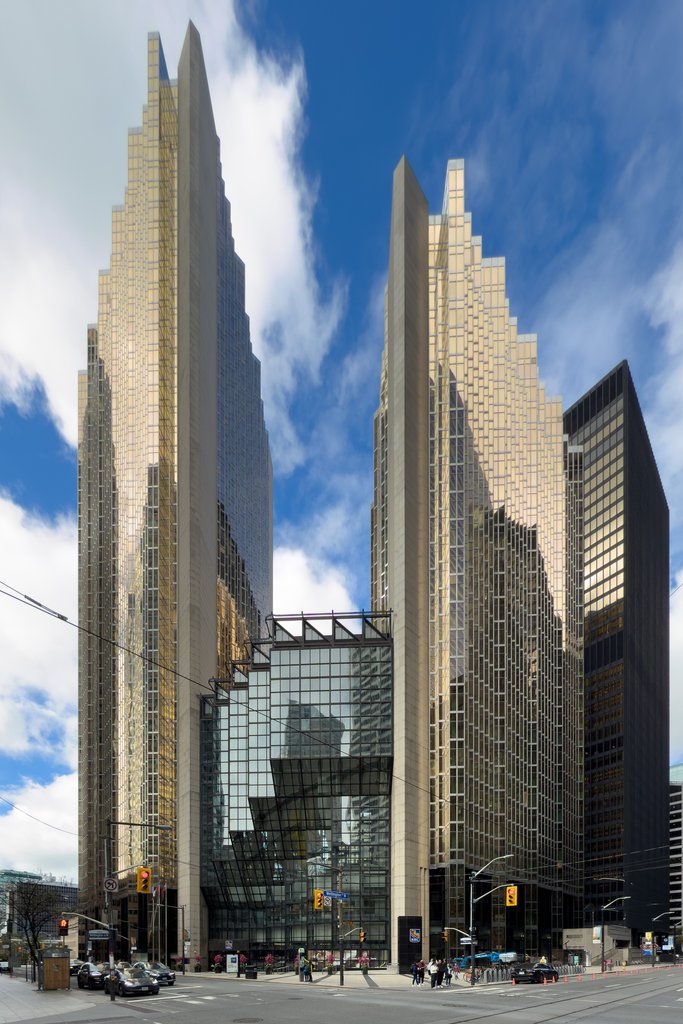
RBC installed its first computer in 1961, the IBM 1401, the first to do so in Canadian banking. In the 1960s, RBC Insurance was created. In 1968, it merged with Ontario Loan and Debenture Company (formerly Ontario Savings and Investment Society). RBC Insurance is the largest Canadian bank-owned insurance organization, with services to over five million people. It provides life, health, travel, home and auto and reinsurance products as well as creditor and business insurance services. The completion of Royal Bank Plaza in Toronto in 1976 saw the relocation of many critical head-office functions from Montreal, with Toronto serving as RBC's corporate headquarters ever since. In 1993, RBC merged with Royal Trust.
In 1998, RBC acquired Security First Network Bank in Atlanta—the first pure Internet bank. In the same year, the Royal Bank of Canada proposed to merge with the Bank of Montreal, at the same time as the Toronto-Dominion Bank proposed to merge with the Canadian Imperial Bank of Commerce. Both mergers were examined by the Competition Bureau of Canada, and ultimately rejected by Paul Martin, at the time the Finance Minister of Canada, and future Prime Minister.
In 2000, RBC merged merchant credit/debit card acquiring business with the Bank of Montreal's to form Moneris Solutions. In 2013, RBC completed the acquisition of the Canadian subsidiary of Ally Financial.
An RBC branch in The Glebe neighbourhood of Ottawa was firebombed in May 2010. The party responsible later identified themselves on Independent Media Center and threatened to make their presence at the upcoming 2010 G20 Toronto summit.
In November 2022, RBC and HSBC Canada announced a deal which would see RBC acquiring 100% of the common shares of HSBC Canada for an all-cash purchase price of $13.5 billion, a multiple of 9.4 times HSBC Canada's estimated 2024 earnings. Completion of the transaction is expected by late 2023, subject to regulatory approvals. In December 2023, RBC received approval from Finance Minister Chrystia Freeland to take over HSBC Bank in a deal. Conditions for the deal include that none of HSBC Canada's 4,000 employees will be laid off within six months of the closing date or two years for direct staff, and banking services will be provided at 33 HSBC branches for at least another four years. RBC will also provide $7 billion in financing for affordable housing developments in Canada.
International expansion
1882: Merchants Bank of Halifax opened offices in Bermuda and Newfoundland.
1899: RBC opened an agency in New York City and a branch in Havana.
1903: RBC bought Banco de Oriente de Santiago de Cuba. By the mid-1920s, RBC had 65 branches in Cuba and is the largest bank in the country.
1904: RBC bought Banco del Commercio de Havana.
1907: RBC opened a branch in San Juan, Puerto Rico; branches in Mayagüez and Ponce followed.
1909: RBC established a branch in Nassau, Bahamas.
1910: RBC opened a branch in London and acquired branches in Puerto Rico and Port of Spain, Trinidad as a result of its acquisition of Union Bank of Halifax.
1911: RBC opened an agency in New York City, and branches in Bridgetown, Barbados, and Kingston, Jamaica.
1912: RBC bought Bank of British Honduras (incorporated in 1902 by United States citizens from Mobile) in British Honduras, which it converted to a branch.
RBC opened a branch in the Dominican Republic; three more follow.
1913: RBC opened a branch in Grenada.
1914: RBC bought out Bank of British Guiana (est. 1836), in British Guiana, and converted it to a branch.
1915: RBC opened branches in Costa Rica, Antigua, Dominica, and Saint Kitts.
1916: RBC opened a branch in Venezuela.
1917: RBC opened branches in Antigua, Dominica, St. Kitts, Montserrat, Nevis, and Tobago.
1918: RBC opened a branch in Barcelona, and another in Vladivostok that lasted less than a year.
1919: RBC opened branches in Brazil, Argentina, Uruguay, Paris, Martinique, Guadeloupe, and Port-au-Prince, Haiti.
1920: RBC opened a branch in Colombia and a branch in Castries, St Lucia.
1923: RBC bought and consolidated the banking operations of Pedro Gomez Mena e Hijo in Cuba.
1925: RBC opened a branch in Peru, and acquired the American-owned, and failed, Bank of Central and South America. The purchase of BCSA brought with it subsidiaries, and their branches, in Colombia, Costa Rica, Peru, and Venezuela
1932: RBC closed its branch in St. Lucia.
1940: RBC closed its branches in Martinique and Guadeloupe.
1958: A representative office opened in Hong Kong, which became a branch in 1978.
1959: RBC opened a branch in St. Vincent.
1960: RBC returned to St. Lucia.
1960: Fidel Castro's regime acquired RBC's operations in Cuba on December 8. At the time of the forced sale, RBC had 24 branches in Cuba. From 1961 to 1965, RBC maintained a Special Representative in Havana to facilitate trade between Cuba and Canada. After the failed Bay of Pigs Invasion in April 1961, the Special Representative acted as a financial intermediary between the American and Cuban governments to manage the ransoming of the prisoners for food and agricultural machinery.
1964: RBC opened a branch in George Town, Cayman Islands.
1970s: As a result of Law 75, RBC's operations in Colombia became Banco Royal Colombiano.
1973: RBC was forced to incorporate its operations in Jamaica, which became Royal Bank (Jamaica).
1980: RBC purchased Banco de San Juan in Puerto Rico, adding its 14 branches to the six that RBC already had in Puerto Rico. RBC sold its assets in Grenada to Republic Bank of Trinidad and Tobago.
1985: RBC started to withdraw from much of the Caribbean.
It sold its 12 branches in the Dominican Republic to Banco de Comercio Dominicano.
It also sold its stake in Royal Bank (Jamaica) to Jamaica Mutual Life Assurance. Branches in Curaçao, Aruba, St. Maarten and Dominica are still open (1985–present)
The Government of Guyana nationalized its operations there and renamed the bank the National Bank of Industry and Commerce Ltd.
Additionally, RBC incorporated its operations in Trinidad and Tobago locally, floating the shares, thereby divesting itself of ownership. The new bank took the name Royal Bank of Trinidad and Tobago (RBTT).
1986: National Mutual Royal Bank opened in Australia with RBC having a 50% shareholding
1986: RBC sold its two branches in Haiti to Societe Generale Haitienne de Banque, a local bank.
1987: RBC sold its operations in Belize, ex-British Honduras, to Belize Holdings Inc., which renamed them Belize Bank.
1990: National Mutual Royal Bank in Australia sold to the Australia and New Zealand Banking Group
1993: RBC sold Royal Bank of Puerto Rico to Spain's Banco Bilbao-Vizcaya.
1995: RBC sold Royal Trust Bank (Austria) to Anglo Irish Bank, which renamed it Anglo Irish Bank (Austria).
2000: Acquired Dain Rauscher Wessels, a US brokerage and investment banking firm based in Minneapolis, Minnesota
2001: RBC acquired Centura Bank based in Rocky Mount, North Carolina.
2001: RBC bought the investment banking and brokerage firm Tucker Anthony Sutro (Boston) from John Hancock Mutual Life Insurance Co.
2003: RBC purchased Florida interest in Provident Financial Group, Cincinnati OH.
2003: Hong Kong branch started operating as a licensed bank.
2006: RBC upgraded its representative office in Beijing, China, to a branch.
2006: Created an institutional investment joint venture with Dexia. The 50/50 partnership operated under the name RBC Dexia Investor Services.
2007: RBC acquires Carlin Financial.
2008: RBC established a representative office in Mumbai, India. RBC re-acquired 98.14% of the shares of Royal Bank of Trinidad and Tobago. This brought RBC back to Trinidad and Tobago 20 years after it had withdrawn and provided it with a presence in other islands served by RBTT.
2011: RBC sold RBC Bank to PNC Financial Services for US$3.62 billion. PNC ATMs are now used by customers with RBC Bank (Georgia), N.A. providing Canadians with bank options when they are residing in the US.
2012: RBC completed the acquisition of Dexia's 50% stake in RBC Dexia Investor Services Limited, making it the sole owner of the newly named [RBC Investor & Treasury Services]. RBC also opened a Branch in Wilemstad, Curaçao.
2014: RBC "entered into a merger agreement to acquire City National Corporation", a major U. S. bank.
2015: RBC agreed to sell its Swiss private bank Royal Bank of Canada (Suisse) SA to local rival SYZ Group. Terms of the sale were not disclosed. Royal Bank of Canada (Suisse) manages CHF 10 billion (US$10.5 billion, C$13.4 billion) of assets for clients in Africa, the Middle East and South America.
2015: RBC completed the acquisition of City National Bank (November)
2016: On January 21, 2016, Aviva announced the acquisition of RBC General Insurance Company, for C$582 million.
2019: RBC agreed to sell its Eastern Caribbean banking operations, in places such as Antigua, Dominica, and Saint Lucia, to a consortium of banks in the region.
2022: RBC announced the acquisition of wealth manager Brewin Dolphin in the United Kingdom, in a deal which valued Brewin Dolphin at C$2.4bn (£1.6bn).
2024 RBC completed the acquisition of HSBC Canada, splitting some assets with the National Bank for competition issues.
Branding
Logo
The bank's first modern identity was designed by firm Lippincott & Margulies, and was introduced in January 1962. From this point forward the bank's logo has contained the same basic element of a stylized lion clutching a globe, becoming more simplified with each iteration. Alongside promotion of the Royal Bank Plaza, a tweaked version of the mark by Montreal design consultancy Gottschalk + Ash silently debuted in June 1979. The same basic form was retained, however many lines were thickened and details simplified to facilitate printing at small sizes. The total brand overhaul and shortening of the Royal Bank name to RBC in August 2001 coincided with their expansion into the United States market. The direction of the lion, now further simplified, was reversed, the crown above omitted, and both the symbol and wordmark were placed within a blue shield.
Sponsorship
RBC sponsors cultural events including the Toronto International Film Festival. It also sponsors the RBC Taylor Prize, a literary award for non-fiction writing in Canada, and hosts a yearly Canadian Women Entrepreneur Award. In July 2013, the RBC Foundation partnered with the University of Toronto to revive the Siminovitch Prize in Theatre, given to recognize achievement in Canadian theatre.
RBC is one of Canada's largest sponsors of amateur sports and is the longest-running Canadian sponsor of the Olympic Games. It employs dozens of top-tier amateur athletes as part-time spokespeople through the RBC Olympians program. RBC is a former premier sponsor of Hockey Canada and previously owned the naming rights to the National Junior A Championship, then called the Royal Bank Cup (later the RBC Cup). In addition, it supports Canadian hockey at the grassroots level through the RBC Play Hockey program.
RBC owns naming rights to the RBC Centre, RBC Convention Centre Winnipeg, RBC Canadian Open, and RBC Heritage (formerly the Heritage Classic). From 2002 to 2012, RBC previously held the naming rights to what is now the Lenovo Center in Raleigh, North Carolina.
RBC has owned naming rights for the Top 25 Canadian Immigrants Award, presented annually by Canadian Immigrant, since 2013.
RBC has also sponsored Major League Soccer in the United States since 2023. In 2025, RBC and its Los Angeles-based subsidiary City National Bank signed with the LA Galaxy to have its logo placed on the team's jersey sleeve and throughout the stadium.
Head offices
The head office for the institution was initially located at the Merchants' Bank of Halifax Building, on Bedford Row, Halifax, Nova Scotia. The building served as the head office for the bank from 1864 to 1907. In 1907, the RBC relocated its head office to the Four Pillars Building, at 147 Saint Jacques Street (renumbered 221 in 1928), Montreal. The building was used as RBC's head office until 1928. The Four Pillars Building was later demolished, with only its facade remaining. In 1928, RBC moved its head office to the Old Royal Bank Building, at 360 Saint Jacques Street, Montreal.
In 1962, RBC moved its head office to Place Ville-Marie, at University Street and René-Lévesque Boulevard in Montreal. In 1976, RBC moved its corporate headquarters to Royal Bank Plaza to 200 Bay Street in Toronto, although Place Ville-Marie remained its registered head office under the Bank Act. RBC makes the distinction that Royal Bank Plaza in Toronto is its corporate headquarters, while Place Ville-Marie in Montreal is its head office.
Controversies
Discrimination
On January 15, 2007, CBC Radio reported RBC was "refusing" to open US dollar accounts for people of certain nationalities. Canadian citizens with dual citizenship in Cuba, Iran, Iraq, Myanmar, North Korea or Sudan (mostly countries with US sanctions) were affected. The US Treasury Department restricts certain foreign nationals from using the US dollar payment system to limit terrorism and money laundering after the September 11, 2001, attacks. RBC replied that compliance with such laws does not represent an endorsement by the bank and on January 17, clarified its position on the application of the US laws, specifying that "with some exceptions" it does open accounts for dual citizens of the sanctioned countries. There have also been reports that the bank had closed the accounts of some Iranian-Canadian citizens.
Environment
According to a report by Rainforest Action Network, RBC's financing of oil sands bitumen extraction and expansion amounted to "more than $2.3 billion in loans and financing [of] more than $6.9 billion in [corporate] debt between 2003 and 2007 for 13 companies including: Encana, Husky Energy, OPTI Canada, Delphi Energy, Canadian Oil Sands Trust, Northwest Upgrading, Suncor, TotalEnergies, Connacher Oil and Gas, InterPipeline and Enbridge".
A 2020 report on fossil fuel finance by the Sierra Club and Rainforest Action Network found that RBC was the fifth largest funder of fossil fuels in the world, and largest in Canada, investing over US$160 billion on fossil fuel projects since the Paris Agreement in 2015. This sparked criticism from environmental groups and climate activists.
A more recent 2023 report from a coalition of environmental group places RBC as the largest financier of fossil fuel in the world in 2022, investing US$42 billion in fossil fuel projects in that year alone.
Funding of SCO litigation on Linux
RBC invested in SCO Group during the series of court cases seeking to collect royalties from the users of Linux.
Investor protection
In 2014, the Commodity Futures Trading Commission fined RBC $35,000,000 for engaging in more than 1,000 wash sales, fictitious sales, and other non-competitive practices over a three-year period.
Mismarking
In 2007, the Royal Bank of Canada fired several traders in its corporate bond business, after another trader accused them of mismarking bonds the bank held by overpricing them, and marked down the values of the bonds and recognized $13 million of trading losses relating to the bonds. The bank said it investigated the accusations, and took remedial action. The Globe and Mail noted: "traders might have an incentive to boost [the bonds'] prices because it could have an impact on their bonuses."
Temporary foreign workers and Canadian layoffs
In April 2013, the CBC reported that the Royal Bank of Canada was indirectly hiring temporary foreign workers to replace 45 Canadian information technology workers.
The CBC reported on May 7, 2013, that, during Question Period in Parliament, the NDP leveled accusations against the government and then Prime Minister Stephen Harper. Harper responded that the government has been working on problems with the Temporary Foreign Worker Program for more than a year.
Vacation pay class action lawsuit
On December 29, 2022, the Supreme Court of Ontario certified a class action lawsuit permitting employees of RBC Dominion Securities to seek $800 million in damages, over alleged unpaid wages for holidays and other vacation days.
Memberships
RBC is a member of the Canadian Bankers Association which includes Canada's Big Five banks, and is a registered member with the Canada Deposit Insurance Corporation, a federal agency insuring deposits at all of Canada's chartered banks.
It is also a member of:
Leadership
The office of chairman of the Board was created in October 1949 for outgoing president Sydney Dobson. Until 2001, the chairmanship was given to the current or former president. After John Cleghorn's retirement in 2001, the chairmanship was made a separate, non-executive position.
President
James W. Merkel, 1864–1869
Thomas Clifford Kinnear, 1869–1870
Thomas Edward Kenny, 1870–1908
Herbert Samuel Holt, 1908–1934
Morris Watson Wilson, 1934 – 13 May 1946
Sydney George Dobson, 4 June 1946 – 18 October 1949
James Muir, 18 October 1949 – 10 April 1960
Madison Melville Walter, 26 April 1960 – 9 December 1960
William Earle McLaughlin, 19 December 1960– 30 June 1977
Rowland Cardwell Frazee 1 July 1977 – 30 September 1980
Jock Kinghorn Finlayson, 1 October 1980 – 31 May 1983
Allan Richard Taylor, 1 June 1983 – 31 May 1986
John Edward Cleghorn, 1 June 1986 – 30 March 2001
Gordon Melbourne Nixon, 1 April 2001 – 31 July 2014
David Ian McKay 1 August 2014 –
Chairman of the Board
Sydney George Dobson, 18 October 1949 – 30 November 1954
James Muir, 1 December 1954 – 10 April 1960
Madison Melville Walter, 26 April 1960 – 9 December 1960
William Earle McLaughlin, 1962 – 30 September 1980
Rowland Cardwell Frazee, 1 October 1980 – 31 May 1986
Allan Richard Taylor, 1 June 1986 – 26 January 1995
John Edward Cleghorn, 26 January 1995 – 31 July 2001
Guy Saint-Pierre, 1 August 2001 – 27 February 2004
David Peter O'Brien, 27 February 2004 – 31 December 2013
Kathleen Patricia Taylor, 1 January 2014 – 5 April 2023
Jacynthe Côté, 5 April 2023 –
Awards
2025 - "Customer Service Excellence," "Recommended to Friends or Family (Net Promoter Score," "Financial Planning & Advice," "ATM Banking Excellence," "Online Banking Excellence," Ipsos 2025 Financial Service Excellence Awards
2025 - Ranked highest in customer satisfaction, J.D. Power 2025 Canada Retail Banking Advice Satisfaction Study
2025 - Canada's Best Investment Bank, Euromoney Awards for Excellence, 2025
2025 - North America's Best Bank for Research, Euromoney Awards for Excellence, 2025
2025 - "Most Valuable Canadian Brand 2025", Kantar BrandZ
2024 – RBC Dominion Securities, the highest-ranked bank-owned investment dealer in Canada, Investment Executive 2024 Brokerage Report Card
2024 – "Best Bank in Canada for Small and Medium-Sized Business," Global Finance
Operating Units
RBC has six divisions:
Personal Banking offers a range of banking and financial services to individuals and businesses across Canada, such as mortgages, loans, credit cards and bank and investment accounts.
Commercial Banking works with small to medium-sized businesses and large enterprises to deliver a variety of banking and commercial finance services, including bank accounts, loans, lines of credit and equipment financing. Its RBCx platform supports company founders and venture capital firms in the innovation economy with a wide range of financial services.
Wealth Management provides a variety of financial advisory services to its clients, including wealth, estate and retirement planning, business succession planning, private banking and philanthropic assistance. In September 2022, RBC acquired Brewin Dolphin, one of the U.K.'s largest wealth management firms.
Capital Markets is a global investment bank providing services in banking, finance, and capital markets to corporations, institutional investors, asset managers, and governments globally.
Insurance offers a range of personal and business-related insurance products, including health, home, auto, travel, wealth, and reinsurance advice and solutions. It also offers creditor and business insurance services to individual, business, and group clients.
Investor and Treasury Services (I&TS) provides custodial, advisory, financing, and other services to safeguard clients' assets, while also maximizing liquidity and managing risk. RBC Borealis, a division of I&TS, conducts finance-focused AI research and develops AI models for financial services.
Bank histories
McDowall, Duncan. Quick to the Frontier: Canada's Royal Bank. McClelland & Stewart, 1993.
Royal Bank of Canada. Fiftieth Anniversary of the Royal Bank of Canada: A Record of Its Progress during the Past Half Century. Royal Bank of Canada, 1920.
แหล่งที่มา: Wikipedia (ภาษาอังกฤษ), CC BY-SA 4.0 · ดูบน Wikipedia ↗
ผลการดำเนินงาน 10 ปี แนวโน้มรายได้ กำไรสุทธิ อัตรากำไร และ EPS
การประเมินมูลค่า อัตราส่วน P/E, P/S, P/B, EV/EBITDA — หุ้นมีราคาแพงหรือถูก?
| ตัวชี้วัด | แนวโน้ม 5 ปี | RY | ค่าเฉลี่ย 5 ปี | ค่ามัธยฐานของกลุ่มอุตสาหกรรม | บทสรุป |
|---|---|---|---|---|---|
| P/E | 10.4ค่าเฉลี่ย 5 ปี ≈9.3 | ≈9.3 | · | · |
ค่ามัธยฐานของกลุ่มบริษัทคำนวณตามมาตรฐานสำหรับแต่ละตัวชี้วัด และอาจไม่ตรงกับเกณฑ์ TTM/MRQ ที่แสดงสำหรับหุ้นนี้เสมอไป
ความสามารถในการทำกำไร อัตรากำไรขั้นต้น, อัตรากำไรจากการดำเนินงาน และอัตรากำไรสุทธิ; ROE, ROA, ROIC
| ตัวชี้วัด | แนวโน้ม 5 ปี | RY | ค่าเฉลี่ย 5 ปี | ค่ามัธยฐานของกลุ่มอุตสาหกรรม | บทสรุป |
|---|---|---|---|---|---|
| EBITDA Margin (อัตรากำไร EBITDA) | 4.6%ค่าเฉลี่ย 5 ปี ≈5.0% | ≈5.0% | · | · | |
| Pretax Margin (อัตรากำไรก่อนหักภาษี) | 38.5%ค่าเฉลี่ย 5 ปี ≈37.7% | ≈37.7% | · | · | |
| Net Profit Margin (อัตรากำไรสุทธิ) | 30.6%ค่าเฉลี่ย 5 ปี ≈30.0% | ≈30.0% | · | · | |
| ROA | 0.91%ค่าเฉลี่ย 5 ปี ≈0.86% | ≈0.86% | · | · | |
| ROE | 15.3%ค่าเฉลี่ย 5 ปี ≈14.9% | ≈14.9% | · | · |
สุขภาพทางการเงิน หนี้สิน, สภาพคล่อง, ความสามารถในการชำระหนี้ — ความแข็งแกร่งของงบดุล
ยังไม่มีข้อมูลพื้นฐานเพียงพอที่จะคำนวณกลุ่มอัตราส่วนนี้
การเติบโต การเติบโตของรายได้, EPS และกำไรสุทธิ: YoY, CAGR 3 ปี, CAGR 5 ปี
ยังไม่มีข้อมูลพื้นฐานเพียงพอที่จะคำนวณกลุ่มอัตราส่วนนี้
ประสิทธิภาพของเงินทุน อัตราหมุนเวียนสินทรัพย์, อัตราหมุนเวียนสินค้าคงคลัง, อัตราหมุนเวียนลูกหนี้
| ตัวชี้วัด | แนวโน้ม 5 ปี | RY | ค่าเฉลี่ย 5 ปี | ค่ามัธยฐานของกลุ่มอุตสาหกรรม | บทสรุป |
|---|---|---|---|---|---|
| Asset Turnover (อัตราหมุนเวียนสินทรัพย์) | 0.0ค่าเฉลี่ย 5 ปี ≈0.0 | ≈0.0 | · | · | |
| Revenue / Employee (รายได้ต่อพนักงาน (รายได้ต่อปี ÷ จำนวนพนักงาน (จำนวนพนักงานที่รายงาน, yfinance) — เป็นค่าที่ได้จากการคำนวณ ไม่ใช่แนวคิด SEC-XBRL ที่จัดเก็บไว้)) | ≈$657.7K | · | · | · |
มูลค่า · ≈ ค่าเฉลี่ย 5 ปี · ค่าเฉลี่ยอุตสาหกรรม · การตัดสินใจเทียบกับค่าเฉลี่ย
เงินปันผล ผลตอบแทน, อัตราการจ่ายเงินปันผล, ประวัติเงินปันผล, CAGR 5 ปี
| วันที่ไม่ได้รับสิทธิปันผล | จำนวน | สกุลเงิน | ผลตอบแทน |
|---|---|---|---|
| ก.ค. 27, 2026 | $1.25 | USD | ≈1.2% |
| เม.ย. 23, 2026 | $1.20 | USD | ≈1.3% |
| ก.ค. 24, 2025 | $1.13 | USD | ≈3.2% |
| เม.ย. 24, 2025 | $1.07 | USD | ≈3.5% |
| ม.ค. 27, 2025 | $1.03 | USD | ≈3.3% |
| ต.ค. 24, 2024 | $1.03 | USD | ≈3.3% |
| ก.ค. 25, 2024 | $1.03 | USD | ≈3.7% |
| เม.ย. 24, 2024 | $1.01 | USD | ≈4.2% |
| ม.ค. 24, 2024 | $1.03 | USD | ≈4.1% |
| ต.ค. 25, 2023 | $0.98 | USD | ≈5.0% |
| ก.ค. 25, 2023 | $1.03 | USD | ≈4.0% |
| เม.ย. 24, 2023 | $0.98 | USD | ≈3.9% |
| ม.ค. 25, 2023 | $0.99 | USD | ≈3.9% |
| ต.ค. 25, 2022 | $0.93 | USD | ≈4.2% |
| ก.ค. 25, 2022 | $0.99 | USD | ≈3.9% |
| เม.ย. 22, 2022 | $0.95 | USD | ≈3.5% |
| ม.ค. 25, 2022 | $0.95 | USD | ≈3.2% |
| ต.ค. 25, 2021 | $0.87 | USD | ≈3.2% |
| ก.ค. 23, 2021 | $0.86 | USD | ≈3.4% |
| เม.ย. 21, 2021 | $0.86 | USD | ≈3.6% |
ประวัติผลประกอบการ EPS จริงเทียบกับประมาณการ, เปอร์เซ็นต์ส่วนต่าง%, อัตราการชนะ, วันประกาศผลประกอบการครั้งถัดไป
| งวด | รายงาน | EPS Actual | EPS คาด | ส่วนต่าง |
|---|---|---|---|---|
| 30 กันยายน 2026 | $4.28 | $4.20 | 1.9% | |
| 30 มิถุนายน 2026 | $3.90 | $3.90 | 0.04% | |
| 31 มีนาคม 2026 | $4.08 | $3.96 | 3.0% | |
| 31 ธันวาคม 2025 | $3.85 | $3.63 | 6.0% | |
| 30 กันยายน 2025 | $3.84 | $3.42 | 12.3% | |
| 30 มิถุนายน 2025 | $3.12 | $3.28 | -4.9% |
ปัจจัยพื้นฐานฉบับเต็ม ตัวชี้วัดทั้งหมดรายปี — งบกำไรขาดทุน, งบดุล, งบกระแสเงินสด
งบกำไรขาดทุน
| ตัวชี้วัด | แนวโน้ม | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Revenue | $66.61B | $57.34B | $51.46B | $48.98B | $49.69B | $47.18B | $46.00B | $42.58B | |
| Interest Expense | $70.83B | $77.00B | $61.86B | $18.05B | $8.14B | $14.05B | $21.58B | $15.07B | |
| Interest Income | $103.83B | $104.95B | $86.99B | $40.77B | $28.14B | $34.88B | $41.33B | $33.02B | |
| Pretax Income | $25.65B | $19.86B | $18.18B | $20.11B | $20.63B | $14.39B | $15.91B | $15.76B | |
| Income Tax | $5.28B | $3.62B | $3.57B | $4.30B | $4.58B | $2.95B | $3.04B | $3.33B | |
| Net Income | $20.36B | $16.23B | $14.61B | $15.79B | $16.04B | $11.43B | $12.86B | $12.40B | |
| EPS (Basic) | $14.10 | $11.27 | $10.33 | $11.08 | $11.08 | $7.84 | $8.78 | $8.39 | |
| EPS (Diluted) | $14.07 | $11.25 | $10.32 | $11.06 | $11.06 | $7.82 | $8.75 | $8.36 | |
| Shares (Basic) | 1,409,072,000 | 1,411,903,000 | 1,391,020,000 | 1,403,654,000 | 1,424,343,000 | 1,423,915,000 | 1,434,779,000 | 1,443,894 | |
| Shares (Diluted) | 1,411,589,000 | 1,413,755,000 | 1,392,529,000 | 1,406,034,000 | 1,426,735,000 | 1,428,770,000 | 1,440,682,000 | 1,450,485 | |
| EBITDA | $3.04B | $2.91B | $2.76B | $2.63B | $2.56B | $2.61B | $1.82B | $1.65B |
งบดุล
| ตัวชี้วัด | แนวโน้ม | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $37.02B | $56.72B | $61.99B | $72.40B | $113.85B | $118.89B | $26.31B | $30.21B | |
| PP&E (Net) | $6.82B | $6.85B | $6.75B | $7.21B | $7.42B | $7.93B | $3.19B | $2.83B | |
| Goodwill | $19.41B | $19.29B | $12.59B | $12.28B | $10.85B | $11.30B | $11.24B | $11.14B | |
| Intangibles | $7.40B | $7.80B | $5.90B | $6.08B | $4.47B | $4.75B | $4.67B | $4.69B | |
| Total Assets | $2.33T | $2.17T | $2.01T | $1.92T | $1.71T | $1.62T | $1.43T | $1.33T | |
| Total Liabilities | $2.19T | $2.04T | $1.89T | $1.81T | $1.61T | $1.54T | $1.35T | $1.25T | |
| Retained Earnings | $96.94B | $88.61B | $81.72B | $78.04B | $71.80B | $59.81B | $55.98B | $51.11B | |
| Stockholders' Equity | $139.09B | $127.09B | $115.05B | $108.06B | $98.67B | $86.66B | $83.52B | $79.86B |
กระแสเงินสด
| ตัวชี้วัด | แนวโน้ม | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| D&A | $3.04B | $2.91B | $2.75B | $2.63B | $2.56B | $2.61B | $1.82B | $1.65B | |
| Other Non-cash | $31.81B | $4.00B | $8.46B | $3.51B | $42.44B | $124.78B | $-419M | $3.43B | |
| Operating Cash Flow | $55.22B | $23.14B | $26.08B | $21.94B | $61.04B | $138.82B | $14.27B | $17.47B | |
| Investing Cash Flow | $-68.57B | $-20.89B | $-28.27B | $-57.05B | $-57.35B | $-39.56B | $-11.13B | $-8.02B | |
| Dividends Paid | · | · | · | $6.96B | $6.42B | $6.33B | $6.03B | $5.64B | |
| Financing Cash Flow | $-6.71B | $-8.15B | $-9.83B | $-2.19B | $-5.93B | $-7.75B | $-7.46B | $-7.72B |
ความสามารถในการทำกำไร
| ตัวชี้วัด | แนวโน้ม | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Net Margin | 30.6% | 28.3% | 26.5% | 32.2% | 32.3% | 24.2% | 28.0% | 29.1% | |
| Pretax Margin | 38.5% | 34.6% | 32.9% | 41.0% | 41.5% | 30.5% | 34.6% | 37.0% | |
| EBITDA Margin | 4.6% | 5.1% | 4.9% | 5.4% | 5.2% | 5.5% | 4.0% | 3.9% | |
| ROA | 0.91% | 0.78% | 0.76% | 0.87% | 0.96% | 0.75% | 0.93% | 0.97% | |
| ROE | 15.3% | 13.4% | 13.2% | 15.3% | 17.3% | 13.4% | 15.7% | 16.1% |
ประสิทธิภาพ
| ตัวชี้วัด | แนวโน้ม | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
ต่อหุ้น
| ตัวชี้วัด | แนวโน้ม | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Revenue / Share | $47.18 | $40.56 | $40.31 | $34.84 | $34.83 | $33.02 | $31930.71 | $29352.94 | |
| Cash Flow / Share | $39.12 | $16.37 | $18.73 | $15.61 | $42.79 | $97.16 | $9901.56 | $12047.00 | |
| EPS (TTM) | $14.07 | $11.25 | $10.32 | $11.06 | $11.06 | $7.82 | $8.75 | $8.36 |
การประเมินมูลค่า (TTM)
| ตัวชี้วัด | แนวโน้ม | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $66.61B | $57.34B | $51.46B | $48.98B | $49.69B | $47.18B | $46.00B | $42.58B | |
| Net Income TTM | $20.36B | $16.23B | $14.61B | $15.79B | $16.04B | $11.43B | $12.86B | $12.40B | |
| P/E | 10.4 | 10.7 | 7.7 | 8.4 | 9.4 | 9.0 | 9.2 | 8.7 | |
| Earnings Yield | 9.6% | 9.3% | 12.9% | 12.0% | 10.6% | 11.2% | 10.8% | 11.5% | |
| Payout Ratio | · | · | · | 44.1% | 40.0% | 55.4% | 46.9% | 45.5% | |
| Annual Payout | · | · | · | $6.96B | $6.42B | $6.33B | $6.03B | $5.64B |
ต่อหุ้น
| ตัวชี้วัด | แนวโน้ม | Q4 2025 | Q4 2017 | Q4 2016 | Q4 2015 | Q4 2014 | Q4 2013 | Q4 2012 | Q4 2011 | Q4 2010 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| EPS (TTM) | $14.07 | $7.56 | · | · | · | · | · | · | · | · | · | · | · | · | · |
การประเมินมูลค่า (TTM)
| ตัวชี้วัด | แนวโน้ม | Q4 2025 | Q4 2017 | Q4 2016 | Q4 2015 | Q4 2014 | Q4 2013 | Q4 2012 | Q4 2011 | Q4 2010 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $66.61B | $40.67B | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| Net Income TTM | $20.36B | $11.43B | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| P/E | 10.4 | 10.3 | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| Earnings Yield | 9.6% | 9.7% | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| Annual Payout | · | $5.31B | · | · | · | · | · | · | · | · | · | · | · | · | · |
ช่วงเวลาล่าสุดอยู่ทางซ้าย · ค่า null แสดงเป็น ·
งบการเงิน งบกำไรขาดทุน, งบดุล, งบกระแสเงินสด — รายปี, 5 ปีล่าสุด
| ตัวชี้วัด | 2025-10-31 | 2024-10-31 | 2023-10-31 | 2022-10-31 | 2021-10-31 |
|---|---|---|---|---|---|
| รายได้ | $66.61B | $57.34B | $51.46B | $48.98B | $49.69B |
| กำไรสุทธิ | $20.36B | $16.23B | $14.61B | $15.79B | $16.04B |
| EPS ที่ปรับลดแล้ว | $14.07 | $11.25 | $10.32 | $11.06 | $11.06 |
ยังไม่มีข้อมูลพื้นฐานเพียงพอที่จะสร้างงบการเงินนี้
ยังไม่มีข้อมูลพื้นฐานเพียงพอที่จะสร้างงบการเงินนี้
ผู้ถือครองสถาบัน (13F) 1,083 รายงาน · $142.3B ทั้งหมด · ณ วันที่ 30 กันยายน 2026
สถาบันที่รายงานการถือครองหุ้นนี้ในเอกสาร SEC Form 13F รายไตรมาสของตน เฉพาะสถานะ Long; ผู้ยื่นคำร้องรายเดียวอาจปรากฏสองครั้งสำหรับสัญญาออปชันที่แยกจากกัน ขา put/call ขนาดใหญ่ที่หักล้างกันมักสะท้อนถึงการทำตลาด (market-making) หรือสินค้าคงคลังที่มีการป้องกันความเสี่ยง (hedged inventory) ไม่ใช่การเชื่อมั่นในทิศทาง
| พอร์ตใหม่ | ตำแหน่งที่ปิดไปแล้ว | เพิ่มขึ้น | ลดลง | การเปลี่ยนแปลงสุทธิของจำนวนหุ้น |
|---|---|---|---|---|
| 120 (-12 เทียบกับไตรมาสก่อน) | 64 (+4 เทียบกับไตรมาสก่อน) | 334 (0 เทียบกับไตรมาสก่อน) | 341 (+42 เทียบกับไตรมาสก่อน) | +13.9M |
เปรียบเทียบกับ Q1 2026. การยื่นแบบฟอร์ม 13F ของ SEC จะครบกำหนดภายใน 45 วันนับจากสิ้นสุดไตรมาส บวกกับระยะเวลาผ่อนผันสั้นๆ สำหรับผู้ยื่นล่าช้า — ไตรมาสที่ยังอยู่ในช่วงเวลานี้จะถูกข้ามไปเพื่อใช้คู่ที่รายงานล่าสุดอย่างสมบูรณ์
| สถาบัน | มูลค่า | หุ้น | % ของ 13F ที่ติดตาม | ประเภท |
|---|---|---|---|---|
| ROYAL BANK OF CANADA | $14,533,563,000 | 70,220,631 | 10.21% | หุ้น |
| BANK OF MONTREAL /CAN/ | $12,529,569,629 | 60,568,915 | 8.81% | หุ้น |
| VANGUARD GROUP INC | $11,529,165,258 | 67,628,463 | 8.10% | หุ้น |
| VANGUARD CAPITAL MANAGEMENT LLC | $8,837,424,821 | 42,678,029 | 6.21% | หุ้น |
| MACKENZIE FINANCIAL CORP | $5,474,404,300 | 18,640,712 | 3.85% | หุ้น |
| FIL Ltd | $4,864,230,588 | 23,490,517 | 3.42% | หุ้น |
| TD Asset Management Inc | $4,753,876,354 | 22,965,684 | 3.34% | หุ้น |
| NORGES BANK | $4,117,728,095 | 19,905,354 | 2.89% | หุ้น |
| CIBC WORLD MARKET INC. | $3,786,735,367 | 18,303,156 | 2.66% | หุ้น |
| FMR LLC | $3,686,407,722 | 17,803,517 | 2.59% | หุ้น |
| 1832 Asset Management L.P. | $3,526,088,076 | 17,036,711 | 2.48% | หุ้น |
| GEODE CAPITAL MANAGEMENT, LLC | $3,426,400,630 | 16,045,736 | 2.41% | หุ้น |
| NATIONAL BANK OF CANADA /FI/ | $3,378,842,571 | 16,356,045 | 2.37% | หุ้น |
| Federation des caisses Desjardins du Quebec | $2,695,312,709 | 13,071,369 | 1.89% | หุ้น |
| VANGUARD FIDUCIARY TRUST CO | $2,567,442,657 | 12,398,792 | 1.80% | หุ้น |
| BANK OF NOVA SCOTIA | $2,549,157,156 | 12,311,637 | 1.79% | หุ้น |
| TD Waterhouse Canada Inc. | $2,427,208,742 | 11,636,208 | 1.71% | หุ้น |
| MANUFACTURERS LIFE INSURANCE COMPANY, THE | $2,296,716,877 | 11,113,364 | 1.61% | หุ้น |
| CANADA PENSION PLAN INVESTMENT BOARD | $2,275,796,586 | 11,001,378 | 1.60% | หุ้น |
| Connor, Clark & Lunn Investment Management Ltd. | $2,260,819,710 | 10,928,916 | 1.59% | หุ้น |
| Vanguard Global Advisers, LLC | $2,224,443,419 | 10,742,367 | 1.56% | หุ้น |
| CIBC Asset Management Inc | $2,117,783,569 | 10,212,043 | 1.49% | หุ้น |
| SCOTIA CAPITAL INC. | $1,758,288,574 | 8,511,247 | 1.24% | หุ้น |
| Legal & General Group Plc | $1,645,757,717 | 7,950,572 | 1.16% | หุ้น |
| TORONTO DOMINION BANK | $1,634,521,110 | 7,900,458 | 1.15% | หุ้น |
| Fisher Asset Management, LLC | $1,461,695,402 | 7,062,353 | 1.03% | หุ้น |
| JPMORGAN CHASE & CO | $1,403,946,317 | 6,855,539 | 0.99% | หุ้น |
| GOLDMAN SACHS GROUP INC | $1,089,906,023 | 5,266,010 | 0.77% | หุ้น |
| MORGAN STANLEY | $824,775,725 | 3,985,000 | 0.58% | หุ้น |
| CHARLES SCHWAB INVESTMENT MANAGEMENT INC | $815,298,736 | 3,938,658 | 0.57% | หุ้น |
| Fiera Capital Corp | $800,513,843 | 3,872,821 | 0.56% | หุ้น |
| BAILLIE GIFFORD & CO | $740,153,088 | 3,575,634 | 0.52% | หุ้น |
| PICTON MAHONEY ASSET MANAGEMENT | $684,750,909 | 3,315,100 | 0.48% | หุ้น |
| VANGUARD ASSET MANAGEMENT, Ltd | $653,186,284 | 3,154,398 | 0.46% | หุ้น |
| HEALTHCARE OF ONTARIO PENSION PLAN TRUST FUND | $635,819,791 | 3,073,436 | 0.45% | หุ้น |
| Public Sector Pension Investment Board | $625,129,975 | 3,021,927 | 0.44% | หุ้น |
| BRITISH COLUMBIA INVESTMENT MANAGEMENT Corp | $588,345,296 | 2,844,107 | 0.41% | หุ้น |
| MASSACHUSETTS FINANCIAL SERVICES CO /MA/ | $577,116,710 | 2,000,754 | 0.41% | หุ้น |
| DIMENSIONAL FUND ADVISORS LP | $540,485,863 | 2,611,521 | 0.38% | หุ้น |
| DEUTSCHE BANK AG\ | $540,037,301 | 2,609,254 | 0.38% | หุ้น |
| Amundi | $535,456,408 | 2,586,842 | 0.38% | หุ้น |
| WELLINGTON MANAGEMENT GROUP LLP | $528,596,674 | 2,553,618 | 0.37% | หุ้น |
| AGF MANAGEMENT LTD | $522,781,370 | 2,228,739 | 0.37% | หุ้น |
| OMERS ADMINISTRATION Corp | $430,658,976 | 2,080,487 | 0.30% | หุ้น |
| FRANKLIN RESOURCES INC | $412,609,381 | 1,994,581 | 0.29% | หุ้น |
| MUFG SECURITIES (CANADA), LTD. | $408,754,132 | 1,977,134 | 0.29% | หุ้น |
| Caisse de depot et placement du Quebec | $360,367,457 | 1,740,913 | 0.25% | หุ้น |
| Invesco Ltd. | $331,336,278 | 1,600,890 | 0.23% | หุ้น |
| GUARDIAN CAPITAL LP | $330,433,521 | 1,596,304 | 0.23% | หุ้น |
| Assenagon Asset Management S.A. | $329,001,942 | 1,589,605 | 0.23% | หุ้น |
นักเคลื่อนไหวและเจ้าของ %+ 5 4 รายการ
นักลงทุนที่ยื่น SEC Schedule 13D — กรรมสิทธิ์ตามผลประโยชน์ที่แท้จริงสูงกว่า % 5 โดยมีเจตนาที่จะมีอิทธิพลต่อผู้ออกหลักทรัพย์ (การถือหุ้นของนักเคลื่อนไหว, การรณรงค์ในคณะกรรมการ, M&A) แต่ละแถวแสดงสถานะล่าสุดที่ทราบของตำแหน่งของผู้ยื่นคำร้องรายนั้น
| ผู้ยื่นคำร้อง | ยื่นแล้ว | ส่วนได้เสีย | สถานะ | วัตถุประสงค์ | การยื่นคำร้อง |
|---|---|---|---|---|---|
| Royal Bank of Canada, RBC Municipal Products, LLC ×9 เอกสารยื่นคำร้อง | 28 สิงหาคม 2017 | · | การยื่นคำร้องครั้งแรก | · | SEC |
| ผู้รายงานที่ไม่ได้เปิดเผย | 16 ตุลาคม 2002 | · | การยื่นคำร้องครั้งแรก | M&A / การขาย | SEC |
| ผู้รายงานที่ไม่ได้เปิดเผย | 13 สิงหาคม 2001 | · | การยื่นคำร้องครั้งแรก | M&A / การขาย | SEC |
| ผู้รายงานที่ไม่ได้เปิดเผย | 10 กรกฎาคม 2001 | · | การยื่นคำร้องครั้งแรก | · | SEC |
Purpose is an automated classification of the filer's own stated purpose (SEC Item 4) — not investment advice. "—" means no clear purpose was stated or the text could not be classified.
การถือครอง ETF ถือโดย ETF 71 ราย
น้ำหนักสะท้อนถึงการถือครองหุ้นโดยตรง (N-PORT) เท่านั้น กองทุนเลเวอเรจหรือกองทุนที่อิงตราสารอนุพันธ์อาจมีการเปิดรับความเสี่ยงจากสัญญาแลกเปลี่ยน (swap) เพิ่มเติมซึ่งไม่แสดง
| กองทุน | น้ำหนัก | หน่วย | ณ วันที่ | แหล่งที่มา |
|---|---|---|---|---|
| BBCA · J.P. Morgan Exchange-Traded Fund Tr… | 9.59% | 4,974,197 NS | 31 กรกฎาคม 2026 | N-PORT |
| EWC · iShares, Inc. | 9.27% | 3,070,526 SH | 11 กันยายน 2026 | รายวัน |
| IDMO · Invesco Exchange-Traded Fund Trust … | 5.14% | 1,121,704 SH | 1 ตุลาคม 2026 | รายวัน |
| VIGI · VANGUARD WHITEHALL FUNDS | 4.90% | 2,153,489 SH | 19 สิงหาคม 2026 | รายวัน |
| IMTM · iShares Trust | 3.29% | 690,878 SH | 11 กันยายน 2026 | รายวัน |
| QLVD · FlexShares Trust | 2.97% | 7,776 NS | 31 กรกฎาคม 2026 | N-PORT |
| IGRO · iShares Trust | 2.80% | 175,358 SH | 11 กันยายน 2026 | รายวัน |
| PIZ · Invesco Exchange-Traded Fund Trust … | 2.23% | 74,655 SH | 1 ตุลาคม 2026 | รายวัน |
| DIVD · EA Series Trust | 2.12% | 2,166 NS | 31 กรกฎาคม 2026 | N-PORT |
| FEDM · FlexShares Trust | 1.98% | 7,497 NS | 31 กรกฎาคม 2026 | N-PORT |
| IXG · iShares Trust | 1.80% | 60,633 SH | 11 กันยายน 2026 | รายวัน |
| PABD · iShares Trust | 1.58% | 25,388 SH | 11 กันยายน 2026 | รายวัน |
| VYMI · VANGUARD WHITEHALL FUNDS | 1.57% | 1,562,557 SH | 19 สิงหาคม 2026 | รายวัน |
| EFFI · Harbor ETF Trust | 1.49% | 10,987 NS | 31 กรกฎาคม 2026 | N-PORT |
| PID · Invesco Exchange-Traded Fund Trust | 1.35% | 57,689 SH | 1 ตุลาคม 2026 | รายวัน |
| BSCR · Invesco Exchange-Traded Self-Indexe… | 1.28% | 58,104,000 | 1 ตุลาคม 2026 | รายวัน |
| FIDI · Fidelity Covington Trust | 1.23% | 21,306 NS | 31 กรกฎาคม 2026 | N-PORT |
| RODM · Lattice Strategies Trust | 1.22% | 95,068 NS | 31 กรกฎาคม 2026 | N-PORT |
| PTIN · Pacer Funds Trust | 1.22% | 10,763 NS | 31 กรกฎาคม 2026 | N-PORT |
| PICB · Invesco Exchange-Traded Fund Trust … | 1.19% | 5,300,000 | 1 ตุลาคม 2026 | รายวัน |
| INTF · iShares Trust | 1.18% | 214,432 SH | 11 กันยายน 2026 | รายวัน |
| FDEV · Fidelity Covington Trust | 1.13% | 15,359 NS | 31 กรกฎาคม 2026 | N-PORT |
| BKIE · BNY Mellon ETF Trust | 1.13% | 70,741 NS | 31 กรกฎาคม 2026 | N-PORT |
| DFSI · Dimensional ETF Trust | 1.12% | 61,409 NS | 31 กรกฎาคม 2026 | N-PORT |
| JIVE · J.P. Morgan Exchange-Traded Fund Tr… | 1.09% | 181,623 NS | 31 กรกฎาคม 2026 | N-PORT |
| DFAI · Dimensional ETF Trust | 0.99% | 829,128 NS | 31 กรกฎาคม 2026 | N-PORT |
| IDEV · iShares Trust | 0.97% | 1,531,433 SH | 11 กันยายน 2026 | รายวัน |
| VEA · VANGUARD TAX-MANAGED FUNDS | 0.88% | 13,680,318 SH | 19 สิงหาคม 2026 | รายวัน |
| DFIC · Dimensional ETF Trust | 0.87% | 614,054 NS | 31 กรกฎาคม 2026 | N-PORT |
| VSGX · VANGUARD WORLD FUND | 0.86% | 280,967 SH | 19 สิงหาคม 2026 | รายวัน |
| IQDY · FlexShares Trust | 0.84% | 4,446 NS | 31 กรกฎาคม 2026 | N-PORT |
| ACWX · iShares Trust | 0.76% | 459,819 SH | 11 กันยายน 2026 | รายวัน |
| COMT · iShares U.S. ETF Trust | 0.74% | 10,070,000 SH | 11 กันยายน 2026 | รายวัน |
| VEU · VANGUARD INTERNATIONAL EQUITY INDEX… | 0.70% | 3,272,998 SH | 19 สิงหาคม 2026 | รายวัน |
| GLBL · Pacer Funds Trust | 0.70% | 37 NS | 31 กรกฎาคม 2026 | N-PORT |
| IDLV · Invesco Exchange-Traded Fund Trust … | 0.67% | 10,859 SH | 1 ตุลาคม 2026 | รายวัน |
| IXUS · iShares Trust | 0.66% | 1,919,984 SH | 11 กันยายน 2026 | รายวัน |
| VXUS · VANGUARD STAR FUNDS | 0.64% | 20,563,849 SH | 19 สิงหาคม 2026 | รายวัน |
| IQDF · FlexShares Trust | 0.63% | 34,650 NS | 31 กรกฎาคม 2026 | N-PORT |
| DFAX · Dimensional ETF Trust | 0.61% | 351,449 NS | 31 กรกฎาคม 2026 | N-PORT |
| PXF · Invesco Exchange-Traded Fund Trust … | 0.55% | 81,239 SH | 1 ตุลาคม 2026 | รายวัน |
| TLTD · FlexShares Trust | 0.54% | 17,391 NS | 31 กรกฎาคม 2026 | N-PORT |
| RCGE · EA Series Trust | 0.49% | 2,340 NS | 31 กรกฎาคม 2026 | N-PORT |
| GSY · Invesco Actively Managed Exchange-T… | 0.47% | 17,933,000 | 1 ตุลาคม 2026 | รายวัน |
| BSCS · Invesco Exchange-Traded Self-Indexe… | 0.41% | 14,181,000 | 1 ตุลาคม 2026 | รายวัน |
| DXIV · Dimensional ETF Trust | 0.38% | 3,700 NS | 31 กรกฎาคม 2026 | N-PORT |
| TOK · iShares Trust | 0.34% | 3,893 SH | 11 กันยายน 2026 | รายวัน |
| URTH · iShares, Inc. | 0.32% | 125,484 SH | 11 กันยายน 2026 | รายวัน |
| VOXP · Advisors Series Trust | 0.31% | 87 NS | 31 กรกฎาคม 2026 | N-PORT |
| CRBN · iShares Trust | 0.31% | 17,690 SH | 11 กันยายน 2026 | รายวัน |
| ACWI · iShares Trust | 0.28% | 442,504 SH | 11 กันยายน 2026 | รายวัน |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0.25% | 1,160,961 SH | 19 สิงหาคม 2026 | รายวัน |
| BSCT · Invesco Exchange-Traded Self-Indexe… | 0.23% | 6,883,000 | 30 กันยายน 2026 | รายวัน |
| IMFL · Invesco Exchange-Traded Self-Indexe… | 0.15% | 8,234 SH | 1 ตุลาคม 2026 | รายวัน |
| DIHP · Dimensional ETF Trust | 0.05% | 14,362 NS | 31 กรกฎาคม 2026 | N-PORT |
| GTO · Invesco Actively Managed Exchange-T… | 0.03% | 1,028,000 | 1 ตุลาคม 2026 | รายวัน |
| GTOS · Invesco Actively Managed Exchange-T… | 0.03% | 38,000 | 1 ตุลาคม 2026 | รายวัน |
| GLOF · iShares Trust | 0.02% | 205 SH | 11 กันยายน 2026 | รายวัน |
| VRIG · Invesco Actively Managed Exchange-T… | 0.01% | 200,000 | 29 กันยายน 2026 | รายวัน |
| FTLS · First Trust Exchange-Traded Fund III | -0.22% | -25,586 NS | 31 กรกฎาคม 2026 | N-PORT |
| BIV · VANGUARD BOND INDEX FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| BSV · VANGUARD BOND INDEX FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| BND · VANGUARD BOND INDEX FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| VUSB · VANGUARD BOND INDEX FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| VCRB · VANGUARD MALVERN FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| VCSH · VANGUARD SCOTTSDALE FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| VCIT · VANGUARD SCOTTSDALE FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| VTC · VANGUARD SCOTTSDALE FUNDS | · | · | 30 กรกฎาคม 2026 | รายวัน |
| BNDW · VANGUARD SCOTTSDALE FUNDS | · | · | 30 กรกฎาคม 2026 | รายวัน |
| BNDX · VANGUARD CHARLOTTE FUNDS | · | · | 15 กรกฎาคม 2026 | รายวัน |
| VCEB · VANGUARD WORLD FUND | · | · | 30 กรกฎาคม 2026 | รายวัน |
RY ความเห็นหลายต่อหลายของนักวิเคราะห์ มุมมองนักวิเคราะห์ทั้งเชิงบวกและเชิงลบ, ราคาเป้าหมาย 12 เดือน, อัพไซด์
ราคาเป้าหมาย 12 เดือน
3 นักวิเคราะห์ · 2026-10-01ราคาเป้าหมายค่าเฉลี่ย $207.80 +6.2%
ข่าวล่าสุด หัวข้อข่าวล่าสุดที่กล่าวถึงบริษัทนี้
RY AI Analyst Panel — มุมมองเชิงบวกและเชิงลบ การถกเถียง 2026Q2: Claude, Grok, Gemini, ChatGPT เกี่ยวกับแนวโน้มของหุ้น
Royal Bank of Canada เผชิญกับการต่อสู้ระหว่างสถานะของการเป็นผู้ให้กู้ที่มีประสิทธิภาพสูงและความเป็นจริงของสภาพแวดล้อมอัตราดอกเบี้ยที่เย็นลง Grok ยังคงมองโลกในแง่ดี โดยเดิมพันว่าอัตรากำไรที่ยืดหยุ่นจะขับเคลื่อนหุ้นให้สูงขึ้น ในขณะที่ Claude, Gemini และ ChatGPT เตือนว่า P/E ปัจจุบันที่ 15.7 เท่า ได้คำนวณความสมบูรณ์แบบไว้แล้ว คณะกรรมการมีความเห็นแตกต่างกันอย่างมากว่า ROE 15.4% ของธนาคารสมเหตุสมผลกับการประเมินมูลค่าพรีเมียมหรือไม่ หรือวัฏจักรการลดอัตราดอกเบี้ยที่กำลังจะมาถึงจะบีบอัดกำไรในอนาคตอย่างหลีกเลี่ยงไม่ได้
รอบที่ 1 — มุมมองเริ่มต้น
ฉันมองว่า RY จะส่งมอบการเติบโตที่มั่นคง เนื่องจากธนาคารที่ใหญ่ที่สุดของแคนาดาใช้ประโยชน์จากการลงสู่ภาวะเศรษฐกิจที่อ่อนตัวและอัตราดอกเบี้ยที่สูงขึ้นเป็นเวลานาน ROE ของธนาคารได้เพิ่มขึ้นเป็น 15.37% ซึ่งพิสูจน์ให้เห็นถึงการใช้ส่วนของผู้ถือหุ้นอย่างมีประสิทธิภาพในการสร้างผลกำไรท่ามกลางสินเชื่อที่มั่นคง EPS TTM อยู่ที่ 14.94 ดอลลาร์สหรัฐฯ สะท้อนถึงความสามารถในการทำกำไรที่ยืดหยุ่นซึ่งสนับสนุนเงินปันผลที่เชื่อถือได้ ที่ P/E 15.7 เท่า หุ้นซื้อขายที่ระดับที่สมเหตุสมผล ทำให้มีพื้นที่สำหรับการขยายตัวของหลายเท่าหากแนวโน้มยังคงอยู่
RY ร่วงลงหากการปรับลดอัตราดอกเบี้ยอย่างจริงจังทำให้เกิดการผิดนัดชำระหนี้และบีบอльноดอกเบี้ยสุทธิในช่วงขาลง อัตราส่วนหนี้สินต่อทุนยังคงอยู่ที่ประมาณ 2.5 เท่า เพิ่มความเสี่ยงจากวัฏจักรสินเชื่อใดๆ ที่ส่งผลกระทบต่อคุณภาพของสินทรัพย์ P/B ที่ 2.07 ดูเหมือนจะเต็มเมื่อการเติบโตของ ROE ชะงักงัน ทำให้ผู้ถือหุ้นเผชิญกับการลดลงของมูลค่าทางบัญชี ราคาที่หยุดนิ่งล่าสุดใกล้ 132 ดอลลาร์สหรัฐฯ หลังจากการปรับตัวขึ้น ส่งสัญญาณถึงความอ่อนล้าที่อาจเกิดขึ้นหากแรงกดดันจากปัจจัยมหภาคส่งผลกระทบ
Royal Bank เป็นงบดุลที่แข็งแกร่งซึ่งสร้างผลตอบแทนที่แข็งแกร่งในภาคส่วนที่ระเบียบวินัยด้านเงินทุนมีความสำคัญ การตีความของฉันคือ ROE ที่ 15.4% — นั่นคือผลกำไรที่สร้างขึ้นต่อดอลลาร์ของส่วนของผู้ถือหุ้น — นั้นแข็งแกร่งอย่างแท้จริงสำหรับธนาคารที่มีการกำกับดูแล และอัตรากำไรสุทธิ 26% บ่งบอกว่าอำนาจในการกำหนดราคาเป็นของจริงแม้ในตลาดแคนาดาที่มีการแข่งขันสูง หุ้นปรับตัวขึ้นจาก 117 ดอลลาร์สหรัฐฯ เป็น 132 ดอลลาร์สหรัฐฯ ในสี่เดือน แต่ P/E เพิ่มขึ้นเพียงจาก 13.0 เป็น 15.7 นั่นบ่งชี้ว่าตลาดยังคงประเมินความระมัดระวัง ไม่ใช่ความสุขที่มากเกินไป หากความผันผวนของอัตราดอกเบี้ยมีเสถียรภาพและการเติบโตของสินเชื่อเร่งตัวขึ้น หุ้นนี้จะซื้อขายสูงขึ้น
กรณีขาขึ้นสมมติว่าอัตราดอกเบี้ยยังคงสูงและอุปสงค์สินเชื่อฟื้นตัว — แต่ฉันเห็นปัจจัยกดดันเชิงโครงสร้าง อัตราส่วน P/B ที่ 2.07 เท่า ไม่ใช่ราคาถูกสำหรับธนาคาร โดยเฉพาะอย่างยิ่งธนาคารที่มีอัตราส่วนหนี้สินต่อทุน 2.5 เท่า ซึ่งเป็นเรื่องปกติสำหรับภาคส่วนนี้ แต่ก็ไม่เหลือช่องว่างสำหรับความประหลาดใจด้านสินเชื่อ ที่สำคัญกว่านั้นคือ มูลค่าหลักทรัพย์ตามราคาตลาดลดลงจาก 337 พันล้านดอลลาร์สหรัฐฯ เป็น 329 พันล้านดอลลาร์สหรัฐฯ ในหนึ่งไตรมาส ในขณะที่ราคาหุ้นทรงตัว นั่นคือสัญญาณเตือนของการบีบอัดหลายเท่า หากการเติบโตทางเศรษฐกิจของแคนาดาผิดหวังหรือการแข่งขันด้านเงินฝากทวีความรุนแรงขึ้น กำไรสุทธิจะลดลงและหุ้นจะถูกประเมินมูลค่าใหม่ต่ำลง
Royal Bank of Canada ยังคงเป็นป้อมปราการเชิงรับที่เปลี่ยนทุนของผู้ถือหุ้นให้เป็นผลกำไรที่มีความหมายอย่างสม่ำเสมอ บริษัทสร้างผลตอบแทนต่อส่วนของผู้ถือหุ้นที่ 15.37% ระดับประสิทธิภาพนี้แสดงให้เห็นว่าผู้บริหารมีความสามารถในการดึงมูลค่าออกจากฐานเงินทุนของตนได้อย่างมีประสิทธิภาพ แม้ในสภาพแวดล้อมอัตราดอกเบี้ยที่เข้มงวด นอกจากนี้ ธนาคารยังคงรักษาส่วนแบ่งกำไรสุทธิที่แข็งแกร่งที่ 26.26% สิ่งนี้บ่งชี้ว่ามากกว่าหนึ่งในสี่ของทุกดอลลาร์ที่ได้รับเป็นรายได้จะเข้าสู่บรรทัดสุดท้าย ซึ่งเป็นกันชนที่สำคัญต่อการสูญเสียสินเชื่อที่อาจเกิดขึ้นหรือความผันผวนทางเศรษฐกิจในตลาดที่อยู่อาศัยของแคนาดา
หุ้นเริ่มดูมีราคาแพงเมื่อเทียบกับการประเมินมูลค่าในอดีตของตัวเอง ซึ่งบ่งชี้ว่าตลาดอาจได้คำนวณสถานการณ์ที่ดีที่สุดไว้แล้ว อัตราส่วน P/E ได้เพิ่มขึ้นเป็น 15.67 เท่าของกำไรในอดีต ค่าหลายเท่านี้มีแนวโน้มสูงขึ้น หมายความว่านักลงทุนกำลังจ่ายเงินมากขึ้นในวันนี้สำหรับผลกำไรจำนวนเท่าเดิมมากกว่าเมื่อไม่กี่ไตรมาสที่ผ่านมา นอกจากนี้ อัตราส่วนราคาต่อมูลค่าทางบัญชีอยู่ที่ 2.07 เท่า การจ่ายเงินเป็นสองเท่าของมูลค่าทางบัญชีสำหรับหุ้นธนาคารเป็นค่าพรีเมียมที่สูงมาก ซึ่งเหลือช่องว่างน้อยมากสำหรับข้อผิดพลาดหากการเติบโตชะงักงันหรือสภาวะสินเชื่อแย่ลง
ฉันคิดว่ากรณีขาขึ้นที่แข็งแกร่งที่สุดของ RBC คือการรวมกันของความสามารถในการทำกำไรที่ยั่งยืนกับการประเมินมูลค่าที่สมเหตุสมผล P/E TTM อยู่ที่ประมาณ 15.7 เท่า นั่นบ่งชี้ว่าตลาดจ่ายในราคาที่เหมาะสมสำหรับธนาคารคุณภาพสูงที่มีกำไรสม่ำเสมอ อัตรากำไรสุทธิอยู่ที่ประมาณ 26.3% นั่นหมายความว่า RBC แปลงรายได้ส่วนใหญ่ให้เป็นกำไร ซึ่งสนับสนุนความสามารถในการทำกำไรที่สม่ำเสมอมากขึ้น ROE อยู่ที่ประมาณ 15.4% นั่นแสดงให้เห็นถึงการใช้ส่วนของผู้ถือหุ้นอย่างมีประสิทธิภาพและผลตอบแทนที่สามารถสนับสนุนการเติบโตของเงินปันผลได้ หากแนวโน้มเหล่านี้ยังคงอยู่ หุ้นอาจทบต้นจากความยืดหยุ่นของกำไร บวกกับการสนับสนุนค่าหลายเท่าที่เอื้ออำนวย
ฉันคิดว่ากรณีหมีที่แข็งแกร่งที่สุดของ RBC คือการใช้ประโยชน์และความเป็นวัฏจักรอาจส่งผลกระทบหากการเติบโตชะลอตัว P/S TTM อยู่ที่ประมาณ 3.0x นั่นส่งสัญญาณว่าตลาดได้คำนวณการเติบโตที่แข็งแกร่งไว้แล้ว การชะลอตัวอาจทำให้ค่าหลายเท่าลดลง หนี้สินต่อทุนประมาณ 2.5 เท่า การใช้ประโยชน์สูงเพิ่มความอ่อนไหวต่อต้นทุนสินเชื่อและภาวะเศรษฐกิจถดถอย P/B รายปีอยู่ที่ประมาณ 2.07 เท่า นั่นเหลือช่องว่างน้อยหาก ROE กลับสู่ภาวะปกติหรือแรงกดดันด้านกฎระเบียบ/สินเชื่อเพิ่มขึ้น สรุป: การประเมินมูลค่าดูแข็งแกร่งพอที่จะจำกัด upside หากปัจจัยมหภาคที่น่าประหลาดใจโน้มเอียงไปทางลบ
รอบที่ 2 — การตอบกลับและการโต้แย้ง
รอบที่ 2 — การตอบกลับและการโต้แย้ง
Claude เรื่องมูลค่าหลักทรัพย์ตามราคาตลาดของคุณที่ลดลงจาก 337 พันล้านดอลลาร์สหรัฐฯ เป็น 329 พันล้านดอลลาร์สหรัฐฯ พลาดเรื่องราวการเคลื่อนไหวของราคาที่แท้จริง — หุ้นได้ปรับตัวขึ้น 12% จาก 118 ดอลลาร์สหรัฐฯ ในช่วงปลายเดือนเมษายน เป็น 132 ดอลลาร์สหรัฐฯ ในวันนี้ การปรับตัวขึ้นนั้นแสดงให้เห็นถึงอุปสงค์ของนักลงทุนที่เอาชนะการเจือจางหุ้นใดๆ สนับสนุนกรณีการซื้อของฉัน เนื่องจากอัตราดอกเบี้ยที่สูงขึ้นเป็นเวลานานจะช่วยเพิ่มรายได้ดอกเบี้ยสุทธิ P/B ที่ 2.07 เท่า ยังคงดูสมเหตุสมผลเมื่อประสิทธิภาพ ROE อยู่ที่ 15.4% ซึ่งส่งสัญญาณถึงพื้นที่สำหรับการขยายตัวหากการเติบโตของสินเชื่อกลับมา
ฉันต้องโต้แย้งความมั่นใจของ Grok ที่นี่ Grok กล่าวว่า P/E ที่ 15.7 เท่า เหลือพื้นที่สำหรับการขยายตัวของค่าหลายเท่า แต่ก็พลาดสิ่งที่ฉันชี้แจงในรอบที่ 1 — P/E ได้เพิ่มขึ้นจาก 13.0 เป็น 15.7 ในเวลาเพียงเก้าเดือน ในขณะที่หุ้นปรับตัวขึ้นเพียง 12% นั่นคือการขยายตัวของค่าหลายเท่าที่เกิดขึ้นแล้ว และมันเกิดขึ้นเร็วกว่าการเติบโตของกำไร หากตลาดได้ประเมินมูลค่า RY ใหม่จาก 13 เท่า เป็น 15.7 เท่า จากความสามารถในการทำกำไรเท่าเดิม เงินที่ได้มาง่ายๆ หมดไปแล้ว การเคลื่อนไหวครั้งต่อไปต้องการการเร่งตัวของกำไรที่แท้จริง ไม่ใช่แค่การสนับสนุนค่าหลายเท่า กรณี 'ซื้อ' ของ Grok พึ่งพาการประเมินมูลค่าที่ยังคงสูงเกินไปมากเกินไป
Claude ประเด็นของคุณเกี่ยวกับมูลค่าหลักทรัพย์ตามราคาตลาดที่ลดลงในขณะที่ราคาหุ้นทรงตัวเป็นข้อสังเกตที่สำคัญซึ่งเน้นย้ำถึงความเสี่ยงด้านสภาพคล่องที่ละเอียดอ่อนหรือความเสี่ยงจากการเจือจางจำนวนหุ้น มูลค่าหลักทรัพย์ตามราคาตลาดลดลงจาก 337 พันล้านดอลลาร์สหรัฐฯ เป็น 329 พันล้านดอลลาร์สหรัฐฯ ในหนึ่งไตรมาส สิ่งนี้ส่งสัญญาณว่ามูลค่ารวมที่ตลาดกำหนดให้กับธนาคารกำลังหดตัว แม้ว่าราคาหุ้นจะยังคงอยู่ในช่วงแคบๆ ซึ่งมักจะนำไปสู่การแก้ไขที่ลึกขึ้น ฉันเห็นด้วยว่าเรากำลังเห็นการบีบอัดค่าหลายเท่า และความแตกต่างระหว่างการเคลื่อนไหวของราคาและมูลค่าตราสารทุนทั้งหมดนี้ทำให้ฉันระมัดระวังมากขึ้นเกี่ยวกับการไล่ตามหุ้นในระดับเหล่านี้
Claude ประเด็นของคุณเกี่ยวกับการขยายตัวของ P/E ที่สะท้อนถึงความระมัดระวังพลาดเหตุผลที่ค่าหลายเท่าสามารถสะท้อนถึงความสามารถในการทำกำไรได้ที่นี่ P/E อยู่ที่ประมาณ 15.7 เท่า เพิ่มขึ้นจากประมาณ 13 เท่าก่อนหน้านี้ นั่นหมายความว่านักลงทุนกำลังคำนวณกำไรที่สม่ำเสมอมากขึ้นและผลตอบแทนที่ยืดหยุ่น ซึ่งอาจสนับสนุน upside ที่เลือกสรรสำหรับ RBC หากอัตราดอกเบี้ยมีเสถียรภาพและสินเชื่อมีความเสี่ยงที่สามารถจัดการได้ ความเสี่ยงคือการใช้ประโยชน์และความเป็นวัฏจักรยังคงทำให้ช่องว่างพร่ามัว ดังนั้นเวลาเข้าจึงมีความสำคัญ
รอบที่ 3 — การโต้แย้งสุดท้าย
รอบที่ 3 — การโต้แย้งสุดท้าย
Gemini คำเตือนของคุณเกี่ยวกับการเจือจางจำนวนหุ้นจากการลดลงของมูลค่าหลักทรัพย์ตามราคาตลาดพลาดการทะลุแนวต้านทางเทคนิคที่กำลังดึงดูดผู้ซื้อ RY พุ่งขึ้น 12% จาก 118 ดอลลาร์สหรัฐฯ ในช่วงปลายเดือนเมษายน เป็น 132 ดอลลาร์สหรัฐฯ ในปัจจุบัน ทำลายแนวต้าน 130 ดอลลาร์สหรัฐฯ ด้วยปริมาณการซื้อขายรายสัปดาห์เกิน 5 ล้านหุ้น รูปแบบการไหลนี้แสดงให้เห็นถึงการวางตำแหน่งระยะยาวของสถาบันก่อนที่เสถียรภาพของอัตราดอกเบี้ยของธนาคารแห่งแคนาดาจะช่วยเพิ่ม NIM เข้าสู่ 2026Q2 ซึ่งเอาชนะเสียงรบกวนจากการออกหุ้นใดๆ
ฉันต้องการโต้แย้งกรอบความคิดของ ChatGPT ที่นี่ ChatGPT กล่าวว่า P/E ที่ 15.7 เท่า สะท้อนถึง 'กำไรที่สม่ำเสมอและผลตอบแทนที่ยืดหยุ่น' แต่นั่นคือการมองย้อนกลับ — มันสะท้อนถึงสิ่งที่ตลาด *ยินดีที่จะจ่าย* ไม่ใช่สิ่งที่กำไรสมเหตุสมผล คำถามที่แท้จริงคือ กำไรเหล่านั้นกำลังเร่งตัวขึ้นจริงหรือไม่ ดูข้อมูล: EPS TTM คือ 14.94 ดอลลาร์สหรัฐฯ แต่ฉันไม่เห็นการเติบโตของ EPS รายไตรมาสในพื้นฐานดิบที่คุณให้มา P/E ขยายตัวจาก 13.0 เป็น 15.7 ในขณะที่หุ้นปรับตัวขึ้น 12% ซึ่งหมายความว่าการขยายตัวของค่าหลายเท่าแซงหน้าการเติบโตของกำไร นั่นไม่ใช่การลงคะแนนความเชื่อมั่นในกำไรในอนาคต — นั่นคือตลาดที่วิ่งนำหน้าเรื่องราวที่ยังไม่ได้รับการพิสูจน์ จนกว่าฉันจะเห็นการเร่งตัวของ EPS ที่แท้จริง ไม่ใช่แค่การสนับสนุนค่าหลายเท่า ฉันยังคงระมัดระวัง
ฉันกำลังขยายกรอบเพื่อกล่าวถึงระบอบมหภาค โดยเฉพาะอย่างยิ่งผลกระทบจากการปรับเปลี่ยนนโยบายล่าสุดของธนาคารแห่งแคนาดา สมมติฐานการซื้อของ Grok สมมติว่าอัตราดอกเบี้ยที่สูงขึ้นเป็นเวลานาน แต่ตลาดได้คำนวณการเปลี่ยนแปลงไปสู่สภาพแวดล้อมอัตราดอกเบี้ยที่เป็นกลางภายในปี 2026 แล้ว การเปลี่ยนแปลงนี้จะบีบอัดอัตรากำไรสุทธิ ซึ่งเป็นเครื่องยนต์หลักสำหรับอัตรากำไรสุทธิ 26.26% ของ RBC ตัวชี้วัดนั้นแสดงถึงส่วนแบ่งรายได้ที่แท้จริงที่ RBC เก็บไว้หลังจากหักค่าใช้จ่ายทั้งหมด และมีความอ่อนไหวสูงต่อการราบเรียบของเส้นอัตราผลตอบแทน การพึ่งพารายได้จากอัตราดอกเบี้ยเป็นการเดิมพันที่อันตรายเมื่อธนาคารกลางกำลังดำเนินการอย่างแข็งขันเพื่อลดต้นทุนการกู้ยืม
ฉันคิดว่าการแกว่งตัวที่เหลืออยู่ครั้งใหญ่สำหรับ RBC ใน 2026Q2 อยู่เหนือตัวเลขรายไตรมาสของธนาคาร: ปัจจัยมหภาคและระบอบกฎระเบียบ Claude, Grok, Gemini เส้นทางอัตราดอกเบี้ยที่กำหนดโดยธนาคารแห่งแคนาดาและนโยบายเงินทุน/เงินปันผลของ OSFI เป็นคันโยกที่สามารถประเมินมูลค่า RBC ใหม่ได้โดยไม่ขึ้นกับ ROE หรืออัตรากำไร หาก BoC ยังคงอัตราดอกเบี้ยสูงเป็นเวลานานและหน่วยงานกำกับดูแลยังคงมีท่าทีเข้มงวดเกี่ยวกับเงินทุนและการจ่ายเงิน หุ้นอาจเคลื่อนไหวต่ำลงแม้จะมีกำไรที่สม่ำเสมอ เส้นทางอัตราดอกเบี้ยที่ชัดเจนและกฎที่คาดการณ์ได้อาจปลดล็อกการขยายตัวของค่าหลายเท่า
การคาดการณ์ราคา
| โมเดล | เป้าหมาย 3 เดือน | เป้าหมาย 6 เดือน | เหตุผล |
|---|---|---|---|
| Grok | $140.00 | $152.00 | ฉันคาดว่า RY จะปรับตัวขึ้นจาก NIM ที่ยืดหยุ่นจากการมีเสถียรภาพของอัตราดอกเบี้ย ซึ่งจะให้ผลตอบแทนแก่ ROE ระดับสูงสุดของธนาคาร เนื่องจากตลาดสินเชื่อของแคนาดาฟื้นตัว ตัวเร่งปฏิกิริยาสำคัญคือการประชุมนโยบายของธนาคารแห่งแคนาดาในวันที่ 3 กันยายน 2025 ซึ่งการคงอัตราดอกเบี้ยหรือการลดลงเล็กน้อยจะยืนยันอัตราดอกเบี้ยที่สูงขึ้นเป็นเวลานาน ซึ่งจะปลดล็อกการขยายตัวของ NIM เข้าสู่ Q4 ความเสี่ยงที่ใหญ่คือผลประกอบการ Q3 2025 ที่เปิดเผยการตั้งสำรองสินเชื่อที่สูงขึ้นจากการอ่อนแอของภาคอสังหาริมทรัพย์ ซึ่งจะบีบอัดอัตรากำไร ROE ที่ 15.4% หมายความว่า RY สร้างผลกำไรต่อดอลลาร์ส่วนของผู้ถือหุ้นที่แข็งแกร่งเมื่อเทียบกับคู่แข่ง ซึ่งสมเหตุสมผลกับการปรับ P/E ใหม่เป็น 17 เท่า จาก EPS 14.94 ดอลลาร์สหรัฐฯ สำหรับเป้าหมาย 152 ดอลลาร์สหรัฐฯ ของฉัน |
| Claude | $128.00 | $124.00 | สมมติฐานของฉันคือ RY ได้คำนวณการขยายตัวของค่าหลายเท่าที่ง่ายดายไว้แล้ว และ 6 เดือนข้างหน้าจะทดสอบว่ากำไรจะเร่งตัวขึ้นจริงหรือไม่ หรือตลาดจะประเมินมูลค่าใหม่ต่ำลงเนื่องจากความผิดหวังจากปัจจัยมหภาค ตัวเร่งปฏิกิริยาที่เป็นรูปธรรมที่อาจผลักดันให้เกิน 135 ดอลลาร์สหรัฐฯ คือการประกาศผลประกอบการ Q2 2026 ที่ดีกว่าคาด โดยมีการเติบโตของ EPS รายไตรมาสสูงกว่า 5% — ซึ่งจะยืนยันการปรับ P/E ใหม่จาก 13.0 เป็น 15.7 ความเสี่ยงที่เป็นรูปธรรมที่ทำลายสิ่งนี้คือวัฏจักรการลดอัตราดอกเบี้ยของธนาคารแห่งแคนาดาที่บีบอัดอัตรากำไรสุทธิให้ต่ำกว่า 25% ซึ่งเป็นเครื่องยนต์ของอัตรากำไร 26.3% ของ RY ในปัจจุบัน ที่ 15.7 เท่าของกำไรในอดีต ตลาดกำลังจ่ายในราคาที่เต็มที่สำหรับธนาคารในสภาพแวดล้อมอัตราดอกเบี้ยที่กำลังกลับสู่ภาวะปกติ เหลือช่องว่างเพียงเล็กน้อย ฉันเห็นการรวมตัวกันที่ 128 ดอลลาร์สหรัฐฯ ใน 3 เดือน จากนั้นค่อยๆ ลดลงไปที่ 124 ดอลลาร์สหรัฐฯ ใน 6 เดือน เนื่องจากความคาดหวังในการลดอัตราดอกเบี้ยทวีความรุนแรงขึ้นและการบีบอัดค่าหลายเท่ากลับมา |
| Gemini | $122.00 | $115.00 | สมมติฐานของฉันคือ RBC เผชิญกับการแก้ไขการประเมินมูลค่า เนื่องจากตลาดตระหนักว่าค่าหลายเท่าในปัจจุบันไม่ยั่งยืนในสภาพแวดล้อมอัตราดอกเบี้ยที่อ่อนตัวลง ตัวเร่งปฏิกิริยาสำคัญสำหรับการลดลงจะเป็นรายงานผลประกอบการ 2026Q3 ซึ่งฉันคาดว่าจะเห็นการบีบอัดอัตรากำไร เนื่องจากการลดอัตราดอกเบี้ยของธนาคารแห่งแคนาดาในที่สุดจะส่งผลกระทบต่อรายได้ดอกเบี้ยสุทธิ ในทางตรงกันข้าม การเพิ่มขึ้นอย่างไม่คาดคิดของอุปสงค์สินเชื่อภาคครัวเรือนของแคนาดาจะทำลายสมมติฐานขาลงของฉัน ปัจจุบันเรากำลังพิจารณา P/E ที่ 15.67 เท่า ซึ่งหมายความว่านักลงทุนกำลังจ่ายในราคาพรีเมียมสำหรับกำไรที่มีแนวโน้มว่าจะถึงจุดสูงสุดในวัฏจักรปัจจุบัน การประเมินมูลค่านี้สูงเกินไปสำหรับธนาคารที่กำลังเข้าสู่ช่วงของการหดตัวของอัตรากำไร |
| Chatgpt | $121.00 | $126.00 | ฉันคิดว่า RBC เสนอความสามารถในการทำกำไรที่ยั่งยืนพร้อมกับ upside ที่พอประมาณหากเส้นทางอัตราดอกเบี้ยยังคงเอื้ออำนวย ตัวเร่งปฏิกิริยาคือการตัดสินใจเรื่องอัตราดอกเบี้ยของธนาคารแห่งแคนาดาในอนาคตอันใกล้ ซึ่งส่งสัญญาณว่าอัตราดอกเบี้ยจะยังคงสูงขึ้นเป็นเวลานาน ซึ่งจะทำให้อัตรากำไรสุทธิมีสุขภาพดีและอาจเพิ่มค่าหลายเท่าของหุ้น ความเสี่ยงคือภาวะเศรษฐกิจถดถอยที่รุนแรงขึ้นหรือภาวะสินเชื่อที่นำโดยภาคอสังหาริมทรัพย์ซึ่งจะบีบอัดอัตรากำไรและ ROE ซึ่งอาจกระตุ้นให้เกิดการบีบอัดค่าหลายเท่า EPS TTM คือ 14.94 ดอลลาร์สหรัฐฯ ฐานกำไรนั้นสนับสนุนเงินปันผลที่สม่ำเสมอและทำให้หุ้นมีพื้นที่ในการปรับตัวสูงขึ้นหากความชัดเจนของอัตราดอกเบี้ยยังคงสนับสนุน |
ตัวชี้วัดของฉัน รายการเฝ้าดูส่วนตัวของคุณ — แถวที่เลือกจากข้อมูลพื้นฐานฉบับเต็ม
เลือกตัวชี้วัดที่สำคัญสำหรับคุณ — คลิกเครื่องหมาย + ถัดจากแถวใดก็ได้ใน Fundamentals ฉบับเต็มด้านบน
การเลือกของคุณถูกบันทึกและจะติดตามคุณไปในทุกสัญลักษณ์หุ้น