DASH DoorDash, Inc. - Common Stock
NASDAQ · Hotels, Restaurants & Leisure · Visualizza su SEC EDGAR ↗ chiudi Ott 2, 2026 10-K/10-Q Ago 5, 2026DASH Snapshot del titolo Prezzo, capitalizzazione di mercato, P/E, EPS, ROE, debito/capitale proprio, intervallo 52 settimane
DASH Grafico del prezzo delle azioni OHLCV giornaliero con indicatori tecnici — panoramica, zoom e personalizza la tua visualizzazione
La granularità delle barre si adatta al periodo selezionato — passa il mouse sul grafico per vedere apertura/massimo/minimo/chiusura di una barra.
Informazioni su DoorDash, Inc. - Common Stock Panoramica della società da Wikipedia
DoorDash, Inc. is an American company operating online food ordering and food delivery. It trades under the symbol DASH. With a 56% market share, DoorDash is the largest food delivery platform in the United States. It also has a 60% market share in the convenience delivery category. As of December 31, 2020, the platform was used by 450,000 merchants, 20 million consumers, and had over one million delivery couriers.
Founded by Tony Xu, Andy Fang, Stanley Tang and Evan Moore, DoorDash made its debut on the Fortune 500 list in 2024, ranking No. 443.
DoorDash has been sued for or held legally liable for withholding tips, reducing tip transparency, antitrust price manipulation, listing restaurants without permission, misclassifying workers, withholding sick time, and illegally selling personal data.
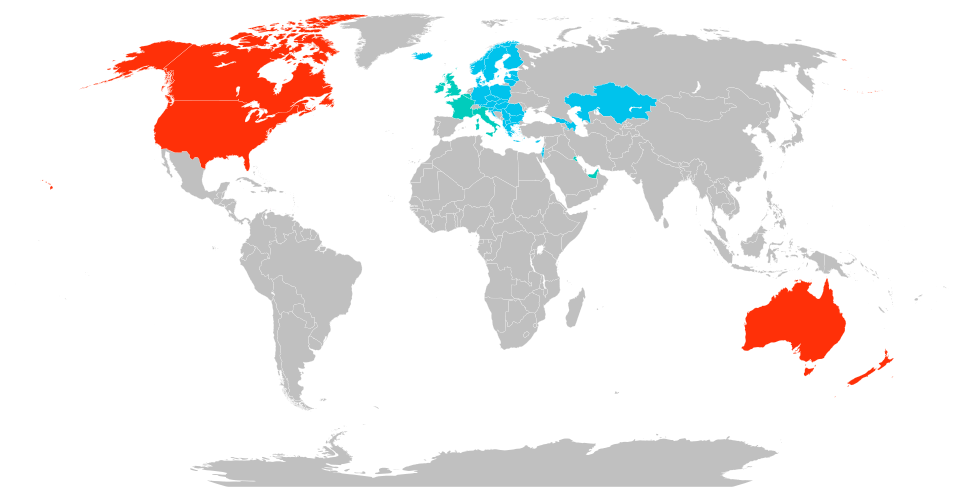
As of April 2026, DoorDash operates in the United States (including Puerto Rico), Canada, Mexico, and Australia. Through its subsidiaries Deliveroo and Wolt, the company also operates across Europe, as well as in Azerbaijan, Georgia, Israel, Kazakhstan, Kuwait, and the United Arab Emirates.
History
In January 2013, Stanford University students Tony Xu, Stanley Tang, Andy Fang and Evan Moore launched PaloAltoDelivery.com in Palo Alto, California. In the summer of 2013, it received US$120,000 in seed money from Y Combinator in exchange for a 7% stake. It incorporated as DoorDash in June 2013.
DoorDash's first partnership with a fast food burger restaurant chain was in April 2016, when it partnered with CKE Restaurants, parent company of Carl's Jr. and Hardee's, for food delivery.
In December 2017, DoorDash announced its partnership with Wendy's for delivery from its restaurants.
In December 2018, DoorDash overtook Uber Eats to hold the second position in total US food delivery sales, behind GrubHub. By March 2019, it had exceeded GrubHub in total sales, at 27.6% of the on-demand delivery market. By early 2019, DoorDash was the largest food delivery provider in the U.S., as measured by consumer spending.
In October 2019, DoorDash opened its first ghost kitchen, DoorDash Kitchen, in Redwood City, California, with four restaurants operating at the location.
By June 2020, DoorDash had raised more than $2.5 billion over several financing rounds from investors including Y Combinator, Charles River Ventures, SV Angel, Khosla Ventures, Sequoia Capital, SoftBank Group, GIC, and Kleiner Perkins. DoorDash announced a partnership with KFC in September 2020, followed by Taco Bell in October 2020.
In November 2020, DoorDash announced the opening of its first physical restaurant location, partnering up with Bay Area restaurant Burma Bites to offer delivery and pick-up orders. In December 2020, it became a public company via an initial public offering, raising $3.37 billion. In November 2021, DoorDash acquired Finland's Wolt for €7bn.
In August 2022, DoorDash announced it would end its partnership with Walmart in September, ending the companies' cooperation agreement from 2018. In November 2022, DoorDash announced plans to lay off 1,250 corporate employees, or about six percent of its workforce, to rein in expenses.
In June 2023, DoorDash announced it would give its drivers the option of earning an hourly minimum wage instead of being paid per delivery. However, drivers are only paid hourly when on an active delivery.
In September 2023, the company transferred its stock listing from the New York Stock Exchange to the Nasdaq. On December 18, 2023, DoorDash was added to the Nasdaq-100 index.
In March 2025, DoorDash announced a partnership with Klarna, a Buy Now, Pay Later (BNPL) service, letting customers schedule small payments over a set period of time. DoorDash received widespread criticism from this decision, including internet mockery, given concerns about the increase of household debt in America.
In 2025, DoorDash acquired the UK-based delivery service Deliveroo for $3.88 billion. The combined company operates in 40 countries and serves 50 million users monthly.
In September 2025, DoorDash and Ace Hardware (the largest hardware cooperative) announced their partnership to offer delivery for home use products from over 4,000 Ace locations.
In June 2026, the NJ Transit Meadowlands Line was renamed to the "Doordash Meadowlands Rail Line" through June 2027, as part of a new partnership with Doordash.
NYC Mayor Zohran Mamdani announced a record $131.5 million settlement with DoorDash on September 22, 2026, resolving what the city called systematic violations of its delivery worker laws that affected about 260,000 workers. DoorDash said the underpayment was a mistake, and it had also spent $1.4m last year trying to stop Mamdani from being elected.
Lawsuits against DoorDash
2017 class-action lawsuit for misclassifying workers
In 2017, a class-action lawsuit was filed against DoorDash for allegedly misclassifying delivery drivers in California and Massachusetts as independent contractors. In 2022, a tentative settlement was reached in which DoorDash would pay $100 million total, with $61 million going to over 900,000 drivers, paying out just over $130 per driver, and $28 million for the lawyers. Gizmodo criticized the settlement, noting that the $413 million that DoorDash CEO Tony Xu received the previous year was one of the largest CEO compensation packages of all time.
2019 data breach lawsuit
On May 4, 2019, DoorDash confirmed 4.9 million customers, delivery workers and merchants had sensitive information stolen via a data breach. Those who joined the platform after April 5, 2018, were unaffected by the breach. A class-action lawsuit for the breach was filed against DoorDash in October 2019.
Withholding of tips and subsequent class-action lawsuits
In July 2019, the company's tipping policy was criticized by The New York Times, and later The Verge and Vox and Gothamist. Drivers receive a guaranteed minimum per order that is paid by DoorDash by default. When a customer added a tip, instead of going directly to the driver, it first went to the company to cover the guaranteed minimum. Drivers then only directly received the part of the tip that exceeded the guaranteed minimum per order.
In January 2020, it was reported that DoorDash had lied about skimming tips from its drivers, causing them to earn an average of $1.45 an hour after expenses, and that after the company had allegedly overhauled its tipping system, DoorDash was still manipulating per-delivery payouts at the expense of drivers.
A DoorDash customer filed a class action lawsuit against the company for its "materially false and misleading" tipping policy. The case was referred to arbitration in August 2020. Under pressure, the company revised its policy. The company settled a lawsuit with District of Columbia Attorney General Karl Racine for $2.5 million, with funds going to deliverers, the government, and to charity.
2021 driver strike for tip transparency
In July 2021, DoorDash drivers went on strike to protest lack of tip transparency and to ask for higher pay. At the time of the strike, and, as of June 2022, DoorDash did not allow drivers to see the full tip amounts prior to accepting a delivery in the app. If customers tip over a set amount for the order total, Doordash hides a portion of the tip until the delivery is complete. The strike occurred after DoorDash rewrote its code to cut off access to Para, a third-party app that drivers had been using to see the full tip amounts.
2025 class-action lawsuit settlement
In 2025, DoorDash agreed to pay around $17 million for "misleading both consumers and delivery workers" with tips being docked from drivers' pay instead of directly going to drivers.
2020 antitrust litigation
In April 2020, in the case of Davitashvili v. GrubHub Inc. DoorDash, Grubhub, Postmates, and Uber Eats were accused of monopolistic power by only listing restaurants on its apps if the restaurant owners signed contracts which include clauses that require prices be the same for dine-in customers as for customers receiving delivery. The plaintiffs stated that this arrangement increases the cost for dine-in customers, as they are required to subsidize the cost of delivery; and that the apps charge "exorbitant" fees, which range from 13% to 40% of revenue, while the average restaurant's profit ranges from 3% to 9% of revenue. The lawsuit seeks treble damages, including for overcharges, since April 14, 2016, for dine-in and delivery customers in the United States at restaurants using the defendants' delivery apps. Although several preliminary documents in the case have now been filed, a trial date has not yet been set.
Litigation for illegal unauthorized restaurant listing
In May 2021, DoorDash was criticized for unauthorized listings of restaurants who had not given permission to appear on the app. The company was sued by Lona's Lil Eats in St. Louis, with the lawsuit claiming that DoorDash had listed them without permission, then prevented any orders to the restaurant from going through and redirecting customers to other restaurants instead, because Lona's was "too far away," when in reality it had not paid DoorDash a fee for listing. This aspect of DoorDash's business practice is illegal in California.
2021 lawsuit by the city of Chicago
In August 2021, the city of Chicago sued DoorDash and GrubHub. According to Chicago mayor Lori Lightfoot, the companies broke the law by using "unfair and deceptive tactics to take advantage of restaurants and consumers who were struggling to stay afloat during the COVID-19 pandemic." DoorDash and GrubHub denied the suit's merits.
2023 class-action lawsuit
DoorDash has been accused of charging users of iPhone more than users on the Android platform. User testing claimed to show several instances of various fees and delivery charges being higher when using an Apple device. DoorDash denied these allegations in response to the ongoing US$1 billion class-action suit.
2023 lawsuit by the city of Seattle
In August 2023, DoorDash was obligated to pay its drivers and the city of Seattle a total of $1.6 million. It was found that the platform made it difficult for users to request paid time off. DoorDash is to pay $1.1 million towards safe and sick time credits, $500k directly to drivers and an additional $8,500 in city fees.
2024 privacy lawsuit by the state of California
In February 2024, after being found to have illegally sold personal data, DoorDash was obligated to pay a $375,000 civil penalty as well as to begin complying with privacy laws it had been shirking, namely CCPA and CalOPPA.
Markets
DoorDash began expanding into international markets in 2015, launching in Toronto, Canada. The company started operating in markets outside North America in 2019, officially launching in Melbourne, Australia, in September and later expanding further into the country. In 2021, the company expanded its service area to Sendai, Japan in June and Stuttgart, Germany, in November. In June 2022, the company expanded into the Wellington Region of New Zealand.
The company expanded its service offerings in 2020, adding grocery delivery initially in California and the Midwest in August 2020. DoorDash expanded the service offerings in 2021 to include DoubleDash, which allows for orders from multiple merchants, and alcohol delivery in 20 U.S. states, Washington, D.C., Canada, and Australia.
Acquisitions
In August 2019, the company acquired Scotty Labs, a tele-operations startup company that focuses on self-driving and remote-controlled vehicle technology. In October 2019, DoorDash acquired Caviar, a service specializing in food delivery from upscale urban-area restaurants that typically do not offer delivery, from Square, Inc. for $410 million. On February 8, 2021, DoorDash announced its acquisition of Chowbotics, a robotics company known for its salad-making robot. The companies did not disclose the terms of the deal, but Chowbotics was valued at $46 million in 2018. On November 9, 2021, DoorDash announced its acquisition of the Finnish technology company Wolt for over $8.1 billion. In March 2022, DoorDash announced its acquisition of Bbot, startup that developed digital ordering and payment solutions for restaurants and hospitality venues.
In April 2025, the company made an initial offer to acquire Deliveroo, a UK-based food delivery company, for £2.7 billion($3.6 billion). In May 2025, DoorDash announced it had acquired Deliveroo for $3.9 billion. In May 2025, DoorDash announced the $1.2 billion all-cash acquisition of restaurant booking platform SevenRooms.
Philanthropy
In 2018, DoorDash launched Project DASH, a partnership with local food security organizations to deliver donations to those in need. By August 2019, the program had expanded to 25 cities in the United States and Canada and had delivered more than one million pounds of food. As of September 2021, Project DASH operated in more than 900 cities and had delivered more than 15 million meals.
DoorDash partnered with the National Urban League in 2020 as part of its Main Street Strong program, pledging $200 million over five years to support restaurants and drivers during the COVID-19 pandemic, $12 million of which was allotted to assisting drivers of color in building job skills and financial literacy.
In 2022, DoorDash partnered with Meals on Wheels to help deliver food to senior citizens.
== Business trend ==
Fonte: Wikipedia (Inglese), CC BY-SA 4.0 · Vedi su Wikipedia ↗
Performance decennale Andamento di ricavi, utile netto, margini e EPS
Valutazione Rapporti P/E, P/S, P/B, EV/EBITDA — il titolo è costoso o economico?
| Metrica | Tendenza 5 anni | DASH | media 5 anni | Mediana dei peer | Verdetto |
|---|---|---|---|---|---|
| P/E (TTM) | 98.5media 5 anni ≈98.9 | ≈98.9 | 26.4 | Sopravvalutato | |
| P/S (TTM) | 5.2media 5 anni ≈6.2 | ≈6.2 | 2.4 | Sopravvalutato | |
| P/B (MRQ) | 8.3media 5 anni ≈7.2 | ≈7.2 | 8.1 | Valore equo | |
| Prezzo / FCF (TTM) | 31.6media 5 anni ≈63.0 | ≈63.0 | · | · | |
| Prezzo / Flusso di cassa (TTM) | 29.0media 5 anni ≈45.9 | ≈45.9 | 16.6 | Sopravvalutato | |
| Prezzo / Valore contabile tangibile (MRQ) | 10.4media 5 anni ≈17.2 | ≈17.2 | · | · |
La mediana dei peer viene calcolata su base standardizzata per metrica e potrebbe non corrispondere sempre alla base TTM/MRQ mostrata per questo titolo.
Redditività Margini lordi, operativi e netti; ROE, ROA, ROIC
| Metrica | Tendenza 5 anni | DASH | media 5 anni | Mediana dei peer | Verdetto |
|---|---|---|---|---|---|
| Margine Operativo (TTM) | 4.5%media 5 anni ≈-5.6% | ≈-5.6% | 13.8% | Debole | |
| Margine EBITDA (TTM) | 10.8%media 5 anni ≈-0.55% | ≈-0.55% | 17.4% | Debole | |
| Margine ante imposte (TTM) | 5.5%media 5 anni ≈-5.7% | ≈-5.7% | 14.7% | Debole | |
| Margine di Profitto Netto (TTM) | 5.3%media 5 anni ≈-5.8% | ≈-5.8% | 11.3% | Debole | |
| ROA (TTM) | 4.6%media 5 anni ≈-7.0% | ≈-7.0% | 10.9% | Debole | |
| ROE (TTM) | 8.9%media 5 anni ≈-9.2% | ≈-9.2% | 10.2% | In linea |
Salute finanziaria Debito, liquidità, solvibilità — solidità del bilancio
| Metrica | Tendenza 5 anni | DASH | media 5 anni | Mediana dei peer | Verdetto |
|---|---|---|---|---|---|
| Rapporto corrente (MRQ) | 1.4media 5 anni ≈1.9 | ≈1.9 | 0.9 | Liquidità elevata |
Crescita Crescita di ricavi, EPS e utile netto: YoY, CAGR 3Y, CAGR 5Y
| Metrica | Tendenza 5 anni | DASH | media 5 anni | Mediana dei peer | Verdetto |
|---|---|---|---|---|---|
| Revenue YoY (Ricavi YoY) | 27.9%media 5 anni ≈37.5% | ≈37.5% | · | · | |
| Revenue CAGR 3Y (CAGR Ricavi 3Y) | 27.7%media 5 anni ≈33.9% | ≈33.9% | · | · | |
| Revenue CAGR 5Y (CAGR Ricavi 5Y) | 36.6% | · | · | · | |
| EPS YoY | 634.5% | · | · | · | |
| Net Income YoY (Utile Netto YoY) | 660.2% | · | · | · |
Efficienza del Capitale Rotazione delle attività, rotazione delle scorte, rotazione dei crediti
| Metrica | Tendenza 5 anni | DASH | media 5 anni | Mediana dei peer | Verdetto |
|---|---|---|---|---|---|
| Revenue / Employee (Ricavi / Dipendente) | ≈$436.8K | · | · | · |
valore · ≈ media 5 anni · mediana del settore · giudizio rispetto alla mediana
Cronologia utili EPS effettivo vs stima, surprise %, tasso di superamento, data prossimi utili
| Periodo | Rapporto | EPS Actual | EPS Stimato | Sorpresa |
|---|---|---|---|---|
| 30 Giugno 2026 | Ago 4, 2026 | $0.46 | $0.47 | -1.2% |
| 31 Marzo 2026 | $0.42 | $0.37 | 13.0% | |
| 31 Dicembre 2025 | $0.48 | $0.60 | -19.7% | |
| 30 Settembre 2025 | $0.55 | $0.70 | -22.0% | |
| 30 Giugno 2025 | $0.65 | $0.45 | 44.8% | |
| 31 Marzo 2025 | $0.44 | $0.40 | 10.8% |
Fondamentali Completi Tutte le metriche per anno — conto economico, stato patrimoniale, rendiconto finanziario
Conto Economico
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Revenue | $13.72B | $10.72B | $8.63B | $6.58B | $4.89B | $2.89B | $885M | |
| R&D Expense | $1.43B | $1.17B | $1.00B | $829M | $430M | $321M | $107M | |
| SG&A Expense | $1.60B | $1.45B | $1.24B | $1.15B | $797M | $556M | $245M | |
| Operating Expenses | $12.99B | $10.76B | $9.21B | $7.71B | $5.34B | $3.32B | $1.50B | |
| Operating Income | $723M | $-38M | $-579M | $-1.12B | $-452M | $-436M | $-616M | |
| Interest Expense | · | · | · | $2M | $14M | $32M | $0 | |
| Other Non-op | $5M | $-5M | $-107M | $-305M | $0 | $3M | $-68M | |
| Pretax Income | $939M | $156M | $-534M | $-1.40B | $-463M | $-458M | $-666M | |
| Income Tax | $7M | $39M | $31M | $-31M | $5M | $3M | $1M | |
| Net Income | $935M | $123M | $-558M | $-1.36B | $-468M | $-461M | $-667M | |
| EPS (Basic) | $2.19 | $0.30 | $-1.42 | $-3.68 | $-1.39 | $-7.39 | $-15.44 | |
| EPS (Diluted) | $2.13 | $0.29 | $-1.42 | $-3.68 | $-1.39 | $-7.39 | $-15.44 | |
| Shares (Basic) | 427,043,000 | 411,551,000 | 392,948,000 | 371,413,000 | 336,847,000 | 62,390,000 | 43,252,000 | |
| Shares (Diluted) | 439,686,000 | 430,242,000 | 392,948,000 | 371,413,000 | 336,847,000 | 62,390,000 | 43,252,000 | |
| EBITDA | $1.47B | $523M | $-70M | $-755M | $-296M | $-316M | · |
Stato Patrimoniale
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $4.38B | $4.02B | $2.66B | $1.98B | $2.50B | $4.34B | $257M | |
| Receivables | $1.11B | $732M | $533M | $400M | $349M | $291M | $58M | |
| Prepaid Expense | $1.17B | $687M | $525M | $358M | $139M | $221M | $125M | |
| Other Current Assets | $397M | $253M | $146M | · | · | · | · | |
| Current Assets | $8.64B | $7.39B | $5.60B | $4.72B | $4.57B | $5.52B | $998M | |
| Goodwill | $5.52B | $2.31B | $2.43B | $2.37B | $316M | $316M | $306M | |
| Intangibles | $2.26B | $510M | $659M | $765M | $61M | $74M | $103M | |
| Other Non-current Assets | $896M | $632M | $420M | $129M | $68M | $33M | $28M | |
| Total Assets | $19.66B | $12.85B | $10.84B | $9.79B | $6.81B | $6.35B | $1.73B | |
| Accounts Payable | $397M | $321M | $216M | $157M | $161M | $80M | $20M | |
| Accrued Liabilities | $5.64B | $4.05B | $3.13B | $2.33B | $1.57B | $943M | $345M | |
| Current Liabilities | $6.15B | $4.44B | $3.41B | $2.54B | $1.76B | $1.40B | $382M | |
| Capital Leases | $461M | $468M | $454M | $456M | $373M | $238M | $167M | |
| Other Non-current Liabilities | $281M | $129M | $162M | $21M | $9M | $13M | $1M | |
| Total Liabilities | $9.61B | $5.04B | $4.03B | $3.02B | $2.14B | $1.65B | $550M | |
| Common Stock | $0 | $0 | $0 | $0 | $0 | $0 | $0 | |
| Paid-in Capital | $14.09B | $13.16B | $11.89B | $10.63B | $6.75B | $6.31B | $70M | |
| Retained Earnings | $-4.32B | $-5.25B | $-5.15B | $-3.85B | $-2.08B | $-1.61B | $-1.15B | |
| AOCI | $261M | $-107M | $73M | $-33M | $-4M | $0 | · | |
| Stockholders' Equity | $10.03B | $7.80B | $6.81B | $6.75B | $4.67B | $4.70B | $-1.08B | |
| Liabilities + Equity | $19.66B | $12.85B | $10.84B | $9.79B | $6.81B | $6.35B | $1.73B | |
| Shares Outstanding | 434,247,000 | 419,677,000 | 403,228,000 | 391,471,000 | 346,512,000 | 318,503,000 | 43,937,000 |
Flusso di cassa
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| D&A | $747M | $561M | $509M | $369M | $156M | $120M | $32M | |
| Stock-based Comp | $1.05B | $1.10B | $1.09B | $889M | $486M | $322M | $18M | |
| Deferred Tax | $-37M | $1M | $-1M | $-35M | $1M | $0 | · | |
| Amort. of Intangibles | $212M | $125M | $127M | $99M | $13M | $51M | $7M | |
| Restructuring | $2M | $0 | $2M | $92M | $0 | $0 | · | |
| Other Non-cash | $-265M | $348M | $635M | $509M | $518M | $271M | · | |
| Operating Cash Flow | $2.43B | $2.13B | $1.67B | $367M | $692M | $252M | $-467M | |
| CapEx | $257M | $104M | $123M | $176M | $129M | $106M | $78M | |
| Investing Cash Flow | $-4.39B | $-444M | $-342M | $-300M | $-2.05B | $-192M | $-570M | |
| Stock Repurchased | $0 | $224M | $750M | $400M | $0 | $0 | $0 | |
| Net Stock Activity | $0 | $-224M | $-750M | $-400M | · | $0 | · | |
| Financing Cash Flow | $2.36B | $-204M | $-752M | $-375M | $-483M | $4.00B | $1.11B | |
| Net Change in Cash | $460M | $1.45B | $584M | $-318M | $-1.84B | $4.06B | $72M | |
| Free Cash Flow | $2.17B | $2.03B | $1.55B | $191M | $563M | $146M | · | |
| Levered FCF | · | · | · | $189M | $549M | $114M | · |
Redditività
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Operating Margin | 5.3% | -0.35% | -6.7% | -17.1% | -9.2% | -15.1% | · | |
| Net Margin | 6.8% | 1.1% | -6.5% | -20.7% | -9.6% | -16.0% | · | |
| Pretax Margin | 6.9% | 1.5% | -6.2% | -21.2% | -9.5% | -15.9% | · | |
| EBITDA Margin | 10.7% | 4.9% | -0.81% | -11.5% | -6.1% | -10.9% | · | |
| ROA | · | 1.0% | -5.4% | -16.4% | -7.1% | -11.4% | · | |
| ROE | · | 1.6% | -8.3% | -20.1% | -10.0% | -26.4% | · | |
| ROIC | · | -0.37% | -9.0% | -16.3% | -9.8% | -9.3% | · |
Liquidità e Solvibilità
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Current Ratio | · | 1.7 | 1.6 | 1.9 | 2.6 | 3.9 | · | |
| Quick Ratio | · | 1.1 | 0.9 | 0.9 | 1.6 | 3.3 | · | |
| Interest Coverage | · | · | · | -562.0 | -32.3 | -13.6 | · |
Efficienza
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Asset Turnover | · | 0.9 | 0.8 | 0.8 | 0.7 | 0.7 | · | |
| Receivables Turnover | · | 17.0 | 18.5 | 17.6 | 15.3 | 16.5 | · |
Per Azione
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Book Value / Share | · | $18.59 | $16.88 | $17.25 | $13.47 | $14.76 | · | |
| Revenue / Share | $31.20 | $24.92 | $21.97 | $17.72 | $14.51 | · | · | |
| Cash Flow / Share | $5.53 | $4.96 | $4.26 | $0.99 | $2.05 | · | · | |
| Cash / Share | · | $9.58 | $6.59 | $5.05 | $7.23 | $13.64 | · | |
| EPS (TTM) | $2.13 | $0.29 | $-1.42 | $-3.68 | $-1.39 | $-7.39 | · |
Tassi di Crescita
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Revenue YoY | 27.9% | 24.2% | 31.2% | 34.7% | 69.4% | · | · | |
| Revenue CAGR 3Y | 27.7% | 29.9% | 44.1% | · | · | · | · | |
| Revenue CAGR 5Y | 36.6% | · | · | · | · | · | · | |
| EPS YoY | 634.5% | · | · | · | · | · | · | |
| Net Income YoY | 660.2% | · | · | · | · | · | · |
Valutazione (TTM)
| Metrica | Tendenza | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 |
|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $13.72B | $10.72B | $8.63B | $6.58B | $4.89B | $2.89B | · | |
| Net Income TTM | $935M | $123M | $-558M | $-1.36B | $-468M | $-461M | · | |
| Market Cap | · | $70.40B | $39.88B | $19.11B | $51.60B | $45.47B | · | |
| P/E | 106.3 | 578.4 | -69.6 | -13.3 | -107.1 | -19.3 | · | |
| P/S | · | 6.6 | 4.6 | 2.9 | 10.6 | 15.8 | · | |
| P/B | · | 9.0 | 5.9 | 2.8 | 11.1 | 9.7 | · | |
| P / Tangible Book | 43.6 | 14.1 | 10.7 | 5.3 | 12.0 | 10.5 | · | |
| P / Cash Flow | · | 33.0 | 23.8 | 52.1 | 74.6 | 180.4 | · | |
| P / FCF | · | 34.7 | 25.7 | 100.1 | 91.6 | 311.4 | · | |
| Earnings Yield | 0.94% | 0.17% | -1.4% | -7.5% | -0.93% | -5.2% | · |
Conto Economico
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $4.45B | $4.04B | $3.96B | $3.45B | $3.28B | $3.03B | $2.87B | $2.71B | $2.63B | $2.51B | $2.30B | $2.16B | $2.13B | $2.04B | $1.82B | $1.70B | |
| R&D Expense | $535M | $398M | $419M | $355M | $351M | $306M | $297M | $289M | $303M | $279M | $253M | $250M | $269M | $231M | $250M | $226M | |
| SG&A Expense | $538M | $432M | $480M | $400M | $388M | $332M | $324M | $315M | $494M | $319M | $320M | $289M | $341M | $285M | $300M | $311M | |
| Operating Expenses | $4.30B | $3.88B | $3.81B | $3.19B | $3.12B | $2.88B | $2.76B | $2.60B | $2.83B | $2.57B | $2.39B | $2.27B | $2.34B | $2.21B | $2.19B | $2.01B | |
| Operating Income | $156M | $151M | $147M | $258M | $163M | $155M | $117M | $107M | $-201M | $-61M | $-89M | $-108M | $-211M | $-171M | $-370M | $-308M | |
| Interest Expense | · | · | · | · | · | · | · | · | · | · | · | · | · | $1M | · | $0 | |
| Other Non-op | $16M | $6M | $33M | $-81M | $59M | $-6M | $8M | $-6M | $-5M | $-2M | $-101M | $-1M | $-4M | $-1M | $-305M | $-2M | |
| Pretax Income | $207M | $191M | $222M | $248M | $271M | $198M | $176M | $155M | $-157M | $-18M | $-139M | $-69M | $-181M | $-145M | $-659M | $-301M | |
| Income Tax | $8M | $8M | $9M | $5M | $-13M | $6M | $37M | $-6M | $1M | $7M | $17M | $6M | $-9M | $17M | $-17M | $-5M | |
| Net Income | $200M | $184M | $213M | $244M | $285M | $193M | $141M | $162M | $-157M | $-23M | $-154M | $-73M | $-170M | $-161M | $-640M | $-295M | |
| EPS (Basic) | $0.46 | $0.42 | $0.49 | $0.57 | $0.67 | $0.46 | $0.35 | $0.39 | $-0.38 | $-0.06 | $-0.38 | $-0.19 | $-0.44 | $-0.41 | $-1.71 | $-0.77 | |
| EPS (Diluted) | $0.46 | $0.42 | $0.49 | $0.55 | $0.65 | $0.44 | $0.35 | $0.38 | $-0.38 | $-0.06 | $-0.38 | $-0.19 | $-0.44 | $-0.41 | $-1.71 | $-0.77 | |
| Shares (Basic) | 434,425,000 | 435,429,000 | · | 428,911,000 | 425,113,000 | 421,422,000 | · | 413,106,000 | 410,482,000 | 405,482,000 | · | 393,217,000 | 388,737,000 | 390,397,000 | · | 384,756,000 | |
| Shares (Diluted) | 439,345,000 | 442,326,000 | · | 441,812,000 | 438,377,000 | 435,563,000 | · | 427,962,000 | 410,482,000 | 405,482,000 | · | 393,217,000 | 388,737,000 | 390,397,000 | · | 384,756,000 | |
| EBITDA | $451M | $420M | · | $427M | $322M | $307M | · | $245M | $-61M | $81M | · | $20M | $-83M | $-48M | · | $-190M |
Stato Patrimoniale
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $4.42B | $4.58B | $4.38B | $3.28B | $3.91B | $4.50B | $4.02B | $3.66B | $3.43B | $3.12B | $2.66B | $2.34B | $1.90B | $1.83B | $1.98B | $2.32B | |
| Receivables | $1.10B | $1.03B | $1.11B | $894M | $840M | $782M | $732M | $622M | $585M | $546M | · | $417M | $383M | $382M | · | $325M | |
| Prepaid Expense | $1.15B | $1.12B | $1.17B | $899M | $824M | $730M | $687M | $839M | $782M | $700M | · | $519M | $469M | $509M | · | $302M | |
| Other Current Assets | $440M | $425M | $397M | $362M | $386M | $295M | $253M | · | · | · | · | · | · | · | · | · | |
| Current Assets | $8.42B | $8.59B | $8.64B | $10.49B | $9.73B | $7.85B | $7.39B | $6.76B | $6.62B | $6.13B | · | $5.14B | $4.61B | $4.59B | · | $4.69B | |
| Goodwill | $5.50B | $5.50B | $5.52B | $3.57B | $3.53B | $2.41B | $2.31B | $2.46B | $2.37B | $2.39B | $2.43B | $2.35B | $2.40B | $2.40B | $2.37B | $2.20B | |
| Intangibles | $2.00B | $2.12B | $2.26B | $878M | $890M | $504M | $510M | $577M | $586M | $621M | · | $663M | $708M | $743M | · | $735M | |
| Other Non-current Assets | $1.08B | $1.07B | $896M | $809M | $774M | $731M | $632M | $519M | $458M | $456M | · | $140M | $131M | $126M | · | $125M | |
| Total Assets | $19.56B | $19.71B | $19.66B | $17.97B | $16.95B | $13.57B | $12.85B | $12.28B | $11.84B | $11.45B | · | $10.01B | $9.60B | $9.65B | · | $9.55B | |
| Accounts Payable | $301M | $268M | $397M | $257M | $345M | $329M | $321M | $191M | $163M | $203M | · | $149M | $173M | $208M | · | $238M | |
| Accrued Liabilities | $5.75B | $5.65B | $5.64B | $4.79B | $4.27B | $4.18B | $4.05B | $3.84B | $3.80B | $3.48B | · | $2.77B | $2.50B | $2.39B | · | $1.93B | |
| Current Liabilities | $6.15B | $6.03B | $6.15B | $5.13B | $4.70B | $4.58B | $4.44B | $4.09B | $4.03B | $3.74B | · | $2.99B | $2.73B | $2.65B | · | $2.22B | |
| Capital Leases | $474M | $457M | $461M | $454M | $452M | $457M | $468M | $466M | $470M | $483M | · | $430M | $440M | $437M | · | $460M | |
| Other Non-current Liabilities | $276M | $293M | $281M | $155M | $153M | $143M | $129M | $139M | $167M | $214M | · | $29M | $28M | $27M | · | $35M | |
| Total Liabilities | $9.63B | $9.50B | $9.61B | $8.46B | $8.02B | $5.18B | $5.04B | $4.70B | $4.67B | $4.44B | · | $3.44B | $3.19B | $3.12B | · | $2.71B | |
| Common Stock | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $0 | · | $0 | $0 | $0 | · | $0 | |
| Paid-in Capital | $14.81B | $14.38B | $14.09B | $13.76B | $13.44B | $13.44B | $13.16B | $12.84B | $12.52B | $12.18B | · | $11.58B | $11.26B | $10.90B | · | $10.32B | |
| Retained Earnings | $-4.99B | $-4.30B | $-4.32B | $-4.53B | $-4.78B | $-5.06B | $-5.25B | $-5.40B | $-5.34B | $-5.18B | · | $-4.95B | $-4.87B | $-4.40B | · | $-3.21B | |
| Treasury Stock | · | $162M | · | · | · | · | · | · | · | · | · | · | · | · | · | · | |
| AOCI | $101M | $117M | $261M | $268M | $261M | $7M | $-107M | $122M | $-25M | $-1M | · | $-68M | $9M | $18M | · | $-292M | |
| Stockholders' Equity | $9.92B | $10.20B | $10.03B | $9.49B | $8.92B | $8.39B | $7.80B | $7.57B | $7.16B | $7.00B | $6.81B | $6.56B | $6.40B | $6.52B | $6.75B | $6.83B | |
| Liabilities + Equity | $19.56B | $19.71B | $19.66B | $17.97B | $16.95B | $13.57B | $12.85B | $12.28B | $11.84B | $11.45B | · | $10.01B | $9.60B | $9.65B | · | $9.55B | |
| Shares Outstanding | 433,256,000 | 435,955,000 | 434,247,000 | 430,907,000 | 426,915,000 | 423,627,000 | 419,677,000 | 415,162,000 | 413,140,000 | 408,512,000 | 403,228,000 | 398,386,000 | 392,652,000 | 389,756,000 | 391,471,000 | 388,137,000 |
Flusso di cassa
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $295M | $269M | $267M | $169M | $159M | $152M | $141M | $138M | $140M | $142M | $130M | $128M | $128M | $123M | $111M | $118M | |
| Stock-based Comp | $349M | $231M | $276M | $258M | $282M | $235M | $271M | $274M | $302M | $252M | $269M | $278M | $311M | $230M | $280M | $249M | |
| Amort. of Intangibles | $114M | $114M | $113M | $36M | $32M | $31M | $31M | $32M | $31M | $31M | $30M | $30M | $34M | $33M | $32M | $45M | |
| Restructuring | $2M | $48M | $0 | $1M | $0 | $1M | $0 | $0 | $0 | $0 | $0 | $0 | $0 | $2M | $84M | $5M | |
| Other Non-cash | · | $-90M | · | · | · | $55M | · | · | · | $182M | · | · | · | $205M | · | · | |
| Operating Cash Flow | $944M | $594M | $421M | $871M | $504M | $635M | $518M | $531M | $530M | $553M | $485M | $398M | $393M | $397M | $23M | $199M | |
| CapEx | $61M | $57M | $54M | $63M | $66M | $74M | $32M | $32M | $23M | $17M | $29M | $28M | $27M | $39M | $45M | $54M | |
| Investing Cash Flow | $-188M | $-98M | $-3.12B | $-173M | $-941M | $-160M | $-163M | $-62M | $-147M | $-72M | $-119M | $-78M | $-135M | $-10M | $-181M | $-199M | |
| Stock Repurchased | $887M | $162M | $0 | $0 | $0 | $0 | $0 | $217M | $7M | $0 | $51M | $6M | $301M | $392M | $0 | $400M | |
| Net Stock Activity | · | $-162M | · | · | · | · | · | · | · | $0 | · | · | · | $-392M | · | · | |
| Financing Cash Flow | $-896M | $-173M | $-19M | $1M | $2.38B | $3M | $7M | $-213M | $-5M | $7M | $-50M | $-4M | $-308M | $-390M | $1M | $-384M | |
| Net Change in Cash | $-136M | $301M | $-2.72B | $699M | $1.99B | $493M | $323M | $278M | $373M | $475M | $337M | $302M | $-53M | $-2M | $-139M | $-404M | |
| Free Cash Flow | · | $537M | · | · | · | $561M | · | · | · | $536M | · | · | · | $358M | · | · | |
| Levered FCF | · | · | · | · | · | · | · | · | · | · | · | · | · | $357M | · | · |
Redditività
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | 3.5% | 3.7% | · | 7.5% | 5.0% | 5.1% | · | 4.0% | -7.6% | -2.4% | · | -5.0% | -9.9% | -8.4% | · | -18.1% | |
| Net Margin | 4.5% | 4.6% | · | 7.1% | 8.7% | 6.4% | · | 6.0% | -6.0% | -0.92% | · | -3.4% | -8.0% | -7.9% | · | -17.3% | |
| Pretax Margin | 4.7% | 4.7% | · | 7.2% | 8.2% | 6.5% | · | 5.7% | -6.0% | -0.72% | · | -3.2% | -8.5% | -7.1% | · | -17.7% | |
| EBITDA Margin | 10.1% | 10.4% | · | 12.4% | 9.8% | 10.1% | · | 9.0% | -2.3% | 3.2% | · | 0.92% | -3.9% | -2.4% | · | -11.2% | |
| ROA | 1.1% | 1.1% | · | 1.6% | 2.0% | 1.5% | · | 1.5% | -1.5% | -0.22% | · | -0.75% | -1.7% | -2.0% | · | -3.7% | |
| ROE | 2.1% | 2.0% | · | 2.9% | 3.5% | 2.5% | · | 2.3% | -2.3% | -0.34% | · | -1.1% | -2.5% | -2.9% | · | -5.1% | |
| ROIC | 1.5% | 1.4% | · | 2.7% | 1.9% | 1.8% | · | 1.5% | -2.8% | -1.2% | · | -1.8% | -3.1% | -2.9% | · | -4.4% |
Liquidità e Solvibilità
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.4 | 1.4 | · | 2.0 | 2.1 | 1.7 | · | 1.7 | 1.6 | 1.6 | · | 1.7 | 1.7 | 1.7 | · | 2.1 | |
| Quick Ratio | 0.9 | 0.9 | · | 0.8 | 1.0 | 1.2 | · | 1.0 | 1.0 | 1.0 | · | 0.9 | 0.8 | 0.8 | · | 1.2 | |
| Interest Coverage | · | · | · | · | · | · | · | · | · | · | · | · | · | -171.0 | · | · |
Efficienza
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | 0.2 | 0.2 | · | 0.2 | |
| Receivables Turnover | 4.6 | 4.4 | · | 4.5 | 4.6 | 4.6 | · | 5.2 | 5.4 | 5.4 | · | 5.8 | 5.9 | 5.8 | · | 5.6 |
Per Azione
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $22.90 | $23.39 | · | $22.03 | $20.90 | $19.80 | · | $18.23 | $17.34 | $17.13 | · | $16.46 | $16.29 | $16.72 | · | $17.58 | |
| Revenue / Share | $10.14 | $9.12 | · | $7.80 | $7.49 | $6.96 | · | $6.32 | $6.41 | $6.20 | · | $5.50 | $5.49 | $5.21 | · | $4.42 | |
| Cash Flow / Share | · | $1.34 | · | · | · | $1.46 | · | · | · | $1.36 | · | · | · | $1.02 | · | · | |
| Cash / Share | $10.21 | $10.49 | · | $7.61 | $9.16 | $10.62 | · | $8.83 | $8.30 | $7.65 | · | $5.88 | $4.85 | $4.70 | · | $5.98 | |
| EPS (TTM) | $1.92 | $2.11 | · | $1.99 | $1.82 | $0.79 | · | $-0.44 | $-1.01 | $-1.07 | · | $-2.75 | $-3.33 | $-3.61 | · | $-2.42 |
Valutazione (TTM)
| Metrica | Tendenza | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 | Q3 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $15.89B | $14.72B | · | $12.63B | $11.89B | $11.24B | · | $10.15B | $9.61B | $9.11B | · | $8.15B | $7.69B | $7.16B | · | $6.07B | |
| Net Income TTM | $841M | $926M | · | $863M | $781M | $339M | · | $-172M | $-407M | $-420M | · | $-1.04B | $-1.27B | $-1.36B | · | $-880M | |
| Market Cap | $79.95B | $65.46B | · | $117.20B | $105.24B | $77.43B | · | $59.26B | $44.94B | $56.26B | · | $31.66B | $30.01B | $24.77B | · | $19.19B | |
| P/E | 96.1 | 71.2 | · | 136.7 | 135.4 | 231.4 | · | -324.4 | -107.7 | -128.7 | · | -28.9 | -22.9 | -17.6 | · | -20.4 | |
| P/S | 5.0 | 4.4 | · | 9.3 | 8.8 | 6.9 | · | 5.8 | 4.7 | 6.2 | · | 3.9 | 3.9 | 3.5 | · | 3.2 | |
| P/B | 8.1 | 6.4 | · | 12.3 | 11.8 | 9.2 | · | 7.8 | 6.3 | 8.0 | · | 4.8 | 4.7 | 3.8 | · | 2.8 | |
| P / Tangible Book | 33.0 | 25.4 | · | 23.2 | 23.4 | 14.1 | · | 13.1 | 10.7 | 14.1 | · | 8.9 | 9.1 | 7.3 | · | 4.9 | |
| P / Cash Flow | · | 110.2 | · | · | · | 121.9 | · | · | · | 101.7 | · | · | · | 62.4 | · | · | |
| Earnings Yield | 1.0% | 1.4% | · | 0.73% | 0.74% | 0.43% | · | -0.31% | -0.93% | -0.78% | · | -3.5% | -4.4% | -5.7% | · | -4.9% |
Periodo più recente a sinistra · valori nulli mostrati come ·
Bilanci Conto economico, stato patrimoniale, flusso di cassa — annuale, ultimi 5 anni
| Metrica | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Ricavi | $13.72B | $10.72B | $8.63B | $6.58B | $4.89B |
| Margine Operativo % | 5.3% | -0.35% | -6.7% | -17.1% | -9.2% |
| Utile netto | $935M | $123M | $-558M | $-1.36B | $-468M |
| EPS Diluito | $2.13 | $0.29 | $-1.42 | $-3.68 | $-1.39 |
| Metrica | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Rapporto corrente | · | 1.7 | 1.6 | 1.9 | 2.6 |
| Quick Ratio | · | 1.1 | 0.9 | 0.9 | 1.6 |
| Metrica | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Flusso di cassa libero | $2.17B | $2.03B | $1.55B | $191M | $563M |
Proprietari istituzionali (13F) 1.169 filer · $79.2B totale · Aggiornato al 30 Settembre 2026
Istituzioni che segnalano il possesso di questo titolo nel loro Modulo SEC 13F trimestrale. Solo posizioni lunghe; un singolo depositante può apparire due volte per diverse gambe di opzioni. Grandi posizioni put/call contrapposte riflettono tipicamente market-making o inventario coperto, non convinzione direzionale.
| Nuove posizioni | Posizioni chiuse | Aumentato | Diminuito | Variazione netta delle azioni |
|---|---|---|---|---|
| 171 (+10 vs trimestre precedente) | 120 (-64 vs trimestre precedente) | 412 (+13 vs trimestre precedente) | 372 (-38 vs trimestre precedente) | +12.6M |
Confrontato con Q1 2026. Le dichiarazioni SEC Form 13F sono dovute entro 45 giorni dalla fine del trimestre più un breve margine per i dichiaranti in ritardo — i trimestri ancora all'interno di questa finestra vengono saltati a favore della coppia più recente completamente riportata.
| Istituzione | Valore | Azioni | % di 13F tracciati | Tipo |
|---|---|---|---|---|
| VANGUARD GROUP INC | $9.835.228.964 | 43.426.479 | 12,41% | Azioni |
| SC US (TTGP), LTD. | $5.830.240.851 | 31.595.084 | 7,36% | Azioni |
| BlackRock, Inc. | $4.957.203.515 | 26.863.944 | 6,26% | Azioni |
| VANGUARD CAPITAL MANAGEMENT LLC | $4.511.093.823 | 24.446.398 | 5,69% | Azioni |
| VANGUARD PORTFOLIO MANAGEMENT LLC | $3.224.942.236 | 17.476.520 | 4,07% | Azioni |
| STATE STREET CORP | $2.971.424.957 | 16.102.666 | 3,75% | Azioni |
| MORGAN STANLEY | $2.678.183.152 | 14.513.536 | 3,38% | Azioni |
| JPMORGAN CHASE & CO | $2.483.553.075 | 13.437.684 | 3,13% | Azioni |
| Invesco Ltd. | $2.409.705.629 | 13.058.612 | 3,04% | Azioni |
| Capital Research Global Investors | $2.019.671.813 | 10.944.937 | 2,55% | Azioni |
| Capital World Investors | $1.917.374.215 | 10.390.570 | 2,42% | Azioni |
| GEODE CAPITAL MANAGEMENT, LLC | $1.668.238.570 | 9.080.148 | 2,11% | Azioni |
| Newlands Management Operations LLC | $1.304.313.214 | 7.068.299 | 1,65% | Azioni |
| BAILLIE GIFFORD & CO | $1.256.411.994 | 6.808.714 | 1,59% | Azioni |
| JANUS HENDERSON GROUP PLC | $1.159.377.028 | 7.762.553 | 1,46% | Azioni |
| FMR LLC | $971.714.735 | 5.265.890 | 1,23% | Azioni |
| NORGES BANK | $914.956.760 | 4.958.309 | 1,15% | Azioni |
| GOLDMAN SACHS GROUP INC | $851.792.231 | 4.616.010 | 1,08% | Azioni |
| BANK OF AMERICA CORP /DE/ | $839.705.896 | 4.550.512 | 1,06% | Azioni |
| Durable Capital Partners LP | $766.571.389 | 4.154.183 | 0,97% | Azioni |
| PARNASSUS INVESTMENTS, LLC | $717.176.767 | 3.886.505 | 0,91% | Azioni |
| WELLINGTON MANAGEMENT GROUP LLP | $708.782.683 | 3.841.016 | 0,89% | Azioni |
| Temasek Holdings (Private) Ltd | $638.750.780 | 3.461.501 | 0,81% | Azioni |
| NORTHERN TRUST CORP | $604.209.715 | 3.274.317 | 0,76% | Azioni |
| JANE STREET GROUP, LLC | $573.150.180 | 3.106.000 | 0,72% | Opzione Call |
| CHARLES SCHWAB INVESTMENT MANAGEMENT INC | $563.343.886 | 3.052.858 | 0,71% | Azioni |
| WELLCOME TRUST LTD (THE) as trustee of the WELLCOME TRUST | $553.590.000 | 3.000.000 | 0,70% | Azioni |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $482.915.010 | 2.617.000 | 0,61% | Opzione Call |
| UBS AM, a distinct business unit of UBS ASSET MANAGEMENT AMERICAS LLC | $458.530.474 | 3.053.816 | 0,58% | Azioni |
| Artisan Partners Limited Partnership | $440.184.162 | 2.385.434 | 0,56% | Azioni |
| Bank of New York Mellon Corp | $436.065.524 | 2.363.114 | 0,55% | Azioni |
| SANDS CAPITAL MANAGEMENT, LLC | $429.178.951 | 2.325.795 | 0,54% | Azioni |
| UBS Group AG | $424.551.309 | 2.300.717 | 0,54% | Azioni |
| VANGUARD FIDUCIARY TRUST CO | $399.972.466 | 2.167.520 | 0,50% | Azioni |
| Legal & General Group Plc | $394.699.439 | 2.138.939 | 0,50% | Azioni |
| Amundi | $387.252.812 | 2.098.590 | 0,49% | Azioni |
| ALKEON CAPITAL MANAGEMENT LLC | $381.977.098 | 2.070.000 | 0,48% | Opzione Call |
| AMERIPRISE FINANCIAL INC | $370.331.889 | 2.006.812 | 0,47% | Azioni |
| PointState Capital LP | $337.687.501 | 1.829.987 | 0,43% | Azioni |
| FIRST TRUST ADVISORS LP | $336.799.845 | 1.825.177 | 0,43% | Azioni |
| FRANKLIN RESOURCES INC | $327.487.974 | 1.774.714 | 0,41% | Azioni |
| Nuveen, LLC | $283.544.258 | 1.536.576 | 0,36% | Azioni |
| Foxhaven Asset Management, LP | $266.988.707 | 1.446.858 | 0,34% | Azioni |
| NOMURA ASSET MANAGEMENT INTERNATIONAL INC. | $259.072.000 | 1.403.958 | 0,33% | Azioni |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $252.713.835 | 1.369.500 | 0,32% | Opzione Put |
| D1 Capital Partners L.P. | $240.572.684 | 1.303.705 | 0,30% | Azioni |
| WOLVERINE TRADING, LLC | $239.636.500 | 879.400 | 0,30% | Opzione Call |
| BNP PARIBAS FINANCIAL MARKETS | $236.166.292 | 1.279.826 | 0,30% | Azioni |
| PRINCIPAL FINANCIAL GROUP INC | $229.065.340 | 1.241.295 | 0,29% | Azioni |
| DIMENSIONAL FUND ADVISORS LP | $228.367.246 | 1.237.545 | 0,29% | Azioni |
Insider aziendali 20 insider · 7 dirigenti · 13 direttori
| Insider | Ruolo | Ultima attività | Azioni possedute | Acquisti 12m | Vendite 12m | Netto 12m |
|---|---|---|---|---|---|---|
| Tony Xu | CHIEF EXECUTIVE OFFICER | 03 Settembre 2026 J | 1.500 | 0 | 15 | $-88.705.441 |
| Ravi Inukonda | CHIEF FINANCIAL OFFICER | 01 Settembre 2026 M | 217.911 | 0 | 36 | $-27.417.019 |
| Prabir Adarkar | PRESIDENT AND COO | 28 Settembre 2026 S | 921.473 | 0 | 71 | $-59.160.684 |
| Christopher D Payne | President and COO | 28 Febbraio 2023 S | 322.951 | 0 | 0 | $0 |
| Keith Yandell | CHIEF BUSINESS OFFICER | 17 Settembre 2026 S | 120.688 | 0 | 28 | $-6.562.271 |
| Gordon S Lee | CHIEF ACCOUNTING OFFICER | 04 Settembre 2026 S | 83.919 | 0 | 11 | $-4.057.453 |
| Tia Sherringham | GENERAL COUNSEL AND SECRETARY | 24 Agosto 2026 S | 118.262 | 0 | 17 | $-8.803.608 |
| Stanley Tang | Direttore | 02 Settembre 2026 J | 10.361 | 0 | 95 | $-114.670.597 |
| Andy Fang | Direttore | 01 Settembre 2026 J | 0 | 0 | 69 | $-43.760.427 |
| Alfred Lin | Direttore | 07 Agosto 2026 J | 877.117 | 11 | 0 | $100.277.893 |
| Shona L Brown | Direttore | 26 Giugno 2026 S | 31.156 | 0 | 13 | $-2.164.314 |
| Milan Kovac | Direttore | 10 Giugno 2026 A | 3.928 | 2 | 0 | $6.238 |
| Ashley Still | Direttore | 10 Giugno 2026 S | 2.685 | 0 | 6 | $-250.828 |
| Elinor Mertz | Direttore | 10 Giugno 2026 A | 15.809 | 0 | 0 | $0 |
| Jeffrey M Blackburn | Direttore | 10 Giugno 2026 A | 8.102 | 0 | 0 | $0 |
| Diego Piacentini | Direttore | 10 Giugno 2026 A | 13.350 | 0 | 0 | $0 |
| DOERR L JOHN | Direttore | 10 Giugno 2026 A | 9.069 | 0 | 0 | $0 |
| Gregory K Peters | Direttore | 20 Giugno 2023 A | 9.818 | 0 | 0 | $0 |
| Stanley J Meresman | Direttore | 24 Maggio 2023 S | 3.557 | 0 | 0 | $0 |
| Maria Renz | · | 22 Giugno 2021 A | 11.408 | 0 | 0 | $0 |
Insider dai depositi SEC Modulo 3/4/5; netto = solo acquisti/vendite di mercato
Proprietà ETF Posseduti da 125 ETF
Il peso riflette solo le partecipazioni azionarie dirette (N-PORT); fondi a leva o basati su derivati possono detenere ulteriore esposizione swap non mostrata.
| Fondo | Peso | Unità | Aggiornato al | Fonte |
|---|---|---|---|---|
| FDND · First Trust Exchange-Traded Fund IV | 2,93% | 1.457 NS | 31 Luglio 2026 | N-PORT |
| JXX · Janus Detroit Street Trust | 2,64% | 3.590 NS | 31 Luglio 2026 | N-PORT |
| RSPD · Invesco Exchange-Traded Fund Trust | 2,05% | 40.724 SH | 01 Ottobre 2026 | Giornaliero |
| PNQI · Invesco Exchange-Traded Fund Trust | 2,01% | 58.378 SH | 01 Ottobre 2026 | Giornaliero |
| WEBL · Direxion Shares ETF Trust | 1,90% | 9.058 NS | 31 Luglio 2026 | N-PORT |
| ARKX · ARK ETF Trust | 1,78% | 68.997 NS | 31 Luglio 2026 | N-PORT |
| QNXT · iShares Trust | 1,58% | 2.152 SH | 11 Settembre 2026 | Giornaliero |
| ARKF · ARK ETF Trust | 1,58% | 56.481 NS | 31 Luglio 2026 | N-PORT |
| ARKQ · ARK ETF Trust | 1,52% | 143.833 NS | 31 Luglio 2026 | N-PORT |
| VOT · VANGUARD INDEX FUNDS | 1,50% | 2.836.119 SH | 19 Agosto 2026 | Giornaliero |
| QQQE · Direxion Shares ETF Trust | 1,25% | 85.333 NS | 31 Luglio 2026 | N-PORT |
| RXI · iShares Trust | 1,22% | 14.972 SH | 11 Settembre 2026 | Giornaliero |
| FDIS · FIDELITY COVINGTON TRUST | 1,17% | 100.427 NS | 31 Luglio 2026 | N-PORT |
| ARKW · ARK ETF Trust | 1,15% | 93.876 NS | 31 Luglio 2026 | N-PORT |
| VCR · VANGUARD WORLD FUND | 1,08% | 401.841 SH | 19 Agosto 2026 | Giornaliero |
| IMCG · iShares Trust | 1,05% | 208.592 SH | 11 Settembre 2026 | Giornaliero |
| WANT · Direxion Shares ETF Trust | 1,04% | 1.078 NS | 31 Luglio 2026 | N-PORT |
| ALTL · Pacer Funds Trust | 0,94% | 4.401 NS | 31 Luglio 2026 | N-PORT |
| GARP · iShares Trust | 0,89% | 134.731 SH | 11 Settembre 2026 | Giornaliero |
| RPG · Invesco Exchange-Traded Fund Trust | 0,88% | 92.348 SH | 01 Ottobre 2026 | Giornaliero |
| TRFM · ETF Series Solutions | 0,87% | 10.984 NS | 31 Luglio 2026 | N-PORT |
| VO · VANGUARD INDEX FUNDS | 0,66% | 8.022.824 SH | 19 Agosto 2026 | Giornaliero |
| SPHB · Invesco Exchange-Traded Fund Trust … | 0,64% | 33.027 SH | 01 Ottobre 2026 | Giornaliero |
| HIBL · Direxion Shares ETF Trust | 0,64% | 2.432 NS | 31 Luglio 2026 | N-PORT |
| IMCB · iShares Trust | 0,53% | 44.208 SH | 11 Settembre 2026 | Giornaliero |
| PALC · Pacer Funds Trust | 0,53% | 5.637 NS | 31 Luglio 2026 | N-PORT |
| HEQQ · J.P. Morgan Exchange-Traded Fund Tr… | 0,52% | 794 NS | 31 Luglio 2026 | N-PORT |
| JHAI · Janus Detroit Street Trust | 0,52% | 620 NS | 31 Luglio 2026 | N-PORT |
| WINN · Harbor ETF Trust | 0,48% | 27.907 NS | 31 Luglio 2026 | N-PORT |
| ACVF · ETF Opportunities Trust | 0,46% | 3.561 NS | 31 Luglio 2026 | N-PORT |
| XOEF · iShares Trust | 0,43% | 477 SH | 11 Settembre 2026 | Giornaliero |
| FTC · First Trust Exchange-Traded AlphaDE… | 0,41% | 27.858 NS | 31 Luglio 2026 | N-PORT |
| QYLD · Global X Funds | 0,38% | 155.480 NS | 31 Luglio 2026 | N-PORT |
| IYW · iShares Trust | 0,37% | 464.177 SH | 11 Settembre 2026 | Giornaliero |
| PTNQ · Pacer Funds Trust | 0,37% | 22.492 NS | 31 Luglio 2026 | N-PORT |
| QYLG · Global X Funds | 0,37% | 2.958 NS | 31 Luglio 2026 | N-PORT |
| QTR · Global X Funds | 0,37% | 142 NS | 31 Luglio 2026 | N-PORT |
| QRMI · Global X Funds | 0,37% | 266 NS | 31 Luglio 2026 | N-PORT |
| QQWZ · Pacer Funds Trust | 0,36% | 938 NS | 31 Luglio 2026 | N-PORT |
| QCLR · Global X Funds | 0,36% | 61 NS | 31 Luglio 2026 | N-PORT |
| FXL · First Trust Exchange-Traded AlphaDE… | 0,35% | 46.085 NS | 31 Luglio 2026 | N-PORT |
| QSIX · Pacer Funds Trust | 0,34% | 318 NS | 31 Luglio 2026 | N-PORT |
| JMOM · J.P. Morgan Exchange-Traded Fund Tr… | 0,33% | 42.003 NS | 31 Luglio 2026 | N-PORT |
| QQQM · Invesco Exchange-Traded Fund Trust … | 0,31% | 1.880.647 SH | 01 Ottobre 2026 | Giornaliero |
| QQQ · Invesco QQQ Trust, Series 1 | 0,31% | 8.544.692 SH | 01 Ottobre 2026 | Giornaliero |
| FBCG · FIDELITY COVINGTON TRUST | 0,31% | 110.030 NS | 31 Luglio 2026 | N-PORT |
| JVAL · J.P. Morgan Exchange-Traded Fund Tr… | 0,31% | 13.177 NS | 31 Luglio 2026 | N-PORT |
| IWY · iShares Trust | 0,27% | 205.882 SH | 11 Settembre 2026 | Giornaliero |
| SIZE · iShares Trust | 0,24% | 5.101 SH | 11 Settembre 2026 | Giornaliero |
| ILCG · iShares Trust | 0,24% | 36.720 SH | 11 Settembre 2026 | Giornaliero |
| HELO · J.P. Morgan Exchange-Traded Fund Tr… | 0,23% | 54.514 NS | 31 Luglio 2026 | N-PORT |
| USMV · iShares Trust | 0,23% | 272.485 SH | 11 Settembre 2026 | Giornaliero |
| IWF · iShares Trust | 0,23% | 1.408.528 SH | 11 Settembre 2026 | Giornaliero |
| VEGN · ETF Series Solutions | 0,23% | 2.040 NS | 31 Luglio 2026 | N-PORT |
| IVW · iShares Trust | 0,21% | 807.070 SH | 11 Settembre 2026 | Giornaliero |
| VUG · VANGUARD INDEX FUNDS | 0,21% | 4.247.615 SH | 19 Agosto 2026 | Giornaliero |
| FAD · First Trust Exchange-Traded AlphaDE… | 0,21% | 6.054 NS | 31 Luglio 2026 | N-PORT |
| IUSG · iShares Trust | 0,20% | 333.160 SH | 11 Settembre 2026 | Giornaliero |
| WRND · New York Life Investments ETF Trust | 0,20% | 107 NS | 31 Luglio 2026 | N-PORT |
| VOOG · VANGUARD ADMIRAL FUNDS | 0,20% | 281.083 SH | 19 Agosto 2026 | Giornaliero |
| VONG · VANGUARD SCOTTSDALE FUNDS | 0,20% | 593.594 SH | 19 Agosto 2026 | Giornaliero |
| DFUV · Dimensional ETF Trust | 0,19% | 152.231 NS | 31 Luglio 2026 | N-PORT |
| RSP · Invesco Exchange-Traded Fund Trust | 0,19% | 991.668 SH | 01 Ottobre 2026 | Giornaliero |
| EUSA · iShares, Inc. | 0,19% | 17.720 SH | 11 Settembre 2026 | Giornaliero |
| GLBL · Pacer Funds Trust | 0,18% | 10 NS | 31 Luglio 2026 | N-PORT |
| EGLE · Global X Funds | 0,17% | 19 NS | 31 Luglio 2026 | N-PORT |
| LGDX · Tidal Trust III | 0,17% | 1.199 NS | 31 Luglio 2026 | N-PORT |
| TOPC · iShares Trust | 0,14% | 230 SH | 11 Settembre 2026 | Giornaliero |
| IWL · iShares Trust | 0,13% | 14.588 SH | 11 Settembre 2026 | Giornaliero |
| XVV · iShares Trust | 0,13% | 4.343 SH | 11 Settembre 2026 | Giornaliero |
| VOXP · Advisors Series Trust | 0,12% | 36 NS | 31 Luglio 2026 | N-PORT |
| ESGV · VANGUARD WORLD FUND | 0,12% | 84.740 SH | 19 Agosto 2026 | Giornaliero |
| IETC · iShares U.S. ETF Trust | 0,12% | 4.095 SH | 11 Settembre 2026 | Giornaliero |
| XTR · Global X Funds | 0,12% | 29 NS | 31 Luglio 2026 | N-PORT |
| XYLG · Global X Funds | 0,12% | 384 NS | 31 Luglio 2026 | N-PORT |
| XYLD · Global X Funds | 0,12% | 19.383 NS | 31 Luglio 2026 | N-PORT |
| IVV · iShares Trust | 0,12% | 4.769.872 SH | 11 Settembre 2026 | Giornaliero |
| CATH · Global X Funds | 0,12% | 7.714 NS | 31 Luglio 2026 | N-PORT |
| XCLR · Global X Funds | 0,12% | 21 NS | 31 Luglio 2026 | N-PORT |
| CHRI · Global X Funds | 0,12% | 47 NS | 31 Luglio 2026 | N-PORT |
| BBUS · J.P. Morgan Exchange-Traded Fund Tr… | 0,11% | 51.958 NS | 31 Luglio 2026 | N-PORT |
| DFSU · Dimensional ETF Trust | 0,11% | 13.242 NS | 31 Luglio 2026 | N-PORT |
| VOTE · TCW ETF Trust | 0,11% | 6.375 NS | 31 Luglio 2026 | N-PORT |
| ILCB · iShares Trust | 0,11% | 7.302 SH | 11 Settembre 2026 | Giornaliero |
| PTLC · Pacer Funds Trust | 0,11% | 18.932 NS | 31 Luglio 2026 | N-PORT |
| XRMI · Global X Funds | 0,11% | 287 NS | 31 Luglio 2026 | N-PORT |
| VOO · VANGUARD INDEX FUNDS | 0,11% | 9.832.428 SH | 19 Agosto 2026 | Giornaliero |
| VV · VANGUARD INDEX FUNDS | 0,11% | 432.357 SH | 19 Agosto 2026 | Giornaliero |
| IYY · iShares Trust | 0,11% | 16.197 SH | 11 Settembre 2026 | Giornaliero |
| IWB · iShares Trust | 0,11% | 259.843 SH | 11 Settembre 2026 | Giornaliero |
| BKLC · BNY Mellon ETF Trust | 0,11% | 29.973 NS | 31 Luglio 2026 | N-PORT |
| PBP · Invesco Exchange-Traded Fund Trust | 0,11% | 2.243 SH | 01 Ottobre 2026 | Giornaliero |
| SPUU · Direxion Shares ETF Trust | 0,11% | 1.427 NS | 31 Luglio 2026 | N-PORT |
| DFUS · Dimensional ETF Trust | 0,11% | 111.972 NS | 31 Luglio 2026 | N-PORT |
| QDPL · Pacer Funds Trust | 0,10% | 9.111 NS | 31 Luglio 2026 | N-PORT |
| ITOT · iShares Trust | 0,10% | 492.153 SH | 11 Settembre 2026 | Giornaliero |
| PBUS · Invesco Exchange-Traded Fund Trust … | 0,10% | 63.915 SH | 01 Ottobre 2026 | Giornaliero |
| IWV · iShares Trust | 0,10% | 102.961 SH | 11 Settembre 2026 | Giornaliero |
| VONE · VANGUARD SCOTTSDALE FUNDS | 0,10% | 62.097 SH | 19 Agosto 2026 | Giornaliero |
| VTHR · VANGUARD SCOTTSDALE FUNDS | 0,10% | 31.561 SH | 19 Agosto 2026 | Giornaliero |
| TOV · EA Series Trust | 0,10% | 1.380 NS | 31 Luglio 2026 | N-PORT |
| FEX · First Trust Exchange-Traded AlphaDE… | 0,10% | 7.636 NS | 31 Luglio 2026 | N-PORT |
| DFAU · Dimensional ETF Trust | 0,09% | 58.531 NS | 31 Luglio 2026 | N-PORT |
| HCMT · Direxion Shares ETF Trust | 0,09% | 2.631 NS | 31 Luglio 2026 | N-PORT |
| VTI · VANGUARD INDEX FUNDS | 0,09% | 11.755.244 SH | 19 Agosto 2026 | Giornaliero |
| TOK · iShares Trust | 0,09% | 1.052 SH | 11 Settembre 2026 | Giornaliero |
| PHDG · Invesco Actively Managed Exchange-T… | 0,09% | 296 SH | 01 Ottobre 2026 | Giornaliero |
| SPXL · Direxion Shares ETF Trust | 0,09% | 29.590 NS | 31 Luglio 2026 | N-PORT |
| HDUS · Lattice Strategies Trust | 0,09% | 883 NS | 31 Luglio 2026 | N-PORT |
| CRBN · iShares Trust | 0,08% | 4.849 SH | 11 Settembre 2026 | Giornaliero |
| ESMV · iShares Trust | 0,08% | 32 SH | 11 Settembre 2026 | Giornaliero |
| URTH · iShares, Inc. | 0,08% | 33.008 SH | 11 Settembre 2026 | Giornaliero |
| RWL · Invesco Exchange-Traded Fund Trust … | 0,08% | 40.202 SH | 01 Ottobre 2026 | Giornaliero |
| ACWI · iShares Trust | 0,07% | 118.219 SH | 11 Settembre 2026 | Giornaliero |
| TILT · FlexShares Trust | 0,07% | 7.900 NS | 31 Luglio 2026 | N-PORT |
| IUS · Invesco Exchange-Traded Self-Indexe… | 0,07% | 3.534 SH | 01 Ottobre 2026 | Giornaliero |
| DFAC · Dimensional ETF Trust | 0,07% | 159.811 NS | 31 Luglio 2026 | N-PORT |
| DCOR · Dimensional ETF Trust | 0,06% | 10.905 NS | 31 Luglio 2026 | N-PORT |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0,06% | 312.434 SH | 19 Agosto 2026 | Giornaliero |
| EQAL · Invesco Exchange-Traded Fund Trust … | 0,06% | 2.511 SH | 01 Ottobre 2026 | Giornaliero |
| PEVC · Pacer Funds Trust | 0,06% | 7 NS | 31 Luglio 2026 | N-PORT |
| LRGF · iShares Trust | 0,05% | 9.295 SH | 11 Settembre 2026 | Giornaliero |
| PRF · Invesco Exchange-Traded Fund Trust | 0,03% | 16.656 SH | 01 Ottobre 2026 | Giornaliero |
| DFLV · Dimensional ETF Trust | 0,00% | 218 NS | 31 Luglio 2026 | N-PORT |
| LSEQ · Harbor ETF Trust | -2,19% | -1.712 NS | 31 Luglio 2026 | N-PORT |
DASH Consenso degli analisti Opinioni degli analisti, sia rialziste che ribassiste, target price a 12 mesi, potenziale di rialzo
Target Price a 12 Mesi
43 analisti · 2026-10-02Target medio $256.26 +35,5%
Confronto Peer (GICS sub-settore industriale) Metriche chiave rispetto ai pari del settore
Base FY, prezzi alla chiusura dell'ultimo anno fiscale di ciascuna società.
| Ticker | Capitalizzazione di Mercato | P/E | Rev YoY | Margine Netto | ROE | Margine lordo |
|---|---|---|---|---|---|---|
| DASH | · | 106.3 | 27.9% | 6.8% | · | · |
| MCD | · | 25.6 | 3.7% | 31.9% | -376.3% | · |
| SBUX | $94.81B | 51.2 | 2.8% | 5.0% | -23.9% | · |
| YUM | · | 27.3 | 8.8% | 19.0% | -20.8% | · |
| CMG | · | 32.5 | 5.4% | 12.9% | 48.3% | · |
| QSR | $23.63B | 29.0 | 12.2% | 11.4% | 31.9% | · |
| DRI | $23.27B | 19.6 | 9.4% | 9.1% | 56.3% | 20.3% |
| ARMK | $10.25B | 32.0 | 6.3% | 1.8% | 10.6% | · |
| TXRH | $11.03B | 27.4 | 9.4% | 7.0% | 29.4% | · |
| DPZ | $14.31B | 24.2 | 5.0% | 12.2% | -15.3% | 40.0% |
| EAT | $7.17B | 15.6 | 7.9% | 8.4% | 118.3% | · |
Ultime notizie Notizie recenti che menzionano questa società
DASH Pannello Analisti AI — Viste Rialziste e Ribassiste Dibattito 2026Q2: Claude, Grok, Gemini, ChatGPT sulle prospettive del titolo
DoorDash è attualmente un titolo conteso, bloccato tra il suo potenziale di potenza logistica e la realtà della sua costosa valutazione. Gemini e Claude hanno sostenuto che il rapporto P/E di 113 è insostenibile dati i sottili margini netti, mentre Grok ha replicato che il volume istituzionale e la scala giustificano il premio. Il panel rimane diviso sulla questione se l'espansione dell'azienda nella spesa alimentare possa finalmente sbloccare l'efficienza necessaria a sostenere il suo prezzo attuale, con la maggior parte degli analisti che mantiene un rating di "hold".
Round 1 — Prime impressioni
Vedo DoorDash costruire un fossato duraturo nella consegna di cibo attraverso effetti di rete che bloccano utenti e ristoranti per accelerare i profitti. I margini lordi si mantengono stabili al 50,49%, dimostrando che catturano la metà di ogni dollaro d'ordine nonostante la forte concorrenza, un segno di reale potere di determinazione dei prezzi. L'EPS è salito a 1,93$, riflettendo una redditività scalabile all'aumentare dei volumi degli ordini. Con un current ratio di 2,04, dispongono di ampia liquidità per investire nell'espansione senza rischi di diluizione. Se le scommesse sulla spesa alimentare e internazionali daranno i loro frutti, questo si comporrà in una macchina da soldi entro il 2026Q2.
La mia opinione è che DoorDash sia scambiata a un premio che presuppone un'esecuzione impeccabile, ma una crescita in rallentamento potrebbe distruggere i rendimenti dati i multipli elevati. Il P/E si attesta a 113, ben al di sopra dei concorrenti come MCD a 25,5, il che significa che il mercato prezza anni di iper-crescita che la saturazione delle consegne minaccia di far deragliare. Il ROE è solo del 9,97%, inferiore ai concorrenti come CMG al 47%, segnalando un uso inefficiente del capitale nonostante i profitti. Il rapporto debito/capitale proprio a 28,67 è basso ma irrilevante se i margini scivolano sotto la pressione competitiva di Uber Eats.
DoorDash ha costruito una rete logistica difendibile che sta finalmente convertendo la scala in profitto reale. L'EPS è salito a 1,93$ negli ultimi dodici mesi e l'azienda sta trasformando il 10% del capitale proprio in utili, modesto per gli standard tecnologici, ma reale e in crescita. Il titolo è salito del 35% dai minimi di maggio a 240$, e i margini lordi si mantengono stabili al 50%, il che significa che l'economia unitaria si mantiene anche se la concorrenza si intensifica. Se la gestione riuscirà a spingere i margini netti dal 6,8% verso il 10% nei prossimi due anni attraverso la leva operativa, la valutazione attuale inizia a sembrare ragionevole per un attore di duopolio in un TAM di oltre 200 miliardi di dollari.
DoorDash è scambiata a 113 volte gli utili degli ultimi dodici mesi, circa 4 volte quanto comanda McDonald's e 2 volte quanto paga Chipotle. Quel P/E non è giustificato dai fondamentali. Il ROE si attesta al 10%, una frazione di quanto generano concorrenti come Starbucks (116%) e Yum (118%), il che ti dice che DoorDash è intrappolata in un modello di business a rendimento inferiore nonostante la sua scala. Il titolo ha già prezzato la perfezione: i margini sono piatti, la crescita sta decelerando e l'azienda sta bruciando capitale in incentivi per i driver solo per mantenere la quota di mercato. A 240$, stai pagando per una commodity logistica, non per un moltiplicatore.
DoorDash si sta effettivamente consolidando come lo strato di utilità essenziale per il commercio locale, andando ben oltre la semplice consegna di cibo. L'azienda mantiene un margine lordo del 50,49%. Ciò indica che per ogni dollaro di ricavi, oltre la metà rimane dopo i costi diretti, dimostrando che la loro piattaforma ha una scala significativa ed efficienza operativa. Inoltre, il loro current ratio si attesta a 2,04. Ciò significa che l'azienda ha più di due dollari in attività liquide per ogni dollaro di debito a breve termine, dando loro la possibilità finanziaria di continuare un'espansione aggressiva nelle categorie di generi alimentari e vendita al dettaglio senza dover raccogliere capitali costosi.
Il divario di valutazione tra DoorDash e i suoi concorrenti nel settore della ristorazione è semplicemente troppo ampio da giustificare dato il profilo di redditività attuale. Il titolo è scambiato a un rapporto P/E di 113,11. Ciò significa che gli investitori stanno pagando un premio massiccio per una crescita degli utili che è significativamente più costosa rispetto ai giganti affermati del fast-food come McDonald's. Inoltre, il ritorno sul capitale proprio è solo del 9,97%. Ciò suggerisce che l'azienda non sta ancora generando rendimenti efficienti sul capitale fornito dagli azionisti, facendo apparire l'attuale multiplo degli utili a tre cifre una scommessa speculativa piuttosto che un investimento basato sul valore per il 2026.
Penso che il caso rialzista più forte di DoorDash sia che l'economia della piattaforma sia duratura e la traiettoria di crescita rimanga intatta, supportata da un bilancio conservativo e da segnali di miglioramento della redditività. L'EPS TTM è 1,93$ per azione. Ciò significa che l'azienda sta già generando utili positivi, dandole la flessibilità di investire nella crescita senza bisogno di nuovo capitale proprio. Il margine lordo è del 50,49%. Quel livello mostra che il marketplace principale genera un solido profitto lordo sui ricavi, che, con la scala, può supportare margini operativi più elevati. Il rapporto Debito/Capitale proprio è 28,67. Quella leva modesta dà al bilancio spazio per finanziare l'espansione o resistere a una recessione.
Penso che il caso ribassista sia che DoorDash sia scambiata a un multiplo altissimo per una crescita con limitata espansione dei margini nel breve termine, e che venti contrari competitivi o normativi potrebbero far deragliare il rally. Il P/E TTM è 113,11. È estremo rispetto ai concorrenti, il che implica che il titolo prezza una crescita molto elevata e un fallimento potrebbe comprimere i multipli. Il P/S TTM è 7,73. Quel premio sulle vendite segnala che gli investitori pagano per la crescita piuttosto che per la redditività attuale. Il ROE TTM è 9,97%. Quel ROE è modesto rispetto ai concorrenti con rendimenti sul capitale proprio molto più elevati, suggerendo un'efficienza limitata e che il potenziale di rialzo dipende dalla crescita della linea superiore piuttosto che dai rendimenti sul capitale.
Round 2 — Risposte e Confutazioni
Round 2 — Risposte e Confutazioni
Claude, il tuo caso ribassista secondo cui il rally del 35% prezza la perfezione ignora come i multipli si stiano comprimendo con la crescita dei profitti. Il P/E è sceso da 133 lo scorso trimestre a 113 ora, poiché l'EPS è salito da 1,76$ a 1,93$. Ciò significa che il mercato sta riconoscendo l'esecuzione effettiva sulla scala, non solo sperando in miracoli sui margini, rendendo la valutazione più difendibile verso il 2026Q2.
Penso che Grok stia confondendo due cose diverse qui. Sì, il margine lordo al 50,49% è solido, ma non è la stessa cosa del potere di determinazione dei prezzi: è il margine dopo aver pagato ristoranti e costi di piattaforma, non dopo aver pagato i driver. Il vero test del potere di determinazione dei prezzi è il margine netto, che si attesta al 6,83% e non si è mosso da due trimestri. Questo mi dice che DoorDash è bloccata in una gara in cui ogni guadagno di efficienza viene annullato dalla concorrenza o speso in incentivi per i driver per mantenere la quota. Il punto di Grok sull'upside della spesa alimentare e internazionale è valido, ma si tratta di scommesse non provate. Il business principale non sta generando i rendimenti che giustificano un P/E di 113.
Claude, la tua attenzione sul ROE del 10% perde di vista la realtà che DoorDash è ancora in una fase di forti investimenti per le sue verticali non di ristorazione. Quel ROE del 9,97% rappresenta il rendimento sul capitale mentre l'azienda sta sussidiando aggressivamente il suo ingresso nella logistica di generi alimentari e vendita al dettaglio. Se dovessero passare a una modalità di pura raccolta, quel numero aumenterebbe in modo significativo, ma hai ragione sul fatto che la valutazione attuale presuppone che quella transizione sia già completata. Stiamo pagando per il potenziale futuro di una rete logistica, non per l'efficienza attuale di una catena di ristorazione matura.
Claude, la tua tesi sull'espansione dei margini si basa su miglioramenti a breve termine che potrebbero non materializzarsi data l'intensa pressione sugli incentivi ai driver e il rischio di pressione sui margini dalla concorrenza. Il P/E 113 segnala che il mercato sta già prezzando anni di crescita eccezionale indipendentemente dai risultati a breve termine. Quel premio significa che qualsiasi decelerazione della crescita o stallo nell'economia unitaria potrebbe innescare una brusca compressione dei multipli, complicando le prospettive anche se gli utili rimangono positivi.
Round 3 — Confutazioni Finali
Round 3 — Confutazioni Finali
Claude, il tuo caso ribassista trascura la convinzione tecnica che guida questo rally verso il 2026Q2. DoorDash è salita del 35% dai minimi di maggio. Quel guadagno è arrivato su acquisti di convinzione, con volumi in aumento a 24 milioni di azioni alla chiusura del 27 giugno a 242$. Le istituzioni si stanno posizionando pesantemente qui, non solo sperando nei margini; questo flusso rende il P/E 113 più resiliente di quanto suggeriscano i rapporti statici.
Voglio contestare la matematica di Grok qui, e penso che sia importante per come inquadriamo il rischio. Grok dice che il P/E si è compresso da 133 a 113 mentre l'EPS è cresciuto da 1,76$ a 1,93$, implicando che il mercato stia premiando l'esecuzione. Ma non è del tutto corretto. La capitalizzazione di mercato è effettivamente scesa da 104 miliardi di dollari a 97,6 miliardi di dollari nello stesso periodo, anche se gli utili sono aumentati. Ciò significa che i multipli non si sono compressi a causa della crescita dei profitti; si sono compressi perché il titolo ha venduto più duramente di quanto siano migliorati gli utili. Il rally dai minimi di maggio è reale, ma siamo ancora in calo del 6% rispetto a tre trimestri fa su base di utili per azione. Non è un voto di fiducia nel modello di business, è una ri-prezzatura del rischio. Mantengo il mio "hold", ma la narrativa secondo cui l'esecuzione viene premiata non corrisponde ai flussi di capitale effettivi.
Voglio mettere in discussione l'affermazione di Grok secondo cui la compressione del P/E da 133 a 113 convalida il prezzo delle azioni. Questo ignora il cambio di regime macroeconomico, in particolare il raffreddamento della crescita del settore delle consegne poiché la spesa discrezionale dei consumatori si stringe sotto i tassi di interesse elevati e sostenuti. Un P/E di 113,11 significa che il mercato sta ancora prezzando una traiettoria di crescita che presuppone che i consumatori continueranno a pagare commissioni di consegna premium indefinitamente. Se l'attuale ambiente dei tassi costringe le famiglie a passare ad alternative di ristorazione più economiche, quel multiplo di 113 affronterà una grave compressione indipendentemente dall'esecuzione interna di DoorDash o dai recenti guadagni dell'EPS.
Penso che dovremmo ampliare la prospettiva al rischio normativo relativo alla classificazione dei lavoratori autonomi come potenziale fattore di svolta per il 2026Q2. Il margine netto è del 6,83%. Quel margine relativamente sottile significa che qualsiasi riclassificazione verso costi dei driver più elevati potrebbe ulteriormente ridurre i profitti. Claude, la tua scommessa sull'espansione dei margini presuppone che i costi del lavoro rimangano contenuti; i cambiamenti normativi potrebbero far deragliare ciò. Tieni d'occhio la Prop 22 in California e i potenziali effetti a catena mentre gli stati ripensano le regole sul lavoro autonomo.
Previsioni di prezzo
| Modello | Obiettivo 3M | Obiettivo 6M | Motivazione |
|---|---|---|---|
| Grok | $255.00 | $275.00 | Penso che DoorDash sia scambiata equamente intorno ai livelli attuali con un modesto potenziale di rialzo poiché la scala aumenta l'EPS, comprimendo l'estremo P/E verso le realtà dei concorrenti entro il 2026Q2. Il catalizzatore chiave è il rilascio degli utili del Q2 2026 all'inizio di agosto, dove la guidance per una crescita degli ordini del 15%+ nella spesa alimentare potrebbe convalidare il pivot logistico e innescare nuovi acquisti. Il rischio maggiore è l'escalation a livello nazionale delle sfide alla California Prop 22, che aumenterebbe i costi dei driver e comprimerebbe i margini netti del 6,83%. A un target di 275$ a 6 mesi, il P/E scende a circa 90, il che prezza ancora una crescita aggressiva ma si allinea meglio con il 29 di CMG, premiando l'esecuzione senza perfezione. |
| Claude | $215.00 | $198.00 | DoorDash è un moltiplicatore ad alto multiplo prezzato per un'esecuzione impeccabile in un business intrappolato nei margini, e la matematica non supporta il premio. La mia tesi: l'113 P/E è ingiustificabile perché il margine netto si attesta al 6,83% e non si è mosso da due trimestri, il che significa che la scala non si traduce in redditività. Catalizzatore concreto: gli utili del Q2 2026. Se la gestione segnala un'espansione del margine netto all'8%+ e la mantiene nel Q3, rivedrei al rialzo; se rimanesse piatto o scendesse, i multipli si comprimerebbero duramente. Rischio concreto: riclassificazione normativa dei driver in California o a livello federale, che distruggerebbe istantaneamente quel margine del 6,83%. A 113 volte gli utili, DoorDash è scambiata a 4,4 volte il multiplo di McDonald's nonostante 1/10 del ROE; quel divario si chiude quando la crescita rallenta o i costi del lavoro aumentano. |
| Gemini | $215.00 | $235.00 | La mia tesi è che DoorDash sarà scambiata più in alto poiché dimostrerà la sua utilità come spina dorsale logistica, sebbene il percorso sarà volatile a causa dell'elevata valutazione. Un catalizzatore chiave per il target a 6 mesi è il rapporto sugli utili del Q4, dove una crescita sostenuta nelle categorie non di ristorazione potrebbe finalmente convincere il mercato a smettere di trattarla come una semplice app di consegna. Il rischio principale è un ampio giro di vite normativo sulla classificazione dei lavoratori autonomi, che distruggerebbe istantaneamente la loro economia unitaria. L'attuale P/E di 113,11 significa che gli investitori stanno pagando anni di crescita futura, quindi qualsiasi segno di rallentamento del volume degli ordini porterà a una compressione immediata e dolorosa del prezzo delle azioni. |
| Chatgpt | $200.00 | $210.00 | Penso che DoorDash possa salire gradualmente poiché le sue verticali non di ristorazione iniziano a contribuire in modo significativo ai profitti senza compromettere i margini lordi. Catalizzatore: la stampa degli utili del Q2 2026, dove la gestione prevede un mix di spesa alimentare/vendita al dettaglio ampliato e un miglioramento dell'economia unitaria, spingerebbe il titolo verso l'area dei 200. Rischio: una battuta d'arresto normativa sulla classificazione dei lavoratori autonomi o un picco dei costi dei driver potrebbe comprimere i margini e far deragliare il rally. Dal prezzo attuale di 187,76, un movimento verso circa 200 implicherebbe un modesto aumento della valutazione, con 210 che funge da controllo a orizzonte più lungo sulla fiducia nella crescita. |
Segnali di trading Segnali recenti di acquisto/vendita con prezzo di entrata e rapporto rischio/rendimento
Nessun segnale aperto al momento — nessuna scheda è compilata, e questo è onesto.
Le Mie Metriche La tua watchlist personale — righe selezionate da Fondamentali Completi
Scegli le metriche che contano per te: fai clic sul + accanto a qualsiasi riga in Fondamentali Completi sopra.
La tua selezione è salvata e ti segue su tutti i ticker.