ASML ASML Holding N.V. - New York Registry Shares
NASDAQ · Semiconductors · View on SEC EDGAR ↗ close Oct 2, 2026 10-K/10-Q Feb 25, 2026ASML Stock Snapshot Price, market cap, P/E, EPS, ROE, debt/equity, 52-week range
ASML Stock Price Chart Daily OHLCV with technical indicators — pan, zoom, and customize your view
Bar granularity adapts to the selected period — hover the chart to see open/high/low/close for a bar.
| Ex-date | Split | Type |
|---|---|---|
| Oct. 1, 2007 | 1-for-1 | Reverse |
| April 17, 2000 | 3-for-1 | Forward |
| May 8, 1998 | 2-for-1 | Forward |
| May 12, 1997 | 2-for-1 | Forward |
About ASML Holding N.V. - New York Registry Shares Company overview from Wikipedia
ASML Holding N.V. (originally an abbreviation of Advanced Semiconductor Materials Lithography) is a Dutch company that develops and manufactures photolithography machines used to produce integrated circuits. It is the largest supplier to the semiconductor industry and, as of 2026, the world's only manufacturer of extreme ultraviolet (EUV) lithography machines, which are required to manufacture the most advanced semiconductor chips. As of January 2026, ASML had a market capitalization of approximately $527 billion, making it Europe's largest technology company and one of its most valuable companies overall.
ASML was founded in 1984 as a joint venture between the Dutch technology companies Philips and ASM International and became an independent publicly traded company four years later. The company was established to complete development of a lithography machine that Philips had been developing internally, but initially had no market-ready products. ASML's first product, the PAS 2000, was a commercial and technical failure, but the company achieved commercial success in the early 1990s with the PAS 5500. By 2002, it had become the world's largest supplier of lithography machines.
Meanwhile, in 1997, ASML began developing its EUV lithography technology. To help fund the expensive research and development required, Intel invested $4.1 billion in ASML in July 2012 in exchange for a 15 percent stake. Samsung and TSMC subsequently acquired smaller stakes under the same co-investment program. ASML completed development of the first commercially viable EUV machines in the late 2010s. During the 2010s and 2020s, the governments of the Netherlands and the United States imposed increasingly stringent controls on ASML's sales of semiconductor manufacturing equipment to China, citing concerns including national security and the protection of advanced semiconductor technology.
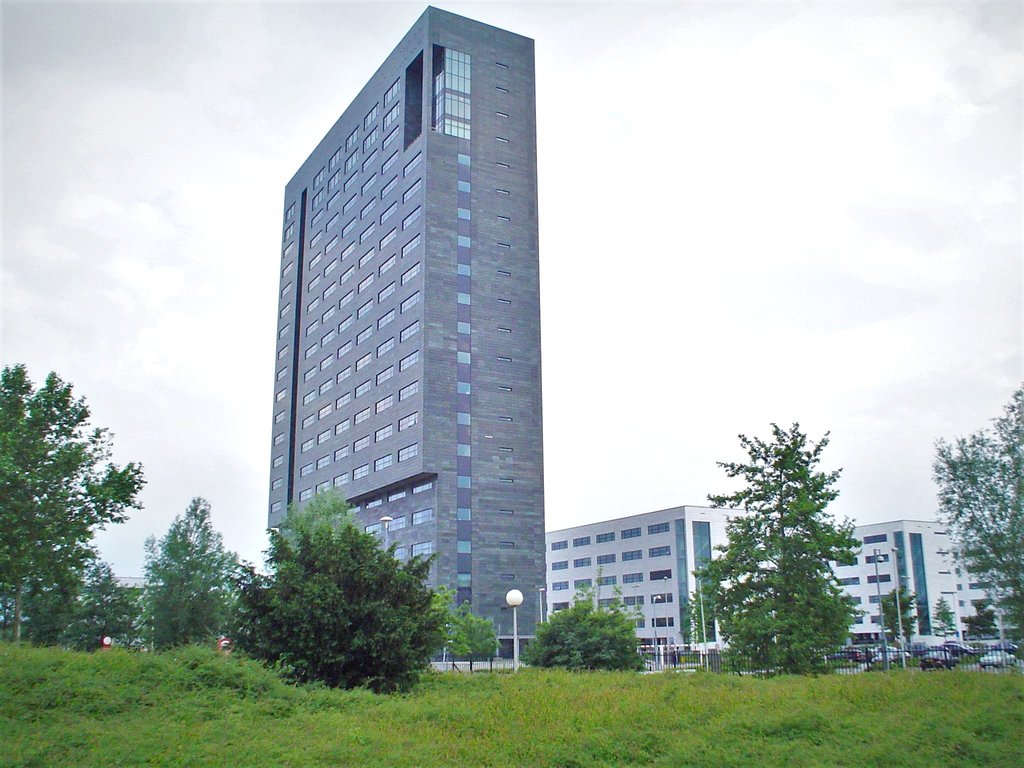
ASML's corporate headquarters are in Veldhoven, near Eindhoven, in the Netherlands, where the company conducts research and development and manufactures and assembles its products. Additionally the company has offices in more than a dozen countries. ASML employs more than 42,000 people and has a network of nearly 5,000 direct suppliers.
History
Background
ASML can be traced back to the 1970s and the Dutch electronics company Philips. The firm, having observed that the wider electronics industry had been struggling to shrink features without losing accuracy or letting contamination/flaws increase, decided to develop its own prototype lithography machines, harnessing Philips' established knowledge in the fields of optics and precision mechanics. By the early 1980s, Philips had projected that considerable additional investment would be necessary to complete its development, but this need came at a time in which the company was trying to reduce expenditure. Accordingly, in 1984, the company elected to spin-off its lithography machine activities into a joint venture with another Dutch firm, ASM International, which specialised in the supply of equipment to the semiconductor industry.
The new entity used a different business strategy to established competitors; lacking the capital, time, and expertise to realistically pursue vertical integration, instead, the joint venture opted to outsource various major components, including motors and optics, to other parties so that it could dedicate its resources and attention on the assembly and optimisation of the final machine. This decision shaped the machine as well, which adopted a modular design and used clearly defined subsystems. Early on, ASML struggled to secure business, having no market share and no brand recognition at the start of its operations. Furthermore, the firm's first product, the PAS 2000, was a commercial and technical failure, having used oil pressure (instead of electric motors) to move the wafer during exposure, which had a tendency to leak; future lithograph machines made by ASML would use conventional electric motors instead.
The design was improved shortly after, using electric motors and, as one of the first contribution of a newly hired Martin van den Brink, a grid profile to improve the precision of the alignment. The resulting PAS 2400 wasn't as accurate as ASML was hoping for, but it could expose 90 wafers per hour, and it was used as a demonstrator in 1985 to win a first contract with AMD that promised to deliver 25 machines by 1987. In 1986, the company, which had grown from 17 employees to over 200, delivered the first truly competitive wafer stepper to Philips: the PAS 2500. This model was the result of ASML's new policy of splitting the design into modular subsystems and outsourcing the manufacturing as much as possible; for instance, it was equipped with a standard lens from Carl Zeiss.
Independence and commercial breakout
By the start of 1988, Philips was reportedly considered shutting down the joint venture entirely after ASM International pulled out. However, sufficient support was present on Philip's board to continue with operations, giving ASML the time to develop another lithography machine, the PAS 5500. Accordingly, in 1988, ASML became an independent publicly traded entity; that same year, it first adopted the name ASML, which is its official name and not an abbreviation.
In 1991, ASML released the PAS 5500, which quickly became the company's first commercial breakout. In contrast to the more precise contemporary lithography machines from competing firm Nikon, the modular design used by ASML meant that its machines could be fixed quickly on site, reducing downtime and making it possible to extend the machine’s operating life. The serviceability advantage was reportedly the key factor that led to IBM ordering the PAS 5500 over its Japanese counterparts. The first company to operate the PAS 5500 was Micron Technology, one of the world's largest producers of computer memory and storage; it became ASML's largest customer for a time. The success of the PAS 5500 line propelled ASML into a period of intense competition with both Canon and Nikon, who were the leaders of the lithography market at the time.
In 1997, ASML began studying a shift to using extreme ultraviolet. Two years later, it joined a consortium, which included Intel and two other U.S. chipmakers, in order to exploit fundamental research conducted by the US Department of Energy. Because the Cooperative Research and Development Agreement (CRADA) it operates under is funded by the US government, licensing must be approved by Congress. Furthermore, in return for being permitted to join this consortium, ASML committed to the establishment of a US-based research center and to source 55 percent of components for all machines sold in the US from American suppliers. ASML collaborated with various manufacturers to obtain mirrors, including the Belgian firms IMEC and Sematech as well as Germany's Carl Zeiss.
2000s
In 2001, ASML acquired the US-based lithography equipment manufacturer Silicon Valley Group (SVG) after it had encountered liquidity issues, The SVG acquisition, which has also been licensed for EUV research results, involved ASML in an arrangement to supply 193 nm scanners to Intel.
In 2002, it became the largest supplier of photolithography systems. Aided by the adoption of the dual-stage TWINSCAN architecture to reduce idle time, ASML machines could produce more chips per hour than any competitor's products; this competitive edge was so strong that the company could charge higher prices for their machines and still grow its market share. By the end of the decade, it had secured two thirds of the global lithography market and had become the dominant supplier for the growing smartphone market.
During December 2006, ASML announced the acquisition of rival firm BRION Technologies in exchange for $270 million; this transaction brought the company into direct competition with the major Electronic design automation (EDA) vendors who had similar products - Cadence Design Systems, Synopsys, and Mentor Graphics.
During late 2008, following the start of the Great Recession, ASML experienced a large drop in sales, which led management to cut the workforce by about 1000 worldwide, mainly at its headquarters in the Netherlands as well its Connecticut manufacturing plant; additionally, the firm applied for support from the Dutch national unemployment fund to prevent even larger layoffs. ASML had recovered by 2011, reporting record-high revenue for that year.
2010s
During the early 2010s, ASML sharply increased its annual R&D budget, rising from just under $500 million in 2010 to $1 billion in 2015. While this expenditure was necessary in order to complete the development of its next generation EUV machines, financing such amounts was not straightforward. To achieve this, ASML launched a co-investment program in 2012, under which 23 percent of the company was sold to its three largest customers: Intel, TSMC and Samsung. Intel's investment of $4.1 billion into ASML, made in July 2012, gave it a 15 percent stake in the company; this move was stated to accelerate Intel's transition from 300 mm to 450 mm wafers as well as support further development of EUV lithography. That same month, ASML offered another 10 percent of its shares to other companies.
Beyond simply generating additional funds, these new stakeholders were incentivised to participate in ASML's research efforts. TSMC in particular worked closely with ASML to develop and troubleshoot its EUV machines, being keen to use them to manufacture their own products. As part of their EUV strategy, ASML announced the acquisition of DUV and EUV sources manufacturer Cymer in exchange for $2.55 billion in October 2012; this transaction was completed in May 2013. Cymer's technology was viewed as being useful to developing ASML's EUV machines.
In November 2013, ASML paused development of 450 mm lithography equipment, citing uncertain timing of chipmaker demand.
In early 2015, ASML reported an instance of intellectual property theft; allegedly a number of employees had been found stealing confidential data from its Silicon Valley software subsidiary that develops software for machine optimization. Three years later, ASML was awarded $223 million in damages pertaining to this incident, as well as securing the offending company's own intellectual property. ASML employees have often been viewed as highly desirable recruitment targets for other tech companies.
In June 2016, ASML announced their plans to acquire Taiwan-based Hermes Microvision Inc. in exchange for about $3.1 billion; it was reported that this transaction would secure technology for creating smaller and more advanced semiconductors.
In 2018, the Trump administration tried to block the sale of ASML technology to China. This move, which has been viewed as part of a wider "technological cold war" between the US and China, may have contributed to the 2020–2023 global chip shortage and impacted the business opportunities available to ASML.
2020s
Throughout the late 2010s and early 2020s, ASML experienced a period of steady revenue growth, rising from $13 billion in 2018 up to $35 billion in 2024; this has been largely credited to the firm's EUV machines, which have received a significant surge in demand during this period, driven by modern electronics' increasing complexity and performance requirements. In July 2020, ASML stated that it had acquired the German optical glassmaking firm Berliner Glas Group, which will help to satisfy the increasing need for components for its EUV systems; at the time of this acquisition, ASML's outstanding orders had reportedly risen to €10 billion.
In July 2021, European Commissioner Thierry Breton, visited ASML and announced a goal of at least 20 percent of global production of semiconductors in Europe by 2030, and support via a European Alliance on semiconductors. After reporting earnings in July 2021, the company said they had a near monopoly for machines used by TSMC and Samsung to make the advanced chips.
In February 2023, ASML claimed that a former worker in China "allegedly" stole information about the company's technology. This was not the first time that ASML was allegedly linked with an intellectual property breach connected to China. In its 2021 annual report, ASML mentioned that Dongfang Jingyuan Electron Limited "was actively marketing products in China that could potentially infringe on ASML's IP rights." At the time, the United States Department of Commerce expressed concern about economic espionage against ASML. In October 2023, Dutch newspaper NRC Handelsblad reported that the former employee who "allegedly" stole data about ASML's technology subsequently went to work for Huawei.
In March 2023, the Dutch government placed restrictions on chip equipment exports in order to protect national security. This measure affected ASML as one of the most important companies in the global microchip supply chain. Export license requirements came into effect in September 2023. Three months later, the Netherlands' Institute for Human Rights ruled that despite the country's constitution prohibiting discrimination based on nationality, ASML was allowed to reject job applications from residents of countries subject to sanctions under the U.S. Export Administration Regulations (such as China, Cuba, Iran, North Korea, and Syria) in order to remain compliant with U.S. law.
In January 2024, the Dutch government placed further restrictions on the shipment of some advanced chip-making equipment to China. On 6 September 2024, the Dutch government tightened export controls on certain ASML chipmaking equipment, aligning its policy with U.S. restrictions to limit China's access to advanced technology amid safety and geopolitical concerns. These restrictions were expanded for tighter export controls in January 2025, with ASML required to apply for export licenses with the Dutch government instead of the U.S. In December 2025, Reuters reported that China had secretly built a prototype EUV machine in Shenzhen with the assistance of former ASML engineers, with the machine expected to produce working chips between 2028 and 2030.
Products
ASML produces the photolithography machines used in the production of integrated circuits, called "scanners". In these machines, patterns are optically imaged onto a silicon wafer that is covered with a film of light-sensitive material (photoresist). This procedure is repeated dozens of times on a single wafer. The photoresist is then further processed to create the actual electronic circuits on the silicon. The optical imaging that ASML's machines deal with is used in the fabrication of nearly all integrated circuits. As of 2025, ASML had 83% percent of the worldwide sales of lithography machines.
ASML's earlier competition consisted of Ultratech, Canon, Nikon, MKS Instruments, Lam Research and Cadence Design Systems.
Immersion lithography
Since immersion lithography was first proposed by Burn-Jeng Lin in the 1970s, ASML cooperated with TSMC. In 2004, TSMC began commercial production of 90 nanometer semiconductor nodes using ASML immersion lithography. By 2011, their high-end TWINSCAN NXT:1950i system was used for producing features down to 32 nanometres at up to 200 wafers per hour, using a water immersion lens and an argon fluoride laser that produces light at a wavelength of 193 nm. By 2011, an average lithography machine cost €27 million.
DUV lithography
Deep ultraviolet lithography (DUV) devices from ASML use ultraviolet light to print the tiny features that form the microchip's structure.
EUV lithography
Extreme ultraviolet lithography (EUV) is a critical technology used to create the smallest and most complex chip designs. ASML holds a near-monopoly in the EUV market. The company's machines are capable of exposing patterns as small as 8 nanometers wide, about 1/10,000 the width of a human hair.
EUV machines produce light in the 13.5 nm wavelength range by focusing a high-energy laser on microscopic droplets of molten tin to produce a plasma, which then emits EUV light. The light is bounced off Zeiss mirrors onto the surface of a silicon wafer to form the designs for the chip.
In 2009, the IMEC research center in Belgium produced the world's first functional 22 nm CMOS Static random-access memory memory cells with a prototype EUV lithography machine. ASML shipped the first pre-production EUV machine in 2013 and, after two decades of development, started shipping production EUV machines in 2018. Samsung shipped the first EUV-enabled commercial product in 2019.
As of 2022, ASML has shipped around 140 EUV systems. ASML's best-selling EUV product has been the TWINSCAN NXE:3600D, which costs up to $200 million. The machine weighs 180 tons and needs three Boeing 747s to transport.
ASML is working on the next generation of EUV systems, with the first shipments for R&D shipped to Intel in December 2023, and TSMC in late 2024. The platform is designated High-NA as it increases the numerical aperture (NA) from 0.33 to 0.55. each system costs approximately $370 million.
Sponsorships
ASML became a sponsor of the PSV football club in 2019 together with Philips, VDL Groep, Royal Swinkels Family Brewers and Jumbo Supermarkets from the Brainport region. Together they run various initiatives like soccer training camps for school children, the development of interactive programs for teaching, assisting community members in need or who are new to the region, as well as supporting a vitality program that is online. ASML was the title partner of the Eindhoven marathon from 2022 - 2024.
Awards
The IEEE Spectrum Emerging Technology 2018 Award was given to ASML for its Extreme Ultraviolet Lithography system. ASML is currently the top supplier of photolithography systems to the semiconductor industry.
In the category for Popular Prize, Vadim Banine received the 2018 European Inventor Award for shaping the future of microchip manufacturing.
The largest independent microelectronics research center in Europe is called IMEC (Interuniversity Micro Electronics Centre). Martin van den Brink of ASML was given the 2019 IMEC Lifetime of Innovation Award.
The Netherlands Association for Investor Relations (NEVIR), where listed companies and professionals in investor relations had the chance to be recognized for their outstanding work in the sector, presented awards to ASML in the categories: "Best Company in the field of Investor Relations" during the Dutch IR Awards 2019 annual award ceremony.
ASML received the SEMI Americas Award at the 2020 edition of the microelectronics conference SEMICON West for its collaborative approach to extreme ultraviolet lithography (EUV), which helped it become commercially viable and opened the door to new technological possibilities.
The Intel Preferred Quality Supplier (PQS) Award for 2020 was awarded to ASML. ASML has attained a level of performance that continuously surpasses Intel's expectations for the commitment to continual quality improvement.
The Dutch Innovation Prize 2021 was awarded to ASML at the 4th National BID AVROTROS Innovation Dinner held at Kasteel Wittenburg in Wassenaar.
ASML received the first CoSta Award for the most successful and impactful innovative partnership between a corporate company and a startup.
Source: Wikipedia, CC BY-SA 4.0 · View on Wikipedia ↗
10-Year Performance Revenue, net income, margins and EPS trends
Valuation P/E, P/S, P/B, EV/EBITDA ratios — is the stock expensive or cheap?
| Metric | 5Y trend | ASML | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| P/E | 75.65Y avg ≈42.3 | ≈42.3 | · | · | |
| P/S | 22.05Y avg ≈12.1 | ≈12.1 | · | · | |
| P/B | 36.75Y avg ≈22.8 | ≈22.8 | · | · | |
| EV / EBITDA | 57.75Y avg ≈32.7 | ≈32.7 | · | · | |
| Price / FCF | 64.95Y avg ≈44.0 | ≈44.0 | · | · | |
| Price / Cash Flow | 56.95Y avg ≈33.3 | ≈33.3 | · | · | |
| EV / Revenue | 21.85Y avg ≈11.9 | ≈11.9 | · | · | |
| EV / FCF | 64.25Y avg ≈43.4 | ≈43.4 | · | · | |
| Price / Tangible Book | 49.55Y avg ≈43.6 | ≈43.6 | · | · |
Peer median is calculated on a standardized basis per metric and may not always match the TTM/MRQ basis shown for this stock.
Profitability Gross, operating and net margins; ROE, ROA, ROIC
| Metric | 5Y trend | ASML | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Gross Margin | 52.8%5Y avg ≈51.7% | ≈51.7% | · | · | |
| Operating Margin | 34.6%5Y avg ≈33.3% | ≈33.3% | · | · | |
| EBITDA Margin | 37.7%5Y avg ≈36.1% | ≈36.1% | · | · | |
| Pretax Margin | 34.9%5Y avg ≈33.3% | ≈33.3% | · | · | |
| Net Profit Margin | 29.4%5Y avg ≈28.6% | ≈28.6% | · | · | |
| ROA | 19.4%5Y avg ≈18.9% | ≈18.9% | · | · | |
| ROE | 50.5%5Y avg ≈55.3% | ≈55.3% | · | · | |
| ROIC | 38.8%5Y avg ≈38.7% | ≈38.7% | · | · |
Financial Health Debt, liquidity, solvency — balance sheet strength
| Metric | 5Y trend | ASML | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Debt / Equity | 0.25Y avg ≈0.4 | ≈0.4 | · | · | |
| Current Ratio | 1.35Y avg ≈1.4 | ≈1.4 | · | · | |
| Quick Ratio | 0.75Y avg ≈0.7 | ≈0.7 | · | · | |
| Long-Term Debt / Equity | 0.15Y avg ≈0.3 | ≈0.3 | · | · |
Growth Revenue, EPS and net income growth: YoY, 3Y CAGR, 5Y CAGR
Not enough fundamentals data to compute this ratio group yet.
Capital Efficiency Asset turnover, inventory turnover, receivables turnover
| Metric | 5Y trend | ASML | 5Y avg | Peer Median | Verdict |
|---|---|---|---|---|---|
| Asset Turnover | 0.75Y avg ≈0.7 | ≈0.7 | · | · | |
| Inventory Turnover | 1.45Y avg ≈1.6 | ≈1.6 | · | · | |
| Receivables Turnover | 8.75Y avg ≈6.9 | ≈6.9 | · | · | |
| Revenue / Employee | ≈$743.5K | · | · | · |
value · ≈ 5Y avg · industry median · verdict relative to median
Dividends Yield, payout ratio, dividend history, 5Y CAGR
| Ex-date | Amount | Currency | Yield |
|---|---|---|---|
| Jul 28, 2026 | $2.14 | USD | ≈0.57% |
| Apr 27, 2026 | $3.18 | USD | ≈0.61% |
| Feb 10, 2026 | $1.88 | USD | ≈0.54% |
| Oct 29, 2025 | $1.86 | USD | ≈0.69% |
| Jul 29, 2025 | $1.85 | USD | ≈1.00% |
| Apr 28, 2025 | $2.09 | USD | ≈1.0% |
| Feb 11, 2025 | $1.57 | USD | ≈0.89% |
| Oct 29, 2024 | $1.64 | USD | ≈0.94% |
| Jul 29, 2024 | $1.64 | USD | ≈0.76% |
| Apr 26, 2024 | $1.87 | USD | ≈0.71% |
| Feb 5, 2024 | $1.56 | USD | ≈0.73% |
| Nov 1, 2023 | $1.53 | USD | ≈1.1% |
| Aug 1, 2023 | $1.59 | USD | ≈0.88% |
| May 1, 2023 | $1.86 | USD | ≈1.6% |
| Feb 6, 2023 | $1.47 | USD | ≈1.2% |
| Nov 3, 2022 | $1.34 | USD | ≈1.5% |
| Aug 4, 2022 | $1.40 | USD | ≈1.3% |
| May 3, 2022 | $3.90 | USD | ≈1.0% |
| Nov 2, 2021 | $2.08 | USD | ≈0.49% |
| May 3, 2021 | $1.87 | USD | ≈0.50% |
Earnings History EPS actual vs estimate, surprise %, beat rate, next earnings date
| Period | Report | EPS Actual | EPS Est | Surprise |
|---|---|---|---|---|
| June 30, 2026 | $7.58 | $6.93 | 9.4% | |
| March 31, 2026 | $7.15 | $6.67 | 7.1% | |
| Dec. 31, 2025 | $7.34 | $7.71 | -4.8% | |
| Sept. 30, 2025 | $5.48 | $5.56 | -1.4% | |
| June 30, 2025 | $5.90 | $5.30 | 11.2% | |
| March 31, 2025 | $7.34 | $7.71 | -4.8% |
Full Fundamentals All metrics by year — income statement, balance sheet, cash flow
Income Statement
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $32.67B | $28.26B | $27.56B | $21.17B | $18.61B | $13.98B | $11.82B | $10.94B | $8.96B | $6.88B | $6.29B | $5.86B | |
| Cost of Revenue | $15.41B | $13.77B | $13.42B | $10.47B | $8.80B | $7.18B | $6.54B | $5.91B | $4.94B | $3.73B | $3.39B | $3.26B | |
| Gross Profit | $17.26B | $14.49B | $14.14B | $10.70B | $9.81B | $6.80B | $5.28B | $5.03B | $4.02B | $3.15B | $2.90B | $2.60B | |
| R&D Expense | $4.70B | $4.30B | $3.98B | $3.25B | $2.55B | $2.20B | $1.97B | $1.58B | $1.26B | · | · | $1.07B | |
| SG&A Expense | $1.26B | $1.17B | $1.11B | $946M | $726M | $545M | $520M | $488M | $417M | $375M | $346M | $321M | |
| Operating Income | $11.30B | $9.02B | $9.04B | $6.50B | $6.75B | $4.05B | $2.79B | $2.97B | $2.44B | $1.76B | $1.57B | $1.28B | |
| Interest Expense | · | · | $153M | $61M | $55M | $43M | $37M | $42M | $58M | $38M | $27M | $23M | |
| Interest Income | $223M | $182M | $194M | $16M | $10M | · | · | · | · | · | · | · | |
| Pretax Income | $11.41B | $9.04B | $9.08B | $6.46B | $6.71B | $4.02B | $2.77B | $2.94B | $2.39B | $1.79B | $1.55B | $1.27B | |
| Income Tax | $2.01B | $1.68B | $1.44B | $970M | $1.02B | $552M | $192M | $352M | $306M | $234M | $161M | $77M | |
| Net Income | $9.61B | $7.57B | $7.84B | $5.62B | $5.88B | $3.55B | $2.59B | $2.59B | $2.07B | $1.56B | $1.39B | $1.20B | |
| EPS (Basic) | $24.73 | $19.25 | $19.91 | $14.14 | $14.36 | $8.49 | $6.16 | $6.10 | $4.81 | $3.66 | $3.22 | $2.74 | |
| EPS (Diluted) | $24.71 | $19.24 | $19.89 | $14.13 | $14.34 | $8.48 | $6.15 | $6.08 | $4.79 | $3.64 | $3.21 | $2.72 | |
| Shares (Basic) | 388,500,000 | 393,300,000 | 393,800,000 | 397,700,000 | 409,800,000 | 418,300,000 | 420,800,000 | 424,900,000 | 429,800,000 | 425,600,000 | 430,600,000 | 437,142,000 | |
| Shares (Diluted) | 388,900,000 | 393,600,000 | 394,100,000 | 398,000,000 | 410,400,000 | 419,100,000 | 421,600,000 | 426,400,000 | 431,600,000 | 427,700,000 | 432,600,000 | 439,693,000 | |
| EBITDA | $12.33B | $9.94B | $9.78B | $7.08B | $7.22B | $4.54B | $3.24B | $3.39B | $2.91B | $2.01B | $1.86B | $1.54B |
Balance Sheet
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $12.92B | $12.74B | $7.00B | $7.27B | $6.95B | $6.05B | $3.53B | $3.12B | $2.26B | $2.91B | $2.46B | $2.42B | |
| Short-term Investments | · | · | · | · | · | $1.30B | $1.19B | $913M | $1.03B | $1.15B | $950M | $335M | |
| Receivables | $3.02B | $4.48B | $4.33B | $5.32B | $3.03B | $1.31B | $1.79B | $1.50B | $1.74B | $700M | $804M | $1.05B | |
| Inventory | $11.43B | $10.89B | $8.85B | $7.20B | $5.18B | $4.57B | $3.81B | $3.44B | $2.96B | $2.78B | $2.57B | $2.55B | |
| Prepaid Expense | $1.43B | $1.94B | $1.58B | $1.64B | $1.00B | $802M | $843M | $773M | $510M | $560M | $489M | $390M | |
| Other Current Assets | $350M | $193M | $92M | $266M | $149M | $93M | $131M | $84M | $78M | $89M | $34M | $39M | |
| Current Assets | $30.62B | $30.74B | $24.39B | $23.06B | $18.19B | $15.93B | $12.13B | $10.53B | $8.89B | $8.56B | $7.71B | $7.15B | |
| PP&E (Net) | $7.89B | $6.85B | $5.49B | $3.94B | $2.98B | $2.47B | $2.00B | $1.59B | $1.60B | $1.69B | $1.62B | $1.45B | |
| PP&E (Gross) | $12.82B | $11.06B | $9.08B | $6.99B | $5.62B | $5.02B | $4.30B | $3.71B | $3.43B | $3.30B | $3.01B | $2.60B | |
| Goodwill | $4.59B | $4.59B | $4.59B | $4.56B | $4.56B | $4.63B | $4.54B | $4.54B | $4.54B | $4.87B | $2.62B | $2.36B | |
| Intangibles | $486M | $621M | $742M | $842M | $952M | $1.05B | $1.10B | $1.10B | $1.17B | $1.32B | $738M | $724M | |
| Other Non-current Assets | $13M | $28M | $14M | $16M | $15M | $15M | $19M | $19M | $24M | $22M | $20M | $5M | |
| Total Assets | $50.57B | $48.59B | $39.96B | $36.30B | $30.23B | $27.27B | $22.63B | $20.14B | $18.19B | $17.21B | $13.30B | $12.20B | |
| Accounts Payable | $3.52B | $3.50B | $2.35B | $2.57B | $2.12B | $1.38B | $1.06B | $964M | $837M | $593M | $528M | $496M | |
| Current Liabilities | $24.26B | $20.05B | $16.27B | $17.98B | $12.30B | $6.60B | $4.69B | $3.79B | $3.17B | $3.28B | $3.11B | $2.89B | |
| Capital Leases | · | · | · | · | $118M | $130M | $154M | $94M | $81M | · | · | · | |
| Deferred Tax | · | · | · | · | · | · | · | $42M | $192M | $278M | $160M | $154M | |
| Other Non-current Liabilities | $432M | $460M | $401M | $455M | $251M | $258M | $241M | $202M | $279M | $616M | $414M | $412M | |
| Total Liabilities | $30.95B | $30.11B | $26.51B | $27.49B | $20.09B | $13.40B | $10.04B | $8.50B | $7.41B | $7.39B | $4.91B | $4.69B | |
| Long-term Debt | $4.39B | $4.69B | $4.63B | $4.26B | $4.58B | $4.68B | $3.11B | $3.01B | $3.04B | $3.28B | $1.03B | $1.04B | |
| Total Debt | $4.39B | $4.69B | $4.63B | $4.26B | $4.58B | $4.68B | $3.11B | $3.01B | $3.01B | $3.04B | $1.03B | $1.04B | |
| Common Stock | · | · | · | · | · | · | $39M | $39M | $39M | · | · | · | |
| Retained Earnings | $17.59B | $14.41B | $12.38B | $9.05B | $8.32B | $10.73B | $9.52B | $9.20B | $7.31B | $6.28B | $5.28B | $4.65B | |
| Treasury Stock | $2.25B | $476M | $3.31B | $4.64B | $2.42B | $863M | $1.02B | $1.62B | $558M | $796M | $477M | $389M | |
| AOCI | $136M | $454M | $345M | $428M | $334M | $179M | $278M | $285M | $252M | $601M | $472M | $212M | |
| Stockholders' Equity | $19.61B | $18.48B | $13.45B | $8.81B | $10.14B | $13.87B | $12.59B | $11.64B | $10.69B | $9.97B | $8.45B | $7.51B | |
| Liabilities + Equity | $50.57B | $48.59B | $39.96B | $36.30B | $30.23B | $27.27B | $22.63B | $20.14B | $18.19B | $17.21B | $13.30B | $12.20B | |
| Shares Outstanding | 385,417,665 | 393,283,720 | 393,421,721 | 394,600,000 | 402,600,000 | 416,500,000 | 419,800,000 | 421,100,000 | 427,400,000 | 429,900,000 | 428,000,000 | 432,900,000 |
Cash Flow
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $1.03B | $919M | $740M | $584M | $471M | $491M | $448M | $423M | $418M | $357M | $297M | $255M | |
| Stock-based Comp | $202M | $173M | $135M | $69M | $118M | $54M | $75M | $46M | $53M | $48M | $59M | $63M | |
| Deferred Tax | $16M | $-66M | $-217M | $-527M | $-367M | $-232M | $-232M | $-292M | $-78M | $76M | $45M | $-59M | |
| Amort. of Intangibles | $124M | $126M | $128M | $135M | $133M | $124M | $115M | $104M | $106M | $64M | $51M | $44M | |
| Other Non-cash | $1.80B | $2.57B | $-3.05B | $2.74B | $4.74B | $761M | $393M | $247M | $-734M | $-210M | $237M | $-430M | |
| Operating Cash Flow | $12.66B | $11.17B | $5.44B | $8.49B | $10.85B | $4.63B | $3.28B | $3.07B | $1.82B | $1.67B | $2.03B | $1.03B | |
| CapEx | $1.57B | $2.07B | $2.16B | $1.28B | $901M | $962M | $767M | $574M | $339M | $316M | $372M | $358M | |
| Investing Cash Flow | $-3.78B | $-2.61B | $-2.69B | $-1.03B | $-72M | $-1.35B | $-1.16B | $-492M | $-1.23B | · | · | · | |
| Debt Issued | · | $22M | $998M | $496M | $0 | $1.49B | $0 | $0 | · | · | · | · | |
| Net Debt Issued | · | $22M | $245M | $-21M | $-12M | $1.48B | $-4M | $-3M | $-243M | $-5M | $-4M | $-4M | |
| Stock Repurchased | $5.95B | $500M | $1.00B | $4.64B | $8.56B | $1.21B | $410M | $1.15B | $500M | $400M | $565M | $700M | |
| Net Stock Activity | $-5.95B | $-500M | $-1.00B | $-4.64B | $-8.56B | $-1.21B | $-410M | $-1.15B | $-500M | $-400M | $-565M | $-700M | |
| Dividends Paid | · | · | · | · | · | · | · | $597M | $517M | $446M | $302M | $268M | |
| Financing Cash Flow | $-8.67B | $-2.83B | $-3.00B | $-7.14B | $-9.89B | $-753M | $-1.71B | $-1.72B | $-1.21B | · | · | · | |
| Net Change in Cash | $180M | $5.73B | $-264M | $316M | $902M | $2.52B | $411M | $862M | $-648M | $448M | $39M | $89M | |
| Taxes Paid | $1.62B | $1.10B | $2.57B | $1.73B | $1.24B | $650M | $679M | $554M | $475M | $116M | $127M | $124M | |
| Free Cash Flow | $11.08B | $9.10B | $3.29B | $7.21B | $9.95B | $3.67B | $2.51B | $2.50B | $1.46B | $1.35B | $1.65B | $667M | |
| Levered FCF | · | · | $3.16B | $7.15B | $9.90B | $3.63B | $2.48B | $2.46B | $1.41B | $1.32B | $1.63B | $645M |
Profitability
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gross Margin | 52.8% | 51.3% | 51.3% | 50.5% | 52.7% | 48.6% | 44.7% | 46.0% | 45.0% | 44.8% | 46.1% | 44.3% | |
| Operating Margin | 34.6% | 31.9% | 32.8% | 30.7% | 36.3% | 29.0% | 23.6% | 27.1% | 27.6% | 24.4% | 24.9% | 21.9% | |
| Net Margin | 29.4% | 26.8% | 28.4% | 26.6% | 31.6% | 25.4% | 21.9% | 23.7% | 23.4% | 21.7% | 22.1% | 20.4% | |
| Pretax Margin | 34.9% | 32.0% | 33.0% | 30.5% | 36.0% | 28.7% | 23.4% | 26.8% | 27.0% | 24.9% | 24.6% | 21.8% | |
| EBITDA Margin | 37.7% | 35.2% | 35.5% | 33.5% | 38.8% | 32.5% | 27.4% | 31.0% | 32.2% | 29.6% | 29.6% | 26.2% | |
| ROA | 19.4% | 17.1% | 20.6% | 16.9% | 20.5% | 14.2% | 12.1% | 13.5% | 12.0% | 9.7% | 10.9% | 10.1% | |
| ROE | 50.5% | 47.4% | 70.4% | 59.4% | 49.0% | 26.9% | 21.4% | 23.2% | 20.5% | 16.1% | 17.4% | 16.6% | |
| ROIC | 38.8% | 31.7% | 42.1% | 42.3% | 38.9% | 18.9% | 16.5% | 17.8% | 15.9% | 11.2% | 14.9% | 14.1% |
Liquidity & Solvency
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 1.3 | 1.5 | 1.5 | 1.3 | 1.5 | 2.4 | 2.6 | 2.8 | 2.7 | 2.6 | 2.5 | 2.5 | |
| Quick Ratio | 0.7 | 0.9 | 0.7 | 0.7 | 0.8 | 0.4 | 0.6 | 1.5 | 1.5 | 1.5 | 1.4 | 1.3 | |
| Debt / Equity | 0.2 | 0.3 | 0.3 | 0.5 | 0.5 | 0.3 | 0.2 | 0.3 | 0.3 | 0.3 | 0.1 | 0.1 | |
| LT Debt / Equity | 0.1 | 0.2 | 0.3 | 0.4 | 0.4 | 0.3 | 0.2 | 0.3 | 0.3 | 0.3 | 0.1 | 0.1 | |
| Interest Coverage | · | · | 59.2 | 106.9 | 123.6 | 93.6 | 76.3 | 70.9 | 43.4 | 43.6 | 57.1 | 55.5 |
Efficiency
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.7 | 0.6 | 0.7 | 0.6 | 0.6 | 0.6 | 0.6 | 0.6 | 0.5 | 0.4 | 0.5 | 0.5 | |
| Inventory Turnover | 1.4 | 1.4 | 1.7 | 1.7 | 1.8 | 1.7 | 1.8 | 1.8 | 1.7 | 1.4 | 1.3 | 1.3 | |
| Receivables Turnover | 8.7 | 6.4 | 5.7 | 5.1 | 8.6 | 9.0 | 7.2 | 6.8 | 7.3 | 9.0 | 6.8 | 6.1 |
Per Share
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $50.89 | $46.98 | $34.19 | $22.33 | $25.19 | $33.29 | $30.00 | $27.64 | $24.98 | $22.84 | $19.60 | $17.35 | |
| Revenue / Share | $84.00 | $71.81 | $69.93 | $53.20 | $45.35 | $33.35 | $28.04 | $25.67 | $20.98 | $15.89 | $14.53 | $13.32 | |
| Cash Flow / Share | $32.55 | $28.37 | $13.81 | $21.32 | $26.43 | $11.04 | $7.77 | $7.21 | $4.17 | $3.90 | $4.68 | $2.33 | |
| Cash / Share | $33.51 | $32.38 | $17.80 | $18.42 | $17.27 | · | · | $7.41 | $5.29 | $6.76 | $5.74 | $5.59 | |
| Dividend / Share | · | $6.40 | $6.10 | $5.80 | $5.50 | $2.75 | · | · | · | · | · | · | |
| EPS (TTM) | $24.71 | $19.24 | $19.89 | $14.13 | $14.34 | $8.48 | $6.15 | $6.08 | $4.79 | $3.64 | $3.21 | $2.72 |
Valuation (TTM)
| Metric | Trend | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $32.67B | $28.26B | $27.56B | $21.17B | $18.61B | $13.98B | $11.82B | $10.94B | $8.96B | $6.88B | $6.29B | $5.86B | |
| Net Income TTM | $9.61B | $7.57B | $7.84B | $5.62B | $5.88B | $3.55B | $2.59B | $2.59B | $2.07B | $1.56B | $1.39B | $1.20B | |
| Market Cap | $412.34B | $272.58B | $297.79B | $215.60B | $320.53B | $203.14B | $124.24B | $65.53B | $74.29B | $48.24B | $37.99B | $46.68B | |
| Enterprise Value | $403.82B | $264.53B | $295.42B | $212.60B | $318.16B | · | · | $64.50B | $74.01B | $47.22B | $35.61B | $44.97B | |
| P/E | 43.3 | 36.0 | 38.1 | 38.7 | 55.5 | 57.5 | 48.1 | 25.6 | 36.3 | 30.8 | 27.7 | 39.6 | |
| P/S | 12.6 | 9.6 | 10.8 | 10.2 | 17.2 | 14.5 | 10.5 | 6.0 | 8.3 | 7.0 | 6.0 | 8.0 | |
| P/B | 21.0 | 14.8 | 22.1 | 24.5 | 31.6 | 14.7 | 9.9 | 5.6 | 7.0 | 4.9 | 4.5 | 6.2 | |
| P / Tangible Book | 28.4 | 20.5 | 36.7 | 63.2 | 69.2 | 24.8 | · | · | · | · | · | · | |
| P / Cash Flow | 32.6 | 24.4 | 54.7 | 25.4 | 29.6 | 43.9 | 37.9 | 21.3 | 41.3 | 29.0 | 18.8 | 45.5 | |
| P / FCF | 37.2 | 30.0 | 90.6 | 29.9 | 32.2 | 55.4 | 49.5 | 26.2 | 50.9 | 35.7 | 23.0 | 70.0 | |
| EV / EBITDA | 32.8 | 26.6 | 30.2 | 30.0 | 44.1 | · | · | 19.0 | 25.4 | 23.4 | 19.1 | 29.3 | |
| EV / FCF | 36.4 | 29.1 | 89.9 | 29.5 | 32.0 | · | · | 25.8 | 50.7 | 35.0 | 21.5 | 67.4 | |
| EV / Revenue | 12.4 | 9.4 | 10.7 | 10.0 | 17.1 | · | · | 5.9 | 8.3 | 6.9 | 5.7 | 7.7 | |
| Dividend Yield | · | · | · | · | · | · | · | 0.91% | 0.70% | 0.92% | 0.80% | 0.57% | |
| Earnings Yield | 2.3% | 2.8% | 2.6% | 2.6% | 1.8% | 1.7% | 2.1% | 3.9% | 2.8% | 3.2% | 3.6% | 2.5% | |
| Payout Ratio | · | · | · | · | · | · | · | 23.0% | 24.4% | 30.3% | 21.8% | 22.4% | |
| Annual Payout | · | · | · | · | · | · | · | $597M | $517M | $446M | $302M | $268M |
Per Share
| Metric | Trend | Q4 2010 | Q4 2009 | Q4 2008 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 | Q4 2001 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| EPS (TTM) | $2.33 | $-0.35 | $0.74 | $1.41 | · | · | · | · | · | · |
Valuation (TTM)
| Metric | Trend | Q4 2010 | Q4 2009 | Q4 2008 | Q4 2007 | Q4 2006 | Q4 2005 | Q4 2004 | Q4 2003 | Q4 2002 | Q4 2001 |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $4.51B | $1.60B | $2.95B | $3.77B | · | · | · | · | · | · | |
| Net Income TTM | $1.02B | $-151M | $322M | $671M | · | · | · | · | · | · | |
| P/E | 21.4 | -126.5 | 31.7 | 28.8 | · | · | · | · | · | · | |
| Earnings Yield | 4.7% | -0.79% | 3.1% | 3.5% | · | · | · | · | · | · | |
| Annual Payout | $87M | $86M | $108M | $0 | · | · | · | · | · | · |
Most recent period on the left · null values shown as ·
Financial Statements Income statement, balance sheet, cash flow — annual, last 5 years
| Metric | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Revenue | $32.67B | $28.26B | $27.56B | $21.17B | $18.61B |
| Gross Margin % | 52.8% | 51.3% | 51.3% | 50.5% | 52.7% |
| Operating Margin % | 34.6% | 31.9% | 32.8% | 30.7% | 36.3% |
| Net Income | $9.61B | $7.57B | $7.84B | $5.62B | $5.88B |
| Diluted EPS | $24.71 | $19.24 | $19.89 | $14.13 | $14.34 |
| Metric | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Debt / Equity | 0.2 | 0.3 | 0.3 | 0.5 | 0.5 |
| Current Ratio | 1.3 | 1.5 | 1.5 | 1.3 | 1.5 |
| Quick Ratio | 0.7 | 0.9 | 0.7 | 0.7 | 0.8 |
| Metric | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Free Cash Flow | $11.08B | $9.10B | $3.29B | $7.21B | $9.95B |
Institutional owners (13F) 2,695 filers · $164.0B total · As of Sept. 30, 2026
Institutions that report holding this stock in their quarterly SEC Form 13F. Long positions only; a single filer may appear twice for separate option legs. Large offsetting put/call legs typically reflect market-making or hedged inventory, not directional conviction.
| New positions | Exited positions | Increased | Decreased | Net shares change |
|---|---|---|---|---|
| 435 (+68 vs prior Q) | 93 (-7 vs prior Q) | 933 (+129 vs prior Q) | 811 (+23 vs prior Q) | +3.6M |
Compared to Q1 2026. SEC Form 13F filings are due within 45 days of quarter-end plus a short buffer for late filers — quarters still inside that window are skipped in favor of the most recent fully-reported pair.
| Institution | Value | Shares | % of tracked 13F | Type |
|---|---|---|---|---|
| FMR LLC | $10,898,828,806 | 5,478,341 | 6.65% | Shares |
| Fisher Asset Management, LLC | $9,425,199,953 | 4,737,614 | 5.75% | Shares |
| Capital World Investors | $7,408,061,436 | 3,726,679 | 4.52% | Shares |
| Invesco Ltd. | $6,247,254,210 | 3,140,208 | 3.81% | Shares |
| STATE FARM MUTUAL AUTOMOBILE INSURANCE CO | $5,487,219,693 | 2,758,173 | 3.35% | Shares |
| VAN ECK ASSOCIATES CORP | $4,892,868,525 | 2,459,420 | 2.98% | Shares |
| Capital International Investors | $4,804,665,620 | 2,439,219 | 2.93% | Shares |
| JPMORGAN CHASE & CO | $4,511,671,022 | 2,395,859 | 2.75% | Shares |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $3,654,402,336 | 1,836,900 | 2.23% | Put option |
| MORGAN STANLEY | $3,557,702,292 | 1,788,291 | 2.17% | Shares |
| BANK OF AMERICA CORP /DE/ | $3,306,830,984 | 1,662,192 | 2.02% | Shares |
| SUSQUEHANNA INTERNATIONAL GROUP, LLP | $3,141,524,704 | 1,579,100 | 1.92% | Call option |
| ARROWSTREET CAPITAL, LIMITED PARTNERSHIP | $2,912,352,596 | 1,463,906 | 1.78% | Shares |
| CITADEL ADVISORS LLC | $2,858,029,504 | 1,436,600 | 1.74% | Put option |
| WCM INVESTMENT MANAGEMENT, LLC | $2,728,632,941 | 1,449,003 | 1.66% | Shares |
| BlackRock, Inc. | $2,550,839,967 | 1,282,190 | 1.56% | Shares |
| JANE STREET GROUP, LLC | $2,223,398,144 | 1,117,600 | 1.36% | Put option |
| DIMENSIONAL FUND ADVISORS LP | $2,181,016,069 | 1,096,493 | 1.33% | Shares |
| CITADEL ADVISORS LLC | $1,897,129,984 | 953,600 | 1.16% | Call option |
| WELLINGTON MANAGEMENT GROUP LLP | $1,847,270,638 | 928,538 | 1.13% | Shares |
| Clearbridge Investments, LLC | $1,781,404,688 | 895,430 | 1.09% | Shares |
| GOLDMAN SACHS GROUP INC | $1,672,998,070 | 840,939 | 1.02% | Shares |
| FRANKLIN RESOURCES INC | $1,595,180,440 | 801,824 | 0.97% | Shares |
| NEUBERGER BERMAN GROUP LLC | $1,499,936,208 | 754,422 | 0.91% | Shares |
| NORTHERN TRUST CORP | $1,459,321,881 | 733,534 | 0.89% | Shares |
| WELLS FARGO & COMPANY/MN | $1,430,376,710 | 718,985 | 0.87% | Shares |
| FIRST MANHATTAN CO. LLC. | $1,429,229,612 | 718,408 | 0.87% | Shares |
| ROYAL BANK OF CANADA | $1,425,726,000 | 716,647 | 0.87% | Shares |
| UBS Group AG | $1,241,136,018 | 623,862 | 0.76% | Shares |
| Fayez Sarofim & Co | $1,166,541,622 | 586,367 | 0.71% | Shares |
| LONE PINE CAPITAL LLC | $1,132,337,523 | 569,174 | 0.69% | Shares |
| Point72 Asset Management, L.P. | $1,103,464,780 | 554,661 | 0.67% | Shares |
| SANDS CAPITAL MANAGEMENT, LLC | $1,061,750,202 | 533,693 | 0.65% | Shares |
| ALLIANCEBERNSTEIN L.P. | $1,010,726,853 | 765,221 | 0.62% | Shares |
| VICTORY CAPITAL MANAGEMENT INC | $947,094,463 | 476,010 | 0.58% | Shares |
| JANE STREET GROUP, LLC | $927,079,040 | 466,000 | 0.57% | Call option |
| TWO SIGMA INVESTMENTS, LP | $918,136,507 | 461,505 | 0.56% | Shares |
| ENVESTNET ASSET MANAGEMENT INC | $876,782,888 | 440,721 | 0.53% | Shares |
| AXIOM INVESTORS LLC /DE | $864,918,987 | 434,755 | 0.53% | Shares |
| EDGEWOOD MANAGEMENT LLC | $860,858,540 | 432,714 | 0.52% | Shares |
| EAGLE CAPITAL MANAGEMENT LLC | $743,880,300 | 373,914 | 0.45% | Shares |
| AMERICAN CENTURY COMPANIES INC | $739,921,065 | 371,924 | 0.45% | Shares |
| PRIMECAP MANAGEMENT CO/CA/ | $699,439,357 | 351,576 | 0.43% | Shares |
| REGENTS OF THE UNIVERSITY OF CALIFORNIA | $698,854,462 | 351,282 | 0.43% | Shares |
| CIBC Bancorp USA Inc. | $694,314,234 | 348,738 | 0.42% | Shares |
| Winslow Capital Management, LLC | $693,033,361 | 348,356 | 0.42% | Shares |
| BNP PARIBAS FINANCIAL MARKETS | $681,570,208 | 342,594 | 0.42% | Shares |
| CITIGROUP INC | $649,238,631 | 326,342 | 0.40% | Shares |
| Value Aligned Research Advisors, LLC | $637,814,464 | 320,600 | 0.39% | Call option |
| BROWN ADVISORY INC | $621,660,400 | 312,480 | 0.38% | Shares |
ETF ownership Held by 64 ETFs
Weight reflects direct equity holdings (N-PORT) only; leveraged or derivative-based funds may hold additional swap exposure not shown.
| Fund | Weight | Units | As of | Source |
|---|---|---|---|---|
| EWN · iShares, Inc. | 22.31% | 84,734 SH | Sept. 11, 2026 | Daily |
| IDMO · Invesco Exchange-Traded Fund Trust … | 9.36% | 222,199 SH | Oct. 2, 2026 | Daily |
| EZU · iShares, Inc. | 8.68% | 492,662 SH | Sept. 11, 2026 | Daily |
| MTRA · Invesco Actively Managed Exchange-T… | 7.87% | 5,907 SH | Oct. 2, 2026 | Daily |
| EFG · iShares Trust | 6.17% | 599,925 SH | Sept. 11, 2026 | Daily |
| DMXF · iShares Trust | 6.07% | 33,678 SH | Sept. 11, 2026 | Daily |
| IQLT · iShares Trust | 5.65% | 458,139 SH | Sept. 11, 2026 | Daily |
| GRW · TCW ETF Trust | 5.38% | 2,142 NS | July 31, 2026 | N-PORT |
| IDHQ · Invesco Exchange-Traded Fund Trust … | 5.11% | 31,154 SH | Oct. 2, 2026 | Daily |
| IMTM · iShares Trust | 4.82% | 121,919 SH | Sept. 11, 2026 | Daily |
| VGK · VANGUARD INTERNATIONAL EQUITY INDEX… | 4.80% | 927,679 SH | Aug. 19, 2026 | Daily |
| SUPP · TCW ETF Trust | 4.76% | 349 NS | July 31, 2026 | N-PORT |
| IEV · iShares Trust | 4.71% | 45,309 SH | Sept. 11, 2026 | Daily |
| IEUR · iShares Trust | 4.23% | 226,267 SH | Sept. 11, 2026 | Daily |
| SOXQ · Invesco Exchange-Traded Fund Trust … | 3.84% | 68,659 SH | Oct. 2, 2026 | Daily |
| DIHP · Dimensional ETF Trust | 3.51% | 137,089 NS | July 31, 2026 | N-PORT |
| ESGD · iShares Trust | 3.20% | 226,669 SH | Sept. 11, 2026 | Daily |
| PABD · iShares Trust | 3.11% | 5,994 SH | Sept. 11, 2026 | Daily |
| EFA · iShares Trust | 3.01% | 1,383,240 SH | Sept. 11, 2026 | Daily |
| QNXT · iShares Trust | 2.96% | 479 SH | Sept. 11, 2026 | Daily |
| AIFD · TCW ETF Trust | 2.94% | 2,259 NS | July 31, 2026 | N-PORT |
| IMFL · Invesco Exchange-Traded Self-Indexe… | 2.72% | 16,291 SH | Oct. 2, 2026 | Daily |
| IEFA · iShares Trust | 2.58% | 2,931,914 SH | Sept. 11, 2026 | Daily |
| AQLT · iShares Trust | 2.55% | 4,845 SH | Sept. 11, 2026 | Daily |
| DFSI · Dimensional ETF Trust | 2.48% | 17,456 NS | July 31, 2026 | N-PORT |
| IXN · iShares Trust | 2.42% | 132,571 SH | Sept. 11, 2026 | Daily |
| SOXX · iShares Trust | 2.42% | 622,400 SH | Sept. 11, 2026 | Daily |
| INTF · iShares Trust | 2.41% | 52,774 SH | Sept. 11, 2026 | Daily |
| IDVZ · Elevation Series Trust | 2.35% | 2,837 NS | July 31, 2026 | N-PORT |
| VEA · VANGUARD TAX-MANAGED FUNDS | 2.33% | 3,773,498 SH | Aug. 19, 2026 | Daily |
| IDEV · iShares Trust | 2.27% | 429,322 SH | Sept. 11, 2026 | Daily |
| VSGX · VANGUARD WORLD FUND | 2.26% | 77,513 SH | Aug. 19, 2026 | Daily |
| ESIM · Strategy Shares | 2.05% | 227 NS | July 31, 2026 | N-PORT |
| THNQ · EXCHANGE TRADED CONCEPTS TRUST | 2.02% | 5,168 NS | July 31, 2026 | N-PORT |
| VEU · VANGUARD INTERNATIONAL EQUITY INDEX… | 1.85% | 903,309 SH | Aug. 19, 2026 | Daily |
| ACWX · iShares Trust | 1.76% | 128,585 SH | Sept. 11, 2026 | Daily |
| VXUS · VANGUARD STAR FUNDS | 1.68% | 5,673,014 SH | Aug. 19, 2026 | Daily |
| SOXL · Direxion Shares ETF Trust | 1.65% | 197,024 NS | July 31, 2026 | N-PORT |
| DFAI · Dimensional ETF Trust | 1.63% | 175,212 NS | July 31, 2026 | N-PORT |
| IOO · iShares Trust | 1.61% | 84,938 SH | Sept. 11, 2026 | Daily |
| MPLY · Strategy Shares | 1.57% | 153 NS | July 31, 2026 | N-PORT |
| IXUS · iShares Trust | 1.52% | 536,382 SH | Sept. 11, 2026 | Daily |
| DFIC · Dimensional ETF Trust | 1.05% | 95,349 NS | July 31, 2026 | N-PORT |
| DXIV · Dimensional ETF Trust | 1.05% | 1,307 NS | July 31, 2026 | N-PORT |
| QQQE · Direxion Shares ETF Trust | 1.03% | 8,428 NS | July 31, 2026 | N-PORT |
| TOK · iShares Trust | 0.78% | 1,077 SH | Sept. 11, 2026 | Daily |
| URTH · iShares, Inc. | 0.73% | 34,908 SH | Sept. 11, 2026 | Daily |
| QRMI · Global X Funds | 0.72% | 63 NS | July 31, 2026 | N-PORT |
| QQQM · Invesco Exchange-Traded Fund Trust … | 0.71% | 432,536 SH | Oct. 2, 2026 | Daily |
| QQQ · Invesco QQQ Trust, Series 1 | 0.71% | 1,969,217 SH | Oct. 2, 2026 | Daily |
| QYLD · Global X Funds | 0.70% | 34,635 NS | July 31, 2026 | N-PORT |
| QYLG · Global X Funds | 0.69% | 666 NS | July 31, 2026 | N-PORT |
| CRBN · iShares Trust | 0.68% | 4,641 SH | Sept. 11, 2026 | Daily |
| QTR · Global X Funds | 0.66% | 31 NS | July 31, 2026 | N-PORT |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0.65% | 323,470 SH | Aug. 19, 2026 | Daily |
| ACWI · iShares Trust | 0.64% | 123,648 SH | Sept. 11, 2026 | Daily |
| QCLR · Global X Funds | 0.64% | 13 NS | July 31, 2026 | N-PORT |
| DFAX · Dimensional ETF Trust | 0.62% | 46,020 NS | July 31, 2026 | N-PORT |
| GLOF · iShares Trust | 0.60% | 707 SH | Sept. 11, 2026 | Daily |
| ACWV · iShares, Inc. | 0.43% | 8,461 SH | Sept. 11, 2026 | Daily |
| PXF · Invesco Exchange-Traded Fund Trust … | 0.39% | 6,239 SH | Oct. 2, 2026 | Daily |
| EFAV · iShares Trust | 0.29% | 9,167 SH | Sept. 11, 2026 | Daily |
| BNDW · VANGUARD SCOTTSDALE FUNDS | · | · | July 30, 2026 | Daily |
| BNDX · VANGUARD CHARLOTTE FUNDS | · | · | July 15, 2026 | Daily |
ASML Analyst Consensus Bullish and bearish analyst opinions, 12-month price target, upside
12-Month Price Target
16 analysts · 2026-09-28Mean target $2118.23 +13.4%
Latest News Recent headlines mentioning this company
ASML AI Analyst Panel — Bullish and Bearish Views 2026Q2 debate: Claude, Grok, Gemini, ChatGPT on the stock's prospects
ASML remains a high-stakes bet on the AI revolution, balancing a unique manufacturing monopoly against significant geopolitical and valuation risks. Grok argues the company's indispensable EUV technology justifies a buy, while Claude, ChatGPT, and Gemini warn that a 34.5 P/E leaves no room for error. The panel split on whether the 21.86 debt-to-equity ratio signals financial strength or a dangerous vulnerability to shifting export controls, ultimately favoring a cautious hold.
Round 1 — Opening Takes
I see ASML dominating the AI chip buildout as the monopoly supplier of EUV lithography tools that no one else can match at scale. They lifted their 2026 sales forecast on April 15, citing AI demand outpacing supply, which locks in multi-year revenue visibility. Net margin climbed to 31.73% TTM, up from 29.31% last quarter, showing they pocket most of that demand as profit thanks to pricing power. ROE holds steady at 46.86%, proving efficient capital turns into high returns without leverage risks, D/E flat at 21.86.
My read is ASML's lofty valuation leaves no room for AI demand to disappoint, risking a sharp multiple contraction if growth slows. P/E TTM sits at 34.5, up with the price rally, meaning the market demands flawless execution for years ahead. P/B at 12.3 is down slightly but still premiums the book value heavily, vulnerable if capex cycles turn. Recent price volatility, dipping to 651 in early May before rebounding to 802, highlights how sentiment swings can erase gains fast.
ASML is riding a structural tailwind that most chipmakers can only dream of — it's the sole critical chokepoint for advanced semiconductor manufacturing, and AI demand is now outpacing supply. The company just raised 2026 guidance on April 15th, signaling confidence in sustained order flow. Net margin expanded to 31.73%, up from 29.31% a year ago, which tells me pricing power is real and durable. Even at a 34.5 P/E, that multiple compresses if earnings growth stays in the 15–20% range, which the guidance lift suggests is realistic.
ASML's valuation has already priced in years of flawless execution — at 34.5 times trailing earnings and 10.9 times sales, there is almost no margin for error. The stock has rallied 18% since May on sentiment alone, and sentiment can reverse faster than fundamentals. Debt-to-equity sits at 21.86, which is elevated for a capital-light software-adjacent business and limits financial flexibility if a customer like TSMC stumbles. My worry is that the market is treating ASML as a proxy for AI upside rather than valuing it on its own cash generation.
ASML is the indispensable tollbooth for the entire AI hardware revolution, and their recent guidance hike proves they have zero competition. The company is currently generating a 31.73% net profit margin. This means nearly a third of every sale flows directly to the bottom line, highlighting their absolute dominance in extreme ultraviolet lithography. With a 46.86% ROE, they are incredibly efficient at turning shareholder capital into real growth. This level of return is a testament to the massive barriers to entry they have built around their unique, high-end chipmaking machines.
The valuation has reached a point where the market is pricing in perfection, leaving absolutely no room for a single missed beat in 2026. Investors are paying 34.49 times trailing earnings for these shares. That is a steep premium that requires flawless execution and sustained, hyper-growth demand to justify the current price. Furthermore, the 21.86 debt-to-equity ratio signals that while they are solvent, they are carrying significant leverage to maintain their massive R&D spending. If the AI spending cycle cools even slightly, that debt load will suddenly feel much heavier on their balance sheet.
I think ASML is positioned for durable upside thanks to AI-driven tool demand and ultra-strong margins. ROE TTM 46.86% shows the company converts equity into profits at a very high rate, signaling efficient scale and a capital-light growth path. That efficiency supports earnings growth and a strong cash generation profile. Net profit margin 31.73% means most revenue becomes profit, giving ASML room to reinvest and return capital. EPS TTM 26.03 signals a robust earnings base that justifies a premium multiple in a market hungry for AI-capital goods.
I think the bear case is that ASML's valuation is stretched and leverage could bite if the AI cycle slows. P/E TTM 34.49 suggests investors are pricing in multi-year AI growth; if demand slows, multiples compress. P/S TTM 10.94 underscores that the stock trades at a rich revenue multiple, making it vulnerable to any top-line misstep. Debt/Equity 21.86 indicates elevated leverage that could weigh on returns if financing costs rise or capex demand softens.
Round 2 — Responses & Rebuttals
Round 2 — Responses & Rebuttals
Claude, I push back on calling debt-to-equity at 21.86 elevated for a capex-heavy leader like ASML — it's held flat for multiple quarters, meaning debt funds just a fifth of their equity base without crowding out R&D. That stability pairs with a 1.41 current ratio, confirming ample liquidity to weather any TSMC hiccups. It bolsters the case for multi-year AI tailwinds over near-term fears.
I need to push back on Grok's read of that D/E ratio. Grok says the 21.86 debt-to-equity is flat and proves there are no leverage risks — but that's backwards. A D/E of 21.86 means ASML is carrying nearly $22 in debt for every dollar of equity, which is genuinely elevated for a company that prints 31.73% net margins. The fact that it's flat doesn't make it safe; it means they're not deleveraging despite record profitability. If AI demand cools and cash flow tightens, that debt load becomes a real constraint on capex flexibility — exactly when ASML needs to invest hardest to stay ahead of competition.
Grok, I think you are overlooking the structural risk of ASML's leverage when you call the 21.86 debt-to-equity ratio flat. While the number hasn't moved, that ratio implies they are financing their massive R&D and EUV production capacity with a significant amount of borrowed money. This means that if the AI demand cycle hits a speed bump, their fixed interest obligations remain constant while revenue becomes volatile. That leverage turns a minor sales dip into a major threat to their bottom line, which is why I am sticking with a hold rating.
Grok, I’m with you on the risk that the lofty multiple leaves little room for error, but I think you’re underestimating the durability of ASML’s moat. The stock trades at 34.5x trailing earnings. That means investors are already pricing in years of AI-driven growth; a near-term demand hiccup would likely compress the multiple before earnings catch up. Beyond the multiple, the Q1 beat and the AI cycle visibility argue for continued robust order flow, offsetting some near-term downside risk.
Round 3 — Final Rebuttals
Round 3 — Final Rebuttals
Claude, Gemini, leverage talk aside, customer concentration actually bolsters the bull case right now. TSMC, ASML's top customer highlighted in the April 16 news alongside strong mutual earnings, is ramping AI chips where ASML tools are irreplaceable. That symbiosis drove the April 15 guidance lift, with net orders outpacing supply. No signs of stumble – instead, it cements multi-year visibility over D/E fears, making buy for 2026Q2.
I want to push back on something nobody's touched yet — customer concentration. ASML's revenue is heavily dependent on TSMC, Samsung, and Intel. If TSMC alone represents 40–50% of orders, then ASML's guidance lift is really a bet on one customer's capex cycle, not a diversified AI tailwind. That means when TSMC's inventory normalizes or their capex pauses, ASML's growth doesn't just slow — it can crater. Grok and Gemini are treating the 31.73% net margin and the guidance as durable, but they're both contingent on TSMC staying in hypergrowth mode. That's not a structural moat; that's customer concentration risk masquerading as pricing power.
Grok, I disagree with your assessment of the current ratio as a shield against risk. A 1.41 current ratio means ASML has roughly $1.41 in liquid assets for every dollar of short-term debt, which is dangerously thin for a company facing intensifying geopolitical export controls. We cannot ignore that the U.S. and Dutch governments are tightening restrictions on shipping high-end lithography tools to China. This regulatory pressure isn't just a headline; it threatens the revenue stream from ASML’s largest growth market, potentially turning that tight liquidity into a solvency bottleneck if sales channels are suddenly blocked.
I think we should widen the frame to regulatory risk around ASML's China exposure. Claude, your point about leverage is interesting, but policy risk could cap upside even with strong fundamentals. Grok, Gemini, I still see AI-driven demand as durable, but export controls in the Netherlands limiting EUV sales to China could trim orders and delay multi-year growth. The overhang matters for 2026Q2 because policy moves can interrupt revenue visibility even as Q1 beat underpins the cash generation story.
Price Forecasts
| Model | 3M Target | 6M Target | Reasoning |
|---|---|---|---|
| Grok | $750.00 | $820.00 | I see ASML reclaiming highs through 2026Q2 as its EUV monopoly captures unrelenting AI tool demand outpacing supply. TSMC's Q2 earnings on July 17, 2026, will spotlight capex ramps that validate ASML's April guidance lift and drive orders higher. The big risk is Dutch regulators expanding China export bans by Q3 earnings, slashing 20-30% of potential sales overnight. My 6-month $820 target implies a forward P/E around 37 on rising EPS, rewarding the 31.73% net margin that converts AI hype into durable profits. |
| Claude | $745.00 | $820.00 | ASML's structural moat in EUV is real, but the stock is pricing in flawless execution at a 34.5x P/E — meaning the market has already baked in years of AI-driven growth. My thesis: near-term consolidation as sentiment cools, then recovery as 2026Q2 earnings prove the guidance lift was earned, not hype. Catalyst: ASML's Q2 2026 earnings beat (late July) confirming sustained TSMC capex and margin durability. Risk: TSMC guidance cut or export control tightening that blocks China revenue, which could compress the multiple 15–20% in weeks. At 34.5x trailing earnings, even a modest earnings miss triggers multiple compression faster than the stock can recover on fundamentals. I'm holding my hold rating but see 745 as fair 3-month value, then 820 by Q3 if Q2 execution holds. |
| Gemini | $725.00 | $760.00 | My thesis is that ASML will trade sideways as the market balances AI-driven order backlogs against the reality of tightening export controls and elevated valuation. A key catalyst for the six-month outlook is the Q3 earnings report, where any sign of margin compression would signal that geopolitical headwinds are finally hitting the bottom line. Conversely, a material expansion of U.S.-led export restrictions on high-end lithography tools to China remains the primary risk that could break my thesis. Investors are currently paying 34.49 times trailing earnings for these shares. That is a steep premium that requires flawless execution to justify the current price in an uncertain regulatory climate. |
| Chatgpt | $710.00 | $750.00 | I think ASML can drift higher over the next several months on durable AI tool demand and solid margins, but valuation and policy risk cap upside. A concrete catalyst is the upcoming earnings print in late July showing continued AI-driven order momentum and a potential guidance upgrade. A concrete risk is accelerated export controls limiting ASML’s China exposure, which could trim orders. ASML trades at about 34.5x trailing earnings. That means the market is pricing years of AI-driven growth into the stock, so a modest miss or policy shock could force multiple compression. |
Trading Signals Recent buy/sell signals with entry price and risk/reward ratio
No open signal right now — no card is filled, and that's honest.
My Metrics Your personal watchlist — selected rows from Full Fundamentals
Pick the metrics that matter to you — click the + next to any row in Full Fundamentals above.
Your selection is saved and follows you across all tickers.