
CP Canadian Pacific Kansas City Limited Common Shares
NYSE · Road & Rail · Переглянути на SEC EDGAR ↗ закриття Жов 6, 2026 10-K/10-Q Лип 30, 2026CP Знімок акцій Ціна, ринкова капіталізація, P/E, EPS, ROE, борг/власний капітал, діапазон 52 тижнів
CP Графік ціни акцій Денні OHLCV з технічними індикаторами — панування, масштабування та налаштування вашого представлення
Гранулярність стовпчиків адаптується до вибраного періоду — наведіть курсор на графік, щоб побачити відкриття/максимум/мінімум/закриття для стовпчика.
| Дата екс-дивіденду | Спліт | Тип |
|---|---|---|
| 14 травня 2021 р. | 5-for-1 | Прямий |
| 02 жовтня 2001 р. | 2-for-1 | Прямий |
| 10 червня 1985 р. | 3-for-1 | Прямий |
Про Canadian Pacific Kansas City Limited Common Shares Огляд компанії з Wikipedia
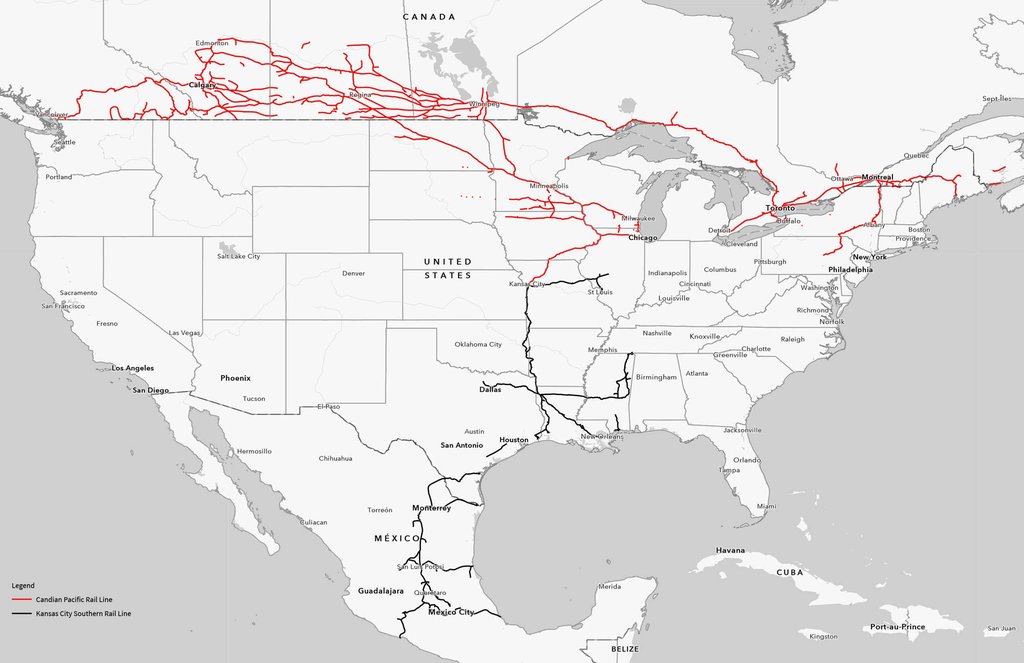
Canadian Pacific Kansas City Limited (known as Canadian Pacific Railway Limited until 2023), doing business as CPKC, is a Canadian railway holding company headquartered in Calgary. Through its operating subsidiaries, including the Canadian Pacific Railway, Kansas City Southern Railway, and Kansas City Southern de Mexico, it operates about 32,000 kilometres (20,000 mi) of rail in Canada, Mexico, and the United States.
History
Predecessors and formation
Canadian Pacific Railway (CP) announced on March 21, 2021, that it was planning to purchase Kansas City Southern (KCS) for US$29 billion.
Thirty days later, Canadian National Railway (CN) issued a competing offer of $33.7 billion. But in August, the US Surface Transportation Board (STB) blocked the CN deal, ruling that the company could not use a voting trust to assume control of KCS because it might reduce competition in the railroad industry.
On September 12, 2021, KCS accepted a new $31 billion offer from CP and terminated its agreement with CN. KCS's shareholders voted to approve the merger on December 10, 2021. The STB had already ruled that CP's plan to use a voting trust to take control of KCS would not hamper competition. The voting trust allowed CP to become the beneficial owner of KCS in December 2021, but the two railroads operated independently until receiving approval for a merger of operations from the STB. CP President and CEO Keith Creel, who became CEO of the merged company, chose the name of the new company as a way to honor the long and rich history of the two main predecessor companies. Creel also announced that if the STB approved the merger of CP with KCS, it would be celebrated with a historic tour from Calgary to Mexico City led by the iconic steam locomotive CPR #2816, The Empress.
Union Pacific and BNSF Railway raised objections with the STB about the merger. Both companies were concerned about CPKC's projected traffic increases and warned that they could cause congestion on UP-owned tracks through the Houston area (Houston, West Belt, East Belt, Beaumont, Harrisburg and Glidden Subdivisions), where UP and BNSF operate a large amount of daily traffic. (BNSF operates in the Houston area through a combination of owned tracks and trackage and haulage rights on UP tracks.) CPKC relies on UP trackage rights between Beaumont and Rosenberg, and between Victoria and Robstown to move its trains from Beaumont to the Mexican border at Laredo; that includes crossing Houston, where KCS and CPKC trains have experienced significant delays due to the heavy traffic that UP and BNSF operate in the Terminal. Creel, who has maintained important working relationships with UP, stated that he would spend time in Houston to learn about operations throughout the area and collaborate with UP to come up with a solution to the recurring problem of traffic congestion.
At the STB hearings, CP and KCS defended their merger proposal, arguing that Houston has sufficient capacity to support the projected increases in traffic. Creel, for example, argued that the receiving and departure tracks located at the west end of Englewood Yard, UP's main yard in Houston, could be lengthened to accommodate longer trains. UP responded to CP's arguments, saying that although they have a proposal to expand the yard, they could not proceed until existing environmental issues were resolved, stemming from creosote contamination that has affected the area surrounding Englewood (Southern Pacific for decades operated a facility at Englewood to treat railroad ties with creosote, and accidental spills of this substance caused severe contamination of the soil beneath the neighborhoods around the yard; UP is currently working with the City of Houston and the Environmental Protection Agency (EPA) on a remediation plan for the existing contamination in the area.) To mediate between the disputing parties, the Board suggested that (pending merger approval or post-merger) KCS or CPKC might apply to UP for trackage rights from Texarkana to Laredo via San Antonio and Austin to reroute part of the north-south traffic, bypassing Houston.
The two companies demanded that CPKC perform construction work on new sidings on both the lines that meet in the Houston area and on Brownsville Subdivision between Placedo and Robstown, near Corpus Christi, where CPKC trains leave the UP tracks in South Texas.
Metra also opposed the merger, arguing that the projected increase in traffic would delay its passenger trains. A group of west-suburban Chicago communities (DuPage County, Bartlett, Bensenville, Elgin, Itasca, Hanover Park, Roselle, Wood Dale and Schaumburg) on the Milwaukee District West Line said the merger would reduce quality of life and slow economic development in their communities.
In STB hearings, Canadian National, which had already lost KCS to CP, presented a plan to acquire a KCS line—the former Gateway Western, which linked Kansas City to Springfield, Illinois; St. Louis, Missouri; and East St. Louis, Illinois—tie it to its former Illinois Central Gilman Subdivision, and thus create via both Springfield and via St. Louis a new corridor between Kansas City, Michigan, and eastern Canada. This would bypass Chicago, and, according to the plan presented by CN, divert 80,000 long-haul truck shipments to rail annually. The plan included the improvement of the corridor, valued at more than US$250 million. A few months later, CN ended its effort to purchase the Springfield Line to try to obtain trackage rights on the line, always with the same intention of creating the corridor proposed in the original plan to purchase the line filed with the STB. The STB rejected CN's plans to operate on the Springfield Line.
Despite the objections, the merger between CP and KCS received final approval on March 15, 2023, and was completed on April 14, 2023.
The merger created the first and, as of 2023 only, railway corporation connecting Canada, the U.S., and Mexico without having to run trains on competing railroads' rails. It had about 32,000-kilometre (20,000 mi) network of tracks. Fully integrating the two railroads was expected to take up to three years.
Post-merger history
Seven days after the merger, the company announced that it had landed its first major contract, handling Schneider National intermodal traffic between the U.S. and Mexico. On April 25, it signed a similar agreement with Knight-Swift. The announcement was seen as backing up pre-merger projections that CPKC's service would enable it to compete in the Chicago–Mexico corridor that had been dominated by the Union Pacific and BNSF. In response, on April 24, Union Pacific responded by announcing a partnership with Canadian National Railway and Grupo México (owner of Ferromex and Ferrosur) to work together to accelerate the exchange of intermodal traffic between Mexico and Chicago or further north into Canada.
On May 11, 2023, CPKC launched its "Mexico Midwest Express (MMX)" service, numbered I180 and I181, which is mainly oriented to intermodal and automobile transportation, and also provides an approximate travel time of 98 hours between Chicago and Kansas City to Monterrey and San Luis Potosi, shorter times than those offered by the "Falcon Premium" service of UP, CN and Grupo México. Previously, and as part of preparatory moves for the day after the merger, CP and KCS launched a series of test interline services between the Lázaro Cárdenas Port in the Michoacán Mexican state and the Bensenville Yard in Chicago.
On June 28, 2023, CPKC announced the intent to jointly acquire with CSX Transportation the Meridian and Bigbee Railroad (MNBR). The MNBR creates a connection 168 miles (270 km) between CSX in Montgomery, Alabama and Meridian, Mississippi, where it joins the Meridian Speedway westbound. Under the proposed agreement, CPKC would acquire the 50.4 miles (81.1 km) segment of the line between Meridian and Myrtlewood, Alabama, so-called Western Line, while CSX, in a nearly separate transaction, will resume operations on the so-called Eastern Line, between Myrtlewood and Montgomery, terminating the lease currently in place with MNBR. MNBR will cease operating between Myrtlewood and Montgomery, although it may continue to operate between Meridian and Myrtlewood and serve existing customers on that segment of the line. If the STB approves the transaction, this will provide a new direct connection between the two companies' networks (CSX and CPKC already have connections New Orleans and in St. Louis, Missouri). In compensation, MNBR owner Genesee & Wyoming would receive CPKC properties in Alberta along with rights on CPKC lines. The connection through the MNBR line will allow CSX traffic destined for Mexico to be delivered directly to CPKC, eliminating the need for a third intermediary railroad to move such traffic. Currently, CSX traffic bound for Mexico is exchanged with the Union Pacific in New Orleans, who then takes it to the cross-border gateway in Laredo, Texas, where it is delivered to CPKC. MNBR's Western Line, once acquired by CPKC, will be renamed Haverty Subdivision, in honor of former KCS CEO and President Mike Haverty, the original driver of the idea to acquire MNBR more than two decades ago, to tie the KCS and CSX rail networks.
Haverty, who served as KCS CEO and president from 1995 to 2015, was the driving force behind the company's expansion to Mexico during his tenure, acquiring Tex-Mex in 1995 and then, that same year, win along with Transportadora Maritima Mexicana (TMM), the concession of the Mexican Northeast Railroad under the name Transportadora Ferroviaria Mexicana (TFM), which would ultimately become the catalyst for CP to acquire KCS.
In October 2024, the STB approved CPKC's purchase of the M&B line between Meridian and Myrtlewood, and CSX's resumption of operations between Myrtlewood and Burkville. The agreement became effective on November 16, 2024. For the first five years, CPKC and CSX will interchange two trains per day in each direction.
A few days before CPKC and CSX took over the former M&B line, Schneider National, CPKC's main intermodal partner and one of CSX's major partners, announced that a new interline service connecting the Southeast (Florida and Georgia) with the Texas and Mexico markets via the route between Montgomery and Meridian will be launched beginning in December.
CN and Amtrak unsuccessfully objected to the purchase of the M&B line, fearing that increased traffic on the Meridian Speedway would cause congestion in the line. CN required CPKC to report the daily number of trains running through the Speedway to know if there will indeed be congestion on the line. Amtrak, for its part, requested that the daily traffic on the line be adjusted to the length of the existing sidings along the route.
The CN and Amtrak requests were rejected by the STB, on the grounds that the two daily train pairs that CPKC and CSX plan to interchange across the M&B line will not cause congestion on the Speedway.
In August 2023, UP and CPKC butted heads again, this time over the scope of the original "North End" and "South End" agreement granting KCS trackage and haulage rights only for grain shipments from the Omaha / Council Bluffs area to Gulf Coast ports. CPKC informed the STB that UP was blocking the use of trackage and haulage rights dating back to the 1988 merger between the Missouri-Kansas-Texas Railroad (MKT), better known as "The Katy", and UP. CPKC inherited those rights from KCS. When UP acquired the Katy, Interstate Commerce Commission (ICC) required UP, as a condition of merger approval, to grant other railroads (including KCS) trackage and haulage rights to operate in the "Omaha/Council Bluffs-Kansas City corridor, with a further ability to move the grain traffic originating in this area to the Gulf." The conflict arose because UP considered that CPKC was violating the original 1988 UP and KCS agreement. The original agreement stated that only grain trains originating in the Omaha/Council Bluffs area would be covered by the “South End” rights agreement between Beaumont and the ports of Houston and Galveston. KCS had sporadically used the "North End" rights between Kansas City and Council Bluffs, along with the "South End" rights from Beaumont to south, but after the merger, grain elevators located on the former CP system, primarily in North Dakota and Minnesota, expressed interest in using the CPKC system to transport their grains from the Upper Midwest to Gulf ports, utilizing the "South End" rights. UP considered this to be a breach of the agreement. In July 2025, the STB ruled in favor of CPKC in the litigation against UP over the "South End" agreement.
In its ruling, the Board determines that the term "interchange" in the 1988 agreement includes the exchange of traffic between rail carriers under common control (CP and KCS).
In January 2024, Bison Transport, Winnipeg, MB, based intermodal mover, signed a major agreement with CPKC capitalizing on the company's growing crossborder intermodal traffic between Canada, US and Mexico. Such a partnership would allow immediate access to cross-border multimodal services using CPKC's rail corridors, while taking advantage of the reliability and punctuality of travel times handled by CPKC trains along its corridor from Chicago to Mexico, primarily the "Mexico Midwest Express" (MMX, I180/I181 trains).
In April 2024, as part of the company's first anniversary celebrations, the Steam locomotive CPR #2816 known as "The Empress" was launched on a historic transnational tour that traveled most of CPKC's network, starting April 24 in Calgary and ending June 7 in Mexico City. On June 9, began its return travel from Mexico City to Calgary, arriving on July 10.
CPKC and Canadian National locked out workers in Canada from August 22 to 26, 2024, after the companies and the Teamsters Canada Rail Conference failed to reach a labor agreement.
In Mexico, CPKC has spent more than $75 million to build new sidings, double-track sections, bypass tracks, add yard leads, and create faster turnouts. These were not initially envisioned as part of the CP-KCS merger. It is working to improve the Port of Lázaro Cárdenas, also promoting it as an alternative to the congestion at Long Beach, Los Angeles, and other West Coast ports for intermodal shipments to and from CPKC's terminals in Kendleton, near Houston, and Wylie, in the Dallas-Fort Worth area, and other points served by the company.
In December 2024, construction was completed on the second crossborder bridge in Laredo–Nuevo Laredo, which ended the bottleneck created by the previous single-tracked bridge. KCS's CEO and President, Patrick "Pat" J. Ottensmeyer had pushed for the new bridge during his tenure at KCS, prior to the merger with CP. He died in July 2024, and CPKC's directors named the new bridge in his memory. CPKC CEO Creel met with Mexican President Claudia Sheinbaum to settle an opening date for the bridge, and the details of a new Mexico City-San Luis Potosi-Monterrey-Nuevo Laredo passenger train to be run primarily on CPKC tracks. The newly renamed double-track "Patrick J. Ottensmeyer International Railway Bridge" opened on 6 February 2025.
As CP has been doing since 1999 until 2022, CPKC has continued to run holiday trains from mid-November through December, which now with the combined network are deployed along the company's entire tracks network. In both 2023 and now in 2024, two Holidays trains made up of ex-CP rolling stock run through the central and northern end of the company's network, and two more trains made up of former KCS and KCSM Office Car Special (OCS) trains run through the southern end of the company's network.
In early 2025, CPKC was promoting bonded shipments between Canada and Mexico without the need to clear US customs, thus avoiding any tariffs imposed on foreign countries by the Trump administration. This service was faster than using trucks or rival railways because CPKC did not need to interchange with other US railways. For example, shipments of Canadian oats to Mexico have quadrupled in volume. Other products transported by CPKC from Canada to Mexico include liquid petroleum gas, refined fuels and plastics. In the other direction, CPKC is transporting Mexican fruits and vegetables, home appliances and furniture to Canada where, due to Canadian counter tariffs, can be cheaper than US imports.
In December 2025, CPKC became one of the companies that has most strongly opposed the proposed merger between UP and Norfolk Southern, and plans to submit its comments to the STB in accordance with the hearing schedule adopted by the STB during the proceedings.
Later that same month, CPKC, along with BNSF, CSX, and CN, decided to file a submission with the STB, stating that the initial proposal from UP and NS was considered incomplete because it omitted key information.
Operations
CPKC operates about 32,000 kilometres (20,000 mi) of rail across Canada, Mexico and the United States. As of April 2023, CPKC has around 20,000 employees. CPKC has its global headquarters in Calgary, Alberta, Canada with its U.S. headquarters in Kansas City, Missouri, and its Mexico headquarters in Mexico City and Monterrey.
Company executives said that merging CP and KCS would be "straightforward" because the railroads only touch at Kansas City, and interchange volumes were relatively low, with about four trains per day as of September 2021. They also cited that the two companies largely used the same back-office information technology systems.
The railroad maintains its own police force, the Canadian Pacific Kansas City Police.
Sponsorships
CPKC inherited and renewed CP's existing sponsorship of the Canadian Women's Open golf tournament in July 2023, extending it through 2026.
In October 2023, CPKC and the Kansas City Current of the National Women's Soccer League announced a 10-year naming rights deal for the Current's new stadium in Kansas City, Missouri, the first stadium ever constructed specifically for a professional women's sports team.
Джерело: Wikipedia (Англійська), CC BY-SA 4.0 · Переглянути на Wikipedia ↗
10-річна ефективність Тренди виручки, чистого прибутку, маржі та EPS
Оцінка Співвідношення P/E, P/S, P/B, EV/EBITDA — акція дорога чи дешева?
| Метрика | 5-річний тренд | CP | середнє за 5 років | Медіана аналогів | Висновок |
|---|---|---|---|---|---|
| P/E (TTM) | 19.9середнє за 5 років ≈18.1 | ≈18.1 | · | · | |
| P/S (TTM) | 4.9 | · | · | · | |
| P/B (MRQ) | 1.6 | · | · | · | |
| Ціна / FCF (TTM) | 31.0 | · | · | · | |
| Ціна / Грошовий потік (TTM) | 13.7 | · | · | · | |
| Ціна / Матеріальний чистий капітал (MRQ) | 1.7середнє за 5 років ≈2.5 | ≈2.5 | · | · | |
| PEG Ratio (Коефіцієнт PEG) | ≈4.3 | · | · | · |
Медіана аналогічних компаній розраховується на стандартизованій основі для кожного показника і може не завжди відповідати базі TTM/MRQ, показаній для цієї акції.
Прибутковість Валова, операційна та чиста маржа; ROE, ROA, ROIC
| Метрика | 5-річний тренд | CP | середнє за 5 років | Медіана аналогів | Висновок |
|---|---|---|---|---|---|
| Операційна маржа (TTM) | 36.8% | · | · | · | |
| Маржа EBITDA (TTM) | 50.0% | · | · | · | |
| До оподаткування маржа (TTM) | 33.5% | · | · | · | |
| Маржа чистого прибутку (TTM) | 25.0% | · | · | · | |
| ROA (TTM) | 4.4% | · | · | · | |
| ROE (TTM) | 8.3% | · | · | · |
Фінансове здоровʼя Борг, ліквідність, платоспроможність — міцність балансу
| Метрика | 5-річний тренд | CP | середнє за 5 років | Медіана аналогів | Висновок |
|---|---|---|---|---|---|
| Поточний коефіцієнт (MRQ) | 0.6 | · | · | · |
Зростання Зростання виручки, EPS та чистого прибутку: рік до року, 3-річний CAGR, 5-річний CAGR
| Метрика | 5-річний тренд | CP | середнє за 5 років | Медіана аналогів | Висновок |
|---|---|---|---|---|---|
| Revenue YoY (Виторг рік до року) | 3.7%середнє за 5 років ≈15.2% | ≈15.2% | · | · | |
| Revenue CAGR 3Y (CAGR виторгу 3 роки) | 19.6%середнє за 5 років ≈19.8% | ≈19.8% | · | · | |
| Revenue CAGR 5Y (CAGR виторгу 5 років) | 14.4% | · | · | · | |
| EPS YoY | 13.3%середнє за 5 років ≈5.2% | ≈5.2% | · | · | |
| Net Income YoY (Чистий прибуток рік до року) | 11.4%середнє за 5 років ≈11.5% | ≈11.5% | · | · | |
| EPS CAGR 3Y (CAGR EPS 3 роки) | 6.2%середнє за 5 років ≈3.3% | ≈3.3% | · | · | |
| EPS CAGR 5Y (CAGR EPS 5 років) | 4.7% | · | · | · | |
| Net Income CAGR 3Y (CAGR чистого прибутку 3 роки) | 5.6%середнє за 5 років ≈10.7% | ≈10.7% | · | · | |
| Net Income CAGR 5Y (CAGR чистого прибутку 5 років) | 11.1% | · | · | · |
Ефективність капіталу Оборотність активів, оборотність запасів, оборотність дебіторської заборгованості
| Метрика | 5-річний тренд | CP | середнє за 5 років | Медіана аналогів | Висновок |
|---|---|---|---|---|---|
| Revenue / Employee (Виручка / співробітник (річна виручка ÷ кількість співробітників (штатний розпис, yfinance). Похідне — не збережена концепція SEC-XBRL).) | ≈$765.9K | · | · | · |
значення · ≈ середнє за 5 років · медіана галузі · вердикт відносно медіани
Дивіденди Дивідендна дохідність, коефіцієнт виплат, історія дивідендів, 5-річний CAGR
| Дата екс-дивіденду | Сума | Валюта | Дохідність |
|---|---|---|---|
| Вер 25, 2026 | $0,19 | USD | ≈0.81% |
| Чер 26, 2026 | $0,19 | USD | ≈0.78% |
| Бер 27, 2026 | $0,17 | USD | ≈0.80% |
| Вер 26, 2025 | $0,16 | USD | ≈0.81% |
| Чер 27, 2025 | $0,17 | USD | ≈0.73% |
| Бер 28, 2025 | $0,13 | USD | ≈0.79% |
| Гру 27, 2024 | $0,13 | USD | ≈0.76% |
| Вер 27, 2024 | $0,14 | USD | ≈0.66% |
| Чер 28, 2024 | $0,14 | USD | ≈0.72% |
| Бер 27, 2024 | $0,14 | USD | ≈0.64% |
| Гру 28, 2023 | $0,14 | USD | ≈0.72% |
| Вер 28, 2023 | $0,14 | USD | ≈0.76% |
| Чер 29, 2023 | $0,14 | USD | ≈0.88% |
| Бер 30, 2023 | $0,14 | USD | ≈0.93% |
| Гру 29, 2022 | $0,14 | USD | ≈0.95% |
| Вер 29, 2022 | $0,14 | USD | ≈1.1% |
| Вер 28, 2022 | $0,14 | USD | ≈0.85% |
| Чер 23, 2022 | $0,15 | USD | ≈0.87% |
| Бер 24, 2022 | $0,15 | USD | ≈0.73% |
| Гру 30, 2021 | $0,15 | USD | ≈0.84% |
Історія прибутків EPS фактичний проти прогнозу, сюрприз %, коефіцієнт перевищення, дата наступного звіту про прибутки
| Період | Звіт | EPS (факт) | EPS прогноз | Сюрприз |
|---|---|---|---|---|
| 30 червня 2026 р. | $1.27 | $1.27 | -0.36% | |
| 31 березня 2026 р. | $1.04 | $1.10 | -5.8% | |
| 31 грудня 2025 р. | $1.33 | $1.40 | -4.7% | |
| 30 вересня 2025 р. | $1.10 | $1.15 | -4.0% | |
| 30 червня 2025 р. | $1.12 | $1.16 | -3.8% | |
| 31 березня 2025 р. | $1.06 | $1.07 | -1.2% |
Повні фундаментальні показники Усі показники за роками — звіт про прибутки та збитки, баланс, рух грошових коштів
Звіт про прибутки та збитки
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $15.08B | $14.55B | $12.55B | $8.81B | $8.00B | $7.71B | $7.79B | · | $6.55B | $6.23B | $6.71B | |
| Operating Expenses | $9.47B | $9.37B | $8.17B | $5.49B | $4.79B | $4.40B | $4.67B | · | $4.04B | $3.82B | $4.02B | |
| Operating Income | $5.61B | $5.18B | $4.39B | $3.33B | $3.21B | $3.31B | $3.12B | · | $2.52B | $2.41B | $2.69B | |
| Interest Expense | · | · | · | · | $446M | $462M | $454M | · | $475M | $472M | · | |
| Interest Income | · | · | · | · | $6M | $4M | $6M | · | $2M | $1M | $1M | |
| Other Non-op | $1M | $42M | $-52M | $-17M | $-237M | $7M | $89M | · | $-12M | $-14M | $-15M | |
| Pretax Income | $5.48B | $4.77B | $-3.05B | $4.14B | $3.62B | $3.20B | $3.15B | · | $2.50B | $2.15B | $1.96B | |
| Income Tax | $1.34B | $1.06B | $-6.98B | $628M | $768M | $758M | $706M | · | $93M | $553M | $607M | |
| Net Income | $4.14B | $3.72B | $3.93B | $3.52B | $2.85B | $2.44B | $2.44B | · | $2.40B | $1.60B | $1.35B | |
| EPS (Basic) | $4.52 | $3.98 | $4.22 | $3.78 | $4.20 | $3.61 | $3.52 | · | $16.49 | $10.69 | $8.47 | |
| EPS (Diluted) | $4.51 | $3.98 | $4.21 | $3.77 | $4.18 | $3.59 | $3.50 | · | $16.44 | $10.63 | $8.40 | |
| Shares (Basic) | 916,200,000 | 933,000,000 | 931,300,000 | 930,000,000 | 679,700,000 | 677,200,000 | 693,800,000 | · | 145,900,000 | 149,600,000 | 159,700,000 | |
| Shares (Diluted) | 917,100,000 | 934,600,000 | 933,700,000 | 932,900,000 | 682,800,000 | 679,900,000 | 696,300,000 | · | 146,300,000 | 150,500,000 | 161,000,000 | |
| EBITDA | · | · | · | · | · | · | · | · | · | $3.22B | $3.28B |
Баланс
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $184M | $739M | $464M | $451M | $69M | $147M | $133M | · | $338M | $164M | $650M | |
| Short-term Investments | · | · | · | $0 | · | · | · | · | $0 | $0 | $0 | |
| Receivables | $2.03B | $1.97B | $1.89B | $1.02B | $819M | $825M | $805M | · | $687M | $591M | $645M | |
| Other Current Assets | $224M | $220M | $251M | $138M | $216M | $141M | $90M | · | $97M | $70M | $54M | |
| Current Assets | $2.94B | $3.38B | $3.00B | $1.89B | $1.35B | $1.32B | $1.21B | · | $1.27B | $1.01B | $1.54B | |
| PP&E (Net) | $55.32B | $56.02B | $51.74B | $22.39B | $21.20B | $20.42B | $19.16B | $18.41B | $17.02B | $16.69B | $16.27B | |
| PP&E (Gross) | · | · | · | · | · | $29.05B | $27.25B | · | $24.43B | $23.81B | $23.23B | |
| Accum. Depreciation | · | · | · | · | · | $8.63B | $8.10B | · | $7.41B | $7.12B | $6.95B | |
| Goodwill | $18.44B | $19.35B | $17.73B | $344M | $328M | $329M | $194M | · | $178M | $191M | $198M | |
| Intangibles | $2.91B | $3.15B | $2.97B | $42M | $43M | $37M | $12M | · | $9M | $11M | $13M | |
| Other Non-current Assets | $734M | $668M | $582M | $420M | $419M | $438M | $451M | $470M | $69M | $57M | $63M | |
| Total Assets | $85.94B | $87.74B | $79.90B | $73.50B | $68.18B | $23.64B | $22.37B | · | $20.14B | $19.22B | $19.64B | |
| Accounts Payable | $2.75B | $2.84B | $2.57B | $1.70B | $1.61B | $1.47B | $1.69B | $1.51B | $1.24B | $1.32B | $1.42B | |
| Accrued Liabilities | $597M | $732M | $667M | $284M | $286M | $294M | $348M | · | $256M | $282M | $293M | |
| Short-term Debt | $1.17B | $1.59B | $1.06B | $0 | · | · | $397M | · | · | · | · | |
| Current Liabilities | $5.99B | $5.66B | $5.71B | $3.21B | $3.16B | $2.65B | $2.29B | · | $1.98B | $1.35B | $1.45B | |
| Capital Leases | $299M | $254M | $242M | $202M | $224M | $248M | $285M | · | $147M | $162M | $171M | |
| Deferred Tax | $11.83B | $11.97B | $11.05B | $12.20B | $11.35B | $3.67B | $3.50B | $3.52B | $3.32B | $3.57B | $3.39B | |
| Other Non-current Liabilities | $815M | $867M | $797M | $520M | $542M | $585M | $562M | $574M | $231M | $284M | $318M | |
| Total Liabilities | $39.12B | $38.85B | $37.49B | $34.61B | $34.35B | $16.32B | $15.30B | · | $13.70B | $14.60B | $14.84B | |
| Common Stock | $24.75B | $25.69B | $25.60B | $25.52B | $25.48B | $1.98B | $1.99B | · | $2.03B | $2.00B | $2.06B | |
| Retained Earnings | $19.78B | $19.43B | $16.42B | $13.20B | $10.39B | $8.10B | $7.55B | $6.63B | $6.10B | $4.37B | $4.17B | |
| AOCI | $1.24B | $2.68B | $-618M | $91M | $-2.10B | $-2.81B | $-2.52B | · | $-1.74B | $-1.80B | $-1.48B | |
| Stockholders' Equity | $45.88B | $47.89B | $41.49B | $38.89B | $33.83B | $7.32B | $7.07B | $6.63B | $6.44B | $4.63B | $4.80B | |
| Liabilities + Equity | $85.94B | $87.74B | $79.90B | $73.50B | $68.18B | $23.64B | $22.37B | · | $20.14B | $19.22B | $19.64B | |
| Shares Outstanding | 897,600,000 | 933,500,000 | 932,100,000 | 930,500,000 | 929,700,000 | 666,300,000 | 685,000,000 | 140,500,000 | 144,900,000 | 146,300,000 | 153,000,000 |
Грошовий потік
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $2.02B | $1.90B | $1.54B | $853M | $811M | $779M | $706M | · | $661M | $640M | $595M | |
| Deferred Tax | $171M | $28M | $-7.88B | $136M | $242M | $221M | $181M | · | $-210M | $320M | $234M | |
| Amort. of Intangibles | $87M | $85M | $61M | $3M | $3M | $3M | $1M | · | $1M | $1M | $1M | |
| Other Non-cash | · | · | · | · | · | · | · | · | · | $-470M | $278M | |
| Operating Cash Flow | $5.31B | $5.27B | $4.14B | $4.14B | $3.69B | $2.80B | $2.99B | · | $2.18B | $2.09B | $2.46B | |
| CapEx | $3.10B | $2.83B | $2.47B | $1.56B | $1.53B | $1.67B | $1.65B | · | $1.34B | $1.18B | $1.52B | |
| Investing Cash Flow | $-2.67B | $-2.80B | $-2.16B | $-1.50B | $-13.73B | $-2.03B | $-1.80B | · | $-1.29B | $-1.07B | $-1.12B | |
| Stock Issued | $73M | $69M | $69M | $32M | $25M | $52M | $26M | · | $45M | $21M | $43M | |
| Stock Repurchased | $3.94B | $0 | $0 | $0 | $0 | $1.51B | $1.13B | · | $381M | $1.21B | $2.79B | |
| Net Stock Activity | · | · | · | · | · | · | · | · | · | $-1.19B | $-2.74B | |
| Dividends Paid | $796M | $709M | $707M | $707M | $507M | $467M | $412M | · | $310M | $255M | $226M | |
| Financing Cash Flow | $-3.15B | $-2.25B | $-1.96B | $-2.30B | $9.94B | $-764M | $-1.11B | · | $-700M | $-1.49B | $-957M | |
| Net Change in Cash | $-555M | $275M | $13M | $369M | $-65M | $14M | $72M | · | $174M | $-486M | $424M | |
| Taxes Paid | $1.16B | $958M | $906M | $408M | $552M | $582M | $506M | · | $425M | $322M | $176M | |
| Free Cash Flow | · | · | · | · | · | · | · | · | · | $907M | $937M |
Прибутковість
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | · | · | · | · | · | · | · | · | · | 41.4% | 40.1% | |
| Net Margin | · | · | · | · | · | · | · | · | · | 25.7% | 20.1% | |
| Pretax Margin | · | · | · | · | · | · | · | · | · | 34.5% | 29.2% | |
| EBITDA Margin | · | · | · | · | · | · | · | · | · | 51.6% | 48.9% | |
| ROA | · | · | · | · | · | · | · | · | · | 8.2% | 7.5% | |
| ROE | · | · | · | · | · | · | · | · | · | 34.4% | 30.8% | |
| ROIC | · | · | · | · | · | · | · | · | · | 41.4% | 38.7% |
Ліквідність та платоспроможність
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | · | · | · | · | · | · | · | · | · | 0.7 | 1.1 | |
| Quick Ratio | · | · | · | · | · | · | · | · | · | 0.6 | 0.9 |
Ефективність
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | · | · | · | · | · | · | · | · | · | 0.3 | 0.4 | |
| Receivables Turnover | · | · | · | · | · | · | · | · | · | 10.1 | 10.0 |
На акцію
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | · | · | · | · | · | · | · | · | · | $31.62 | $31.35 | |
| Revenue / Share | · | · | · | · | · | · | · | · | · | $41.41 | $41.69 | |
| Cash Flow / Share | · | · | · | · | · | · | · | · | · | $13.88 | $15.27 | |
| Cash / Share | · | · | · | · | · | · | · | · | · | $1.12 | $4.25 | |
| Dividend / Share | $0.87 | $0.76 | $0.76 | $0.76 | $0.76 | $0.71 | $0.63 | · | $2.19 | $1.85 | $1.40 | |
| EPS (TTM) | $4.51 | $3.98 | $4.21 | $3.77 | $4.18 | $3.59 | $3.50 | · | $16.44 | $10.63 | $8.40 |
Темпи зростання
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue YoY | 3.7% | 15.9% | 42.4% | 10.2% | 3.7% | · | · | · | · | · | · | |
| Revenue CAGR 3Y | 19.6% | 22.1% | 17.6% | · | · | · | · | · | · | · | · | |
| Revenue CAGR 5Y | 14.4% | · | · | · | · | · | · | · | · | · | · | |
| EPS YoY | 13.3% | -5.5% | 11.7% | -9.8% | 16.4% | · | · | · | · | · | · | |
| EPS CAGR 3Y | 6.2% | -1.6% | 5.5% | · | · | · | · | · | · | · | · | |
| EPS CAGR 5Y | 4.7% | · | · | · | · | · | · | · | · | · | · | |
| Net Income YoY | 11.4% | -5.3% | 11.7% | 23.3% | 16.7% | · | · | · | · | · | · | |
| Net Income CAGR 3Y | 5.6% | 9.2% | 17.1% | · | · | · | · | · | · | · | · | |
| Net Income CAGR 5Y | 11.1% | · | · | · | · | · | · | · | · | · | · | |
| Dividends Paid CAGR 5Y | 11.2% | · | · | · | · | · | · | · | · | · | · |
Оцінка (TTM)
| Метрика | Тенденція | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $15.08B | $14.55B | $12.55B | $8.81B | $8.00B | $7.71B | $7.79B | · | $6.55B | $6.23B | $6.71B | |
| Net Income TTM | $4.14B | $3.72B | $3.93B | $3.52B | $2.85B | $2.44B | $2.44B | · | $2.40B | $1.60B | $1.35B | |
| Market Cap | · | · | · | · | · | · | · | · | · | $4.18B | $3.90B | |
| P/E | 16.3 | 18.2 | 18.8 | 19.8 | 17.2 | 19.3 | 14.6 | · | 2.2 | 2.7 | 3.0 | |
| P/S | · | · | · | · | · | · | · | · | · | 0.7 | 0.6 | |
| P/B | · | · | · | · | · | · | · | · | · | 0.9 | 0.8 | |
| P / Tangible Book | 2.7 | 2.7 | 3.5 | 1.8 | 2.0 | 1.3 | · | · | · | · | · | |
| P / Cash Flow | · | · | · | · | · | · | · | · | · | 2.0 | 1.6 | |
| P / FCF | · | · | · | · | · | · | · | · | · | 4.6 | 4.2 | |
| Dividend Yield | · | · | · | · | · | · | · | · | · | 6.1% | 5.8% | |
| Earnings Yield | 6.1% | 5.5% | 5.3% | 5.1% | 5.8% | 5.2% | 6.9% | · | 45.0% | 37.2% | 32.9% | |
| Payout Ratio | · | · | · | · | · | · | · | · | · | 16.0% | 16.7% | |
| Annual Payout | $796M | $709M | $707M | $707M | $507M | $467M | $412M | · | $310M | $255M | $226M |
Звіт про прибутки та збитки
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | $4.16B | $3.70B | $3.92B | $3.66B | $3.70B | $3.79B | $3.87B | $3.55B | $3.60B | $3.52B | $3.78B | $3.34B | $3.17B | $2.27B | $2.46B | |
| Operating Expenses | $2.69B | $2.44B | $2.31B | $2.33B | $2.36B | $2.48B | $2.31B | $2.35B | $2.34B | $2.37B | $2.33B | $2.17B | $2.23B | $1.44B | $1.47B | |
| Operating Income | $1.47B | $1.26B | $1.61B | $1.34B | $1.34B | $1.32B | $1.56B | $1.20B | $1.27B | $1.15B | $1.44B | $1.17B | $944M | $829M | $989M | |
| Other Non-op | $14M | $-20M | $0 | $-8M | $16M | $-7M | $1M | $-1M | $40M | $2M | $-16M | $-13M | $-21M | $-2M | $-4M | |
| Pretax Income | $1.36B | $1.12B | $1.48B | $1.21B | $1.59B | $1.20B | $1.45B | $1.10B | $1.20B | $1.03B | $1.29B | $1.04B | $-6.35B | $963M | $1.37B | |
| Income Tax | $335M | $275M | $400M | $296M | $357M | $292M | $246M | $262M | $292M | $259M | $275M | $258M | $-7.67B | $163M | $102M | |
| Net Income | $1.02B | $846M | $1.08B | $920M | $1.23B | $910M | $1.20B | $837M | $905M | $775M | $1.02B | $780M | $1.32B | $800M | $1.27B | |
| EPS (Basic) | $1.16 | $0.94 | $1.19 | $1.01 | $1.34 | $0.98 | $1.28 | $0.90 | $0.97 | $0.83 | $1.10 | $0.84 | $1.42 | $0.86 | $1.37 | |
| EPS (Diluted) | $1.15 | $0.94 | $1.20 | $1.01 | $1.33 | $0.97 | $1.28 | $0.90 | $0.97 | $0.83 | $1.09 | $0.84 | $1.42 | $0.86 | $1.36 | |
| Shares (Basic) | 886,400,000 | 896,800,000 | · | 910,400,000 | 923,800,000 | 933,200,000 | · | 933,200,000 | 932,800,000 | 932,400,000 | · | 931,500,000 | 931,200,000 | 930,700,000 | · | |
| Shares (Diluted) | 887,100,000 | 897,300,000 | · | 911,400,000 | 924,800,000 | 934,300,000 | · | 935,300,000 | 934,600,000 | 934,400,000 | · | 933,900,000 | 933,800,000 | 933,500,000 | · | |
| EBITDA | $1.99B | $1.77B | · | $1.84B | $1.84B | $1.82B | · | $1.68B | $1.74B | $1.62B | · | $1.62B | $1.35B | $1.05B | · |
Баланс
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash & Equivalents | $366M | $409M | $184M | $411M | $799M | $695M | $739M | $463M | $557M | $519M | · | $294M | $325M | $290M | · | |
| Short-term Investments | · | · | · | · | · | · | · | · | · | · | · | $273M | $264M | · | · | |
| Receivables | $2.25B | $2.20B | $2.03B | $2.12B | $2.00B | $2.04B | $1.97B | $1.94B | $1.89B | $1.94B | · | $1.85B | $1.66B | $1.03B | · | |
| Other Current Assets | $292M | $265M | $224M | $259M | $266M | $255M | $220M | $261M | $334M | $285M | · | $252M | $292M | $176M | · | |
| Current Assets | $3.45B | $3.40B | $2.94B | $3.27B | $3.52B | $3.46B | $3.38B | $3.07B | $3.21B | $3.15B | · | $3.07B | $2.92B | $1.78B | · | |
| PP&E (Net) | $57.16B | $56.13B | · | $55.62B | $54.46B | $56.16B | · | $53.24B | $53.47B | $52.69B | · | $52.26B | $51.18B | $22.55B | · | |
| Goodwill | $19.11B | $18.75B | $18.44B | $18.72B | $18.35B | $19.33B | $19.35B | $18.16B | $18.41B | $18.23B | $17.73B | $18.15B | $17.67B | · | $344M | |
| Intangibles | $2.97B | $2.94B | $2.91B | $2.98B | $2.94B | $3.12B | $3.15B | $2.97B | $3.04B | $3.03B | $2.97B | $3.06B | $3.02B | · | $42M | |
| Other Non-current Assets | $727M | $753M | $734M | $746M | $669M | $690M | $668M | $620M | $596M | $587M | · | $568M | $585M | $413M | · | |
| Total Assets | $89.28B | $87.68B | $85.94B | $86.69B | $85.18B | $88.04B | $87.74B | $82.22B | $82.79B | $81.67B | · | $81.00B | $79.17B | $73.50B | · | |
| Accounts Payable | $2.91B | $2.63B | $2.75B | $2.90B | $2.74B | $2.73B | $2.84B | $2.59B | $2.61B | $2.52B | · | $2.60B | $2.43B | $1.58B | · | |
| Accrued Liabilities | · | · | $597M | · | · | · | $732M | · | · | · | · | · | · | · | · | |
| Short-term Debt | · | · | $1.17B | · | · | · | $1.59B | · | · | · | · | · | · | $0 | · | |
| Current Liabilities | $5.81B | $5.07B | $5.99B | $5.20B | $3.78B | $4.25B | $5.66B | $5.80B | $6.28B | $6.42B | · | $4.39B | $4.34B | $2.68B | · | |
| Capital Leases | · | · | $299M | · | · | · | $254M | · | · | · | · | · | · | · | · | |
| Deferred Tax | $12.16B | $11.97B | $11.83B | $11.75B | $11.61B | $12.00B | $11.97B | $11.24B | $11.34B | $11.24B | · | $11.22B | $11.08B | $12.22B | · | |
| Other Non-current Liabilities | $910M | $811M | $815M | $944M | $875M | $866M | $867M | $817M | $812M | $832M | · | $799M | $834M | $484M | · | |
| Total Liabilities | $41.67B | $40.27B | $39.12B | $40.03B | $38.03B | $38.80B | $38.85B | $37.15B | $37.97B | $37.91B | · | $38.74B | $38.17B | $33.98B | · | |
| Total Debt | · | · | · | · | · | · | · | · | · | · | · | · | · | $0 | · | |
| Common Stock | $24.36B | $24.62B | $24.75B | $24.82B | $25.29B | $25.60B | $25.69B | $25.67B | $25.66B | $25.63B | · | $25.58B | $25.56B | $25.54B | · | |
| Retained Earnings | $19.73B | $19.94B | $19.78B | $19.18B | $19.86B | $19.88B | $19.43B | $18.41B | $17.75B | $17.02B | · | $15.57B | $14.97B | $13.82B | · | |
| AOCI | $2.42B | $1.77B | $1.24B | $1.60B | $951M | $2.65B | $2.68B | $-28M | $379M | $77M | · | $66M | $-544M | $74M | · | |
| Stockholders' Equity | $46.63B | $46.45B | $45.88B | $45.70B | $46.20B | $48.25B | $47.89B | $44.14B | $43.87B | $42.82B | · | $41.31B | $40.08B | $39.52B | · | |
| Liabilities + Equity | $89.28B | $87.68B | $85.94B | $86.69B | $85.18B | $88.04B | $87.74B | $82.22B | $82.79B | $81.67B | · | $81.00B | $79.17B | $73.50B | · | |
| Shares Outstanding | 882,000,000 | 892,600,000 | 897,600,000 | 901,100,000 | 917,900,000 | 930,400,000 | 933,500,000 | 933,300,000 | 933,100,000 | 932,600,000 | · | 931,700,000 | 931,400,000 | 930,900,000 | · |
Грошовий потік
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| D&A | $519M | $512M | $519M | $503M | $493M | $504M | $488M | $472M | $473M | $467M | $457M | $451M | $410M | $225M | $219M | |
| Deferred Tax | $54M | $15M | $147M | $-11M | $9M | $26M | $-12M | $5M | $18M | $17M | $41M | $3M | $-7.95B | $24M | $-15M | |
| Amort. of Intangibles | · | · | · | · | · | · | · | · | · | · | · | $22M | · | · | · | |
| Other Non-cash | $129M | $-397M | · | $-138M | $-381M | $-284M | · | $-42M | $-118M | $-244M | · | $-207M | $7.11B | $-168M | · | |
| Operating Cash Flow | $1.73B | $976M | $1.52B | $1.27B | $1.35B | $1.16B | $1.70B | $1.27B | $1.28B | $1.01B | $1.34B | $1.03B | $892M | $881M | $1.72B | |
| CapEx | $758M | $664M | $788M | $860M | $743M | $711M | $742M | $748M | $808M | $527M | $702M | $733M | $628M | $405M | $539M | |
| Investing Cash Flow | $-762M | $-672M | $-762M | $-882M | $-306M | $-715M | $-712M | $-760M | $-782M | $-542M | $-402M | $-742M | $-617M | $-401M | $-518M | |
| Debt Issued | · | · | · | · | · | · | · | · | · | · | · | · | · | · | $10.70B | |
| Stock Issued | $30M | $25M | $21M | $14M | $30M | $8M | $14M | $13M | $20M | $22M | $19M | $13M | $19M | $18M | $14M | |
| Stock Repurchased | $1.28B | $680M | $397M | $1.80B | $1.39B | $347M | $0 | $0 | $0 | $0 | · | · | · | · | · | |
| Net Stock Activity | $-1.25B | $-655M | · | $-1.79B | $-1.36B | $-339M | · | $13M | $20M | $22M | · | $13M | $19M | $18M | · | |
| Dividends Paid | $204M | $204M | $204M | $205M | $210M | $177M | $177M | $177M | $178M | $177M | $177M | $177M | $176M | $177M | $177M | |
| Financing Cash Flow | $-1.03B | $-81M | $-979M | $-782M | $-901M | $-484M | $-761M | $-596M | $-464M | $-431M | $-753M | $-324M | $-233M | $-645M | $-888M | |
| Net Change in Cash | $-43M | $225M | $-227M | $-388M | $104M | $-44M | $276M | $-94M | $38M | $55M | $170M | $-31M | $35M | $-161M | $313M | |
| Taxes Paid | $286M | $291M | $305M | $204M | $409M | $237M | $234M | $173M | $309M | $242M | $258M | $205M | $259M | $184M | $89M | |
| Free Cash Flow | $968M | $312M | · | $414M | $612M | $445M | · | $524M | $470M | $488M | · | $294M | $264M | $476M | · |
Прибутковість
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Margin | 35.4% | 34.0% | · | 36.5% | 36.3% | 34.7% | · | 33.9% | 35.2% | 32.6% | · | 35.1% | 29.7% | 36.6% | · | |
| Net Margin | 24.6% | 22.9% | · | 25.1% | 33.4% | 24.0% | · | 23.6% | 25.1% | 22.0% | · | 23.4% | 41.7% | 35.3% | · | |
| Pretax Margin | 32.6% | 30.3% | · | 33.1% | 43.0% | 31.6% | · | 31.0% | 33.2% | 29.3% | · | 31.1% | -200.0% | 42.5% | · | |
| EBITDA Margin | 47.8% | 47.8% | · | 50.2% | 49.6% | 48.0% | · | 47.2% | 48.3% | 45.9% | · | 48.6% | 42.7% | 46.5% | · | |
| ROA | 1.2% | 0.96% | · | 1.1% | 1.5% | 1.1% | · | 1.0% | 1.1% | 1.0% | · | 1.0% | 1.8% | 1.1% | · | |
| ROE | 2.2% | 1.8% | · | 2.1% | 2.7% | 2.0% | · | 2.0% | 2.2% | 1.9% | · | 2.0% | 3.5% | 2.2% | · | |
| ROIC | 2.4% | 2.0% | · | 2.2% | 2.2% | 2.1% | · | 2.1% | 2.2% | 2.0% | · | 2.1% | -0.49% | 1.7% | · |
Ліквідність та платоспроможність
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current Ratio | 0.6 | 0.7 | · | 0.6 | 0.9 | 0.8 | · | 0.5 | 0.5 | 0.5 | · | 0.7 | 0.7 | 0.7 | · | |
| Quick Ratio | 0.5 | 0.5 | · | 0.5 | 0.7 | 0.6 | · | 0.4 | 0.4 | 0.4 | · | 0.6 | 0.5 | 0.5 | · | |
| Debt / Equity | · | · | · | · | · | · | · | · | · | · | · | · | · | 0.0 | · |
Ефективність
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Asset Turnover | 0.0 | 0.0 | · | 0.0 | 0.0 | 0.0 | · | 0.0 | 0.0 | 0.0 | · | 0.0 | 0.0 | 0.0 | · | |
| Receivables Turnover | 2.0 | 1.7 | · | 1.8 | 1.9 | 1.9 | · | 1.9 | 2.0 | 2.4 | · | 2.3 | 2.4 | 2.5 | · |
На акцію
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Book Value / Share | $52.86 | $52.04 | · | $50.71 | $50.34 | $51.86 | · | $47.30 | $47.02 | $45.91 | · | $44.34 | $43.03 | $42.45 | · | |
| Revenue / Share | $4.69 | $4.12 | · | $4.02 | $4.00 | $4.06 | · | $3.79 | $3.86 | $3.77 | · | $3.58 | $3.40 | $2.43 | · | |
| Cash Flow / Share | $1.95 | $1.09 | · | $1.40 | $1.47 | $1.24 | · | $1.36 | $1.37 | $1.09 | · | $1.10 | $0.96 | $0.94 | · | |
| Cash / Share | $0.41 | $0.46 | · | $0.46 | $0.87 | $0.75 | · | $0.50 | $0.60 | $0.56 | · | $0.32 | $0.35 | $0.31 | · | |
| Dividend / Share | $0.27 | $0.23 | $0.23 | $0.23 | $0.23 | $0.19 | $0.19 | $0.19 | $0.19 | $0.19 | $0.19 | $0.19 | $0.19 | $0.19 | $0.19 | |
| EPS (TTM) | $4.30 | $4.48 | · | $4.59 | $4.48 | $4.12 | · | $3.79 | $3.73 | $4.18 | · | $4.48 | $4.60 | $4.00 | · |
Оцінка (TTM)
| Метрика | Тенденція | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | Q2 2024 | Q1 2024 | Q4 2023 | Q3 2023 | Q2 2023 | Q1 2023 | Q4 2022 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue TTM | $15.45B | $14.98B | · | $15.03B | $14.92B | $14.82B | · | $14.45B | $14.24B | $13.81B | · | $11.24B | $10.21B | $9.24B | · | |
| Net Income TTM | $3.87B | $4.08B | · | $4.26B | $4.18B | $3.85B | · | $3.54B | $3.48B | $3.90B | · | $4.17B | $4.29B | $3.73B | · | |
| Market Cap | $76.43B | $70.21B | · | $67.12B | $72.76B | $65.32B | · | $79.83B | $73.46B | $82.23B | · | $69.33B | $75.23B | $71.62B | · | |
| Enterprise Value | · | · | · | · | · | · | · | · | · | · | · | · | · | $71.33B | · | |
| P/E | 20.2 | 17.6 | · | 16.2 | 17.7 | 17.0 | · | 22.6 | 21.1 | 21.1 | · | 16.6 | 17.6 | 19.2 | · | |
| P/S | 4.9 | 4.7 | · | 4.5 | 4.9 | 4.4 | · | 5.5 | 5.2 | 6.0 | · | 6.2 | 7.4 | 7.7 | · | |
| P/B | 1.6 | 1.5 | · | 1.5 | 1.6 | 1.4 | · | 1.8 | 1.7 | 1.9 | · | 1.7 | 1.9 | 1.8 | · | |
| P / Tangible Book | 3.1 | 2.8 | · | 2.8 | 2.9 | 2.5 | · | 3.5 | 3.3 | 3.8 | · | 3.4 | 3.9 | 1.8 | · | |
| P / Cash Flow | 44.3 | 71.9 | · | 52.7 | 53.7 | 56.5 | · | 62.8 | 57.5 | 81.0 | · | 67.5 | 84.3 | 81.3 | · | |
| EV / Revenue | · | · | · | · | · | · | · | · | · | · | · | · | · | 7.7 | · | |
| Dividend Yield | 1.1% | 1.2% | · | 1.1% | 1.0% | 1.1% | · | 0.89% | 0.97% | 0.86% | · | 1.0% | 0.94% | 0.99% | · | |
| Earnings Yield | 5.0% | 5.7% | · | 6.2% | 5.7% | 5.9% | · | 4.4% | 4.7% | 4.7% | · | 6.0% | 5.7% | 5.2% | · | |
| Payout Ratio | 19.9% | 24.1% | · | 22.3% | 17.0% | 19.4% | · | 21.1% | 19.7% | 22.8% | · | 22.7% | 13.3% | 22.1% | · | |
| Annual Payout | $817M | $823M | · | $769M | $741M | $709M | · | $709M | $709M | $707M | · | $707M | $707M | $707M | · |
Найновіший період ліворуч · нульові значення показані як ·
Фінансова звітність Звіт про прибутки та збитки, баланс, рух грошових коштів — річні, за останні 5 років
| Метрика | 2025-12-31 | 2024-12-31 | 2023-12-31 | 2022-12-31 | 2021-12-31 |
|---|---|---|---|---|---|
| Виручка | $15.08B | $14.55B | $12.55B | $8.81B | $8.00B |
| Чистий прибуток | $4.14B | $3.72B | $3.93B | $3.52B | $2.85B |
| Розбавлений EPS | $4.51 | $3.98 | $4.21 | $3.77 | $4.18 |
Ще недостатньо фундаментальних даних для побудови цього звіту.
Ще недостатньо фундаментальних даних для побудови цього звіту.
Інституційні власники (13F) 1 061 подавач звітності · $56.7B всього · Станом на 30 вересня 2026 р.
Інституційні інвестори, які звітують про володіння цими акціями у своїй квартальній формі SEC 13F. Тільки довгі позиції; один подавець звітності може з'явитися двічі для окремих опціонних контрактів. Великі протилежні опціонні позиції (пут/кол) зазвичай відображають маркет-мейкінг або хеджування запасів, а не спрямованість переконань.
| Нові позиції | Закриті позиції | Збільшено | Зменшено | Зміна чистих акцій |
|---|---|---|---|---|
| 99 (-18 проти попереднього кв.) | 53 (-33 проти попереднього кв.) | 335 (+29 проти попереднього кв.) | 308 (-31 проти попереднього кв.) | +28.3M |
Порівняно з Q1 2026. Звіти SEC Form 13F подаються протягом 45 днів після закінчення кварталу плюс невеликий буфер для тих, хто подає із запізненням — квартали, що ще знаходяться в цьому вікні, пропускаються на користь останньої повністю звітної пари.
| Інституційний інвестор | Вартість | Акції | % від відстежуваного 13F | Тип |
|---|---|---|---|---|
| ROYAL BANK OF CANADA | $4 699 603 000 | 54 236 633 | 8,29% | Акції |
| TCI FUND MANAGEMENT LTD | $3 925 911 608 | 45 325 726 | 6,92% | Акції |
| VANGUARD GROUP INC | $2 799 894 365 | 38 030 675 | 4,94% | Акції |
| JPMORGAN CHASE & CO | $2 291 801 857 | 26 369 828 | 4,04% | Акції |
| VANGUARD CAPITAL MANAGEMENT LLC | $2 129 789 516 | 24 565 613 | 3,76% | Акції |
| FMR LLC | $2 107 951 391 | 24 316 233 | 3,72% | Акції |
| MACKENZIE FINANCIAL CORP | $2 096 384 264 | 17 049 319 | 3,70% | Акції |
| FIL Ltd | $1 839 614 023 | 21 218 898 | 3,24% | Акції |
| Invesco Ltd. | $1 773 296 409 | 20 465 048 | 3,13% | Акції |
| BANK OF MONTREAL /CAN/ | $1 722 382 431 | 19 886 289 | 3,04% | Акції |
| WCM INVESTMENT MANAGEMENT, LLC | $1 328 142 284 | 15 281 812 | 2,34% | Акції |
| TD Asset Management Inc | $1 264 350 251 | 14 588 459 | 2,23% | Акції |
| 1832 Asset Management L.P. | $1 220 607 616 | 14 086 643 | 2,15% | Акції |
| NORGES BANK | $1 184 358 416 | 13 671 726 | 2,09% | Акції |
| GEODE CAPITAL MANAGEMENT, LLC | $859 455 799 | 9 777 885 | 1,52% | Акції |
| MASSACHUSETTS FINANCIAL SERVICES CO /MA/ | $820 529 037 | 4 248 626 | 1,45% | Акції |
| GOLDMAN SACHS GROUP INC | $806 425 200 | 9 306 696 | 1,42% | Акції |
| Connor, Clark & Lunn Investment Management Ltd. | $802 982 742 | 9 270 972 | 1,42% | Акції |
| VANGUARD FIDUCIARY TRUST CO | $682 338 402 | 7 870 290 | 1,20% | Акції |
| MANUFACTURERS LIFE INSURANCE COMPANY, THE | $657 672 153 | 7 600 778 | 1,16% | Акції |
| CIBC WORLD MARKET INC. | $656 575 303 | 7 579 771 | 1,16% | Акції |
| NATIONAL BANK OF CANADA /FI/ | $610 327 795 | 7 056 476 | 1,08% | Акції |
| Legal & General Group Plc | $604 797 145 | 6 978 871 | 1,07% | Акції |
| CAUSEWAY CAPITAL MANAGEMENT LLC | $581 660 870 | 6 711 483 | 1,03% | Акції |
| MORGAN STANLEY | $546 453 587 | 6 306 445 | 0,96% | Акції |
| CANADA PENSION PLAN INVESTMENT BOARD | $542 468 611 | 6 263 236 | 0,96% | Акції |
| TD Waterhouse Canada Inc. | $532 625 627 | 6 189 760 | 0,94% | Акції |
| JANUS HENDERSON GROUP PLC | $530 551 016 | 6 749 527 | 0,94% | Акції |
| DZ BANK AG Deutsche Zentral Genossenschafts Bank, Frankfurt am Main | $501 863 363 | 5 790 040 | 0,88% | Акції |
| Fiera Capital Corp | $497 824 938 | 5 752 356 | 0,88% | Акції |
| Veritas Asset Management LLP | $496 319 676 | 5 727 867 | 0,88% | Акції |
| CIBC Asset Management Inc | $488 282 825 | 5 620 145 | 0,86% | Акції |
| Rothschild & Co Wealth Management UK Ltd | $452 604 069 | 5 223 365 | 0,80% | Акції |
| Allspring Global Investments Holdings, LLC | $442 158 326 | 5 146 163 | 0,78% | Акції |
| Federation des caisses Desjardins du Quebec | $424 584 173 | 4 924 762 | 0,75% | Акції |
| Select Equity Group, L.P. | $376 770 450 | 4 346 986 | 0,66% | Акції |
| Fayez Sarofim & Co | $355 651 718 | 4 104 463 | 0,63% | Акції |
| Vanguard Global Advisers, LLC | $327 650 816 | 3 779 220 | 0,58% | Акції |
| BARCLAYS PLC | $325 595 611 | 3 757 595 | 0,57% | Акції |
| SCOTIA CAPITAL INC. | $313 030 835 | 3 624 243 | 0,55% | Акції |
| Fisher Asset Management, LLC | $308 430 006 | 3 559 491 | 0,54% | Акції |
| Sustainable Growth Advisers, LP | $281 369 186 | 3 247 192 | 0,50% | Акції |
| BANK OF AMERICA CORP /DE/ | $276 899 823 | 3 195 613 | 0,49% | Акції |
| Clearbridge Investments, LLC | $257 377 540 | 2 970 312 | 0,45% | Акції |
| TORONTO DOMINION BANK | $250 295 410 | 2 889 961 | 0,44% | Акції |
| Swiss National Bank | $249 299 412 | 2 883 893 | 0,44% | Акції |
| PICTON MAHONEY ASSET MANAGEMENT | $244 733 450 | 2 829 879 | 0,43% | Акції |
| AMERICAN CENTURY COMPANIES INC | $229 594 060 | 2 648 571 | 0,40% | Акції |
| Caisse de depot et placement du Quebec | $228 401 829 | 2 635 370 | 0,40% | Акції |
| FRANKLIN RESOURCES INC | $227 565 127 | 2 626 427 | 0,40% | Акції |
Активісти та власники %+ 5 1 холдинг
Інвестори, які подали Розклад SEC 13D — бенефіціарна власність понад 5% з наміром вплинути на емітента (активістські частки, кампанії в раді директорів, M&A). Кожен рядок показує останній відомий стан позиції цього подавця.
| Подавець | Подано | Частка | Статус | Мета | Подача |
|---|---|---|---|---|---|
| Pershing Square Capital Management, L.P., PS Management GP, LLC, William A. Ackman ×17 подання | 05 серпня 2016 р. | · | Первинна подача | · | SEC |
Purpose is an automated classification of the filer's own stated purpose (SEC Item 4) — not investment advice. "—" means no clear purpose was stated or the text could not be classified.
Інсайдери компанії 24 інсайдери · 14 керівники · 11 директори
| Інсайдер | Роль | Остання активність | Кількість акцій у власності | Купівлі за 12 міс. | Продажі за 12 міс. | Нетто 12 міс |
|---|---|---|---|---|---|---|
| Keith Edward Creel | President & CEO | 30 червня 2017 р. J | 2 087 | 0 | 0 | $0 |
| Hunter E Harrison | Chief Executive Officer | 20 січня 2017 р. S | 0 | 0 | 0 | $0 |
| Nadeem Velani | VP and CFO | 30 червня 2017 р. J | 340 | 0 | 0 | $0 |
| Mark J Erceg | EVP & CFO | 31 серпня 2016 р. J | 371 | 0 | 0 | $0 |
| John E Derry | Vice-President Human Resources | 30 червня 2017 р. J | 242 | 0 | 0 | $0 |
| John Kenneth Brooks | SVP & Chief Marketing Officer | 30 червня 2017 р. J | 1 587 | 0 | 0 | $0 |
| James Dominic Luther Clements | VP Planning & Transportation | 30 червня 2017 р. J | 1 921 | 0 | 0 | $0 |
| Mike Foran | VP Network Transportation | 30 червня 2017 р. J | 1 591 | 0 | 0 | $0 |
| Robert Allen Johnson | Executive VP Operations | 30 червня 2017 р. J | 97 | 0 | 0 | $0 |
| Jeffrey Jerom Ellis | Chief Legal Officer & Corp Sec | 30 червня 2017 р. J | 299 | 0 | 0 | $0 |
| Michael John Redeker | VP & Chief Information Officer | 30 червня 2017 р. J | 951 | 0 | 0 | $0 |
| Peter John Edwards | VP People | 02 травня 2017 р. J | 2 456 | 0 | 0 | $0 |
| Laird Joseph Pitz | VP & Chief Risk Officer | 24 квітня 2017 р. A | · | 0 | 0 | $0 |
| Mark Kenneth Wallace | VP Corp Affrs & Chief of Staff | 26 січня 2017 р. S | 45 | 0 | 0 | $0 |
| Gordon T. Trafton II | Директор | 30 червня 2017 р. A | · | 0 | 0 | $0 |
| William R. Fatt | Директор | 30 червня 2017 р. A | · | 0 | 0 | $0 |
| John Russell Baird | Директор | 30 червня 2017 р. A | · | 0 | 0 | $0 |
| Isabelle Courville | Директор | 30 червня 2017 р. A | · | 0 | 0 | $0 |
| Ubavka Rebecca Macdonald | Директор | 30 червня 2017 р. A | 0 | 0 | 0 | $0 |
| Andrew Fitzpatrick Reardon | Директор | 30 червня 2017 р. A | · | 0 | 0 | $0 |
| Jane L Peverett | Директор | 30 червня 2017 р. A | · | 0 | 0 | $0 |
| Matthew H Paull | Директор | 30 червня 2017 р. A | 1 000 | 0 | 0 | $0 |
| Anthony Ronald Melman | Директор | 30 червня 2016 р. J | · | 0 | 0 | $0 |
| Gillian H Denham | · | 30 червня 2017 р. A | · | 0 | 0 | $0 |
Інсайдери згідно з формами SEC 3/4/5; чистий результат = лише відкритий ринок купівлі/продажу
Присутність в ETF Належить 61 ETF
Вага відображає лише прямі акціонерні володіння (N-PORT); фонди з кредитним плечем або похідними інструментами можуть мати додаткову експозицію за свопами, яка не відображається.
| Фонд | Вага | Одиниці | Станом на | Джерело |
|---|---|---|---|---|
| SHPP · Pacer Funds Trust | 4,07% | 949 NS | 31 липня 2026 р. | N-PORT |
| NFRA · FlexShares Trust | 3,74% | 1 267 296 NS | 31 липня 2026 р. | N-PORT |
| ASLV · ALLSPRING EXCHANGE-TRADED FUNDS TRU… | 3,56% | 87 648 NS | 31 липня 2026 р. | N-PORT |
| BBCA · J.P. Morgan Exchange-Traded Fund Tr… | 2,58% | 3 153 645 NS | 31 липня 2026 р. | N-PORT |
| EWC · iShares, Inc. | 2,56% | 1 964 499 SH | 11 вересня 2026 р. | Щоденно |
| MTRA · Invesco Actively Managed Exchange-T… | 1,77% | 27 986 SH | 05 жовтня 2026 р. | Щоденно |
| SUPP · TCW ETF Trust | 1,59% | 2 134 NS | 31 липня 2026 р. | N-PORT |
| AGRW · ALLSPRING EXCHANGE-TRADED FUNDS TRU… | 1,24% | 15 706 NS | 31 липня 2026 р. | N-PORT |
| EXI · iShares Trust | 0,80% | 127 604 SH | 11 вересня 2026 р. | Щоденно |
| IQRA · New York Life Investments Active ET… | 0,64% | 495 NS | 31 липня 2026 р. | N-PORT |
| ESLV · Strategy Shares | 0,63% | 1 004 NS | 31 липня 2026 р. | N-PORT |
| BSCQ · Invesco Exchange-Traded Self-Indexe… | 0,50% | 16 176 000 | 05 жовтня 2026 р. | Щоденно |
| IDLV · Invesco Exchange-Traded Fund Trust … | 0,46% | 16 895 SH | 05 жовтня 2026 р. | Щоденно |
| SPWO · SP Funds Trust | 0,40% | 9 095 NS | 31 липня 2026 р. | N-PORT |
| PTIN · Pacer Funds Trust | 0,33% | 6 857 NS | 31 липня 2026 р. | N-PORT |
| PICB · Invesco Exchange-Traded Fund Trust … | 0,31% | 1 550 000 | 05 жовтня 2026 р. | Щоденно |
| BKIE · BNY Mellon ETF Trust | 0,31% | 45 409 NS | 31 липня 2026 р. | N-PORT |
| IMFL · Invesco Exchange-Traded Self-Indexe… | 0,30% | 37 690 SH | 05 жовтня 2026 р. | Щоденно |
| IMTM · iShares Trust | 0,30% | 144 367 SH | 11 вересня 2026 р. | Щоденно |
| BSCU · Invesco Exchange-Traded Self-Indexe… | 0,28% | 8 197 000 | 05 жовтня 2026 р. | Щоденно |
| IDEV · iShares Trust | 0,27% | 969 448 SH | 11 вересня 2026 р. | Щоденно |
| DFIV · Dimensional ETF Trust | 0,25% | 596 263 NS | 31 липня 2026 р. | N-PORT |
| VEA · VANGUARD TAX-MANAGED FUNDS | 0,23% | 8 680 756 SH | 19 серпня 2026 р. | Щоденно |
| ACWX · iShares Trust | 0,21% | 296 158 SH | 11 вересня 2026 р. | Щоденно |
| DFAI · Dimensional ETF Trust | 0,20% | 399 978 NS | 31 липня 2026 р. | N-PORT |
| GLBL · Pacer Funds Trust | 0,19% | 24 NS | 31 липня 2026 р. | N-PORT |
| VEU · VANGUARD INTERNATIONAL EQUITY INDEX… | 0,19% | 2 078 284 SH | 19 серпня 2026 р. | Щоденно |
| IXUS · iShares Trust | 0,18% | 1 224 829 SH | 11 вересня 2026 р. | Щоденно |
| ESUM · Strategy Shares | 0,18% | 3 586 NS | 31 липня 2026 р. | N-PORT |
| VXUS · VANGUARD STAR FUNDS | 0,17% | 13 051 885 SH | 19 серпня 2026 р. | Щоденно |
| QLVD · FlexShares Trust | 0,16% | 960 NS | 31 липня 2026 р. | N-PORT |
| PXF · Invesco Exchange-Traded Fund Trust … | 0,15% | 52 067 SH | 05 жовтня 2026 р. | Щоденно |
| TLTD · FlexShares Trust | 0,14% | 10 362 NS | 31 липня 2026 р. | N-PORT |
| ACVF · ETF Opportunities Trust | 0,13% | 2 274 NS | 31 липня 2026 р. | N-PORT |
| BSCT · Invesco Exchange-Traded Self-Indexe… | 0,13% | 4 020 000 | 05 жовтня 2026 р. | Щоденно |
| BSCS · Invesco Exchange-Traded Self-Indexe… | 0,11% | 4 025 000 | 05 жовтня 2026 р. | Щоденно |
| ESIM · Strategy Shares | 0,10% | 201 NS | 31 липня 2026 р. | N-PORT |
| VOXP · Advisors Series Trust | 0,10% | 63 NS | 31 липня 2026 р. | N-PORT |
| TOK · iShares Trust | 0,10% | 2 534 SH | 11 вересня 2026 р. | Щоденно |
| URTH · iShares, Inc. | 0,09% | 79 986 SH | 11 вересня 2026 р. | Щоденно |
| DFIC · Dimensional ETF Trust | 0,08% | 128 849 NS | 31 липня 2026 р. | N-PORT |
| ACWI · iShares Trust | 0,08% | 281 044 SH | 11 вересня 2026 р. | Щоденно |
| VT · VANGUARD INTERNATIONAL EQUITY INDEX… | 0,07% | 752 781 SH | 19 серпня 2026 р. | Щоденно |
| CRBN · iShares Trust | 0,07% | 9 079 SH | 11 вересня 2026 р. | Щоденно |
| DFAX · Dimensional ETF Trust | 0,06% | 77 551 NS | 31 липня 2026 р. | N-PORT |
| DXIV · Dimensional ETF Trust | 0,04% | 829 NS | 31 липня 2026 р. | N-PORT |
| GTO · Invesco Actively Managed Exchange-T… | 0,01% | 277 000 | 05 жовтня 2026 р. | Щоденно |
| GTOS · Invesco Actively Managed Exchange-T… | 0,00% | 5 000 | 30 вересня 2026 р. | Щоденно |
| FTLS · First Trust Exchange-Traded Fund III | -0,18% | -51 790 NS | 31 липня 2026 р. | N-PORT |
| BIV · VANGUARD BOND INDEX FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| BLV · VANGUARD BOND INDEX FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| BSV · VANGUARD BOND INDEX FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| BND · VANGUARD BOND INDEX FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| VCRB · VANGUARD MALVERN FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| VPLS · VANGUARD MALVERN FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| VCSH · VANGUARD SCOTTSDALE FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| VCIT · VANGUARD SCOTTSDALE FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| VCLT · VANGUARD SCOTTSDALE FUNDS | · | · | 15 липня 2026 р. | Щоденно |
| VTC · VANGUARD SCOTTSDALE FUNDS | · | · | 30 липня 2026 р. | Щоденно |
| BNDW · VANGUARD SCOTTSDALE FUNDS | · | · | 30 липня 2026 р. | Щоденно |
| BNDX · VANGUARD CHARLOTTE FUNDS | · | · | 15 липня 2026 р. | Щоденно |
CP Консенсус аналітиків Бичачі та ведмежі думки аналітиків, 12-місячна цільова ціна, потенціал зростання
12-місячна цільова ціна
13 аналітиків · 2026-10-03Середня цільова ціна $98.06 +14,8%
Останні новини Останні заголовки, що згадують цю компанію
Мої показники Ваш персональний список спостереження — вибрані рядки з Повних фундаментальних даних
Виберіть показники, які для вас важливі — натисніть + поруч із будь-яким рядком у розділі Повна фундаментальна інформація вище.
Ваш вибір збережено і він буде застосовуватися до всіх тікерів.